



PW Consulting: Monocyanamide Market to Grow at a 4.34% CAGR During 2026–2032, New Report Finds

Monocyanamide Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Brief
Executive summary
PW Consulting’s new Monocyanamide Market report (base year 2025, forecast period 2026–2032) provides the decision-grade intelligence chemical, agricultural, and electronics sector leaders need to make high-stakes choices in 2026. The global monocyanamide market has expanded steadily from an estimated USD 224.9 Million in 2020 to approximately USD 278.1 Million in 2025 and is projected to reach roughly USD 374.3 Million by 2032, progressing at a compound annual growth rate (CAGR) of 4.34% over the forecast window. These headline dynamics mask important operational, regulatory and quality-driven inflection points that will determine winners and laggards through 2026 and beyond.
Monocyanamide Market
Why this matters for 2026 strategy
- Demand is resilient but selective. Modest but steady volume growth underpins broad industry interest; however, end-users are increasingly differentiating on product grade (standard vs. electronic/pharmaceutical) and on downstream integration into higher-value specialty molecules.
- Supply-side concentration shapes negotiation leverage. The market displays high concentration among a few large suppliers. This structural reality amplifies the commercial and operational consequences of single-facility outages, strategic capex decisions, or product-grade investments by leading producers.
- Raw-material exposure is material to margins. A dominant portion of operating cost in monocyanamide manufacture is driven by calcium cyanamide and related upstream inputs—an exposure that translates volatility in upstream markets directly into margin pressure for producers and price risk for buyers.
- Quality and regulatory alignment are emerging differentiators. Demand for high-purity grades in electronics and pharmaceuticals is accelerating, and regulatory moves in some markets are amplifying the value of certified, lower-impurity supply chains.
Key market dynamics to track in 2026
- Price and cost signals: Short-cycle price indicators from the first quarter of 2026 show material per-ton pricing that traders and procurement teams should use as inputs to scenario models and hedging strategies. Given the upstream cost composition, even moderate swings in cyanamide-related raw materials can have outsized effects on producer economics.
- Capex and capacity timing: Several strategic investments announced by major non-Chinese producers will change grade-availability dynamics for electronic- and pharmaceutical-grade monocyanamide beginning in the second half of 2026. Executives should map supplier capex calendars into their sourcing timelines to avoid procurement mismatches.
- Regulatory and ESG pressure: Environmental controls on ammonia-related and cyanamide feedstocks, as well as tighter scrutiny of supply chains for critical electronic inputs, are likely to drive higher compliance costs and create selective advantages for producers that have invested in cleaner upstream profiles or local production near high-regulation markets.
- Geopolitical and trade-side noise: While no monocyanamide-specific tariffs emerged in 2025, broader trade measures and export controls in adjacent chemical sectors can create indirect supply-chain ripple effects. Buyers should stress-test supply networks under modest trade disruption scenarios.
Competitive landscape — what the data implies
The market’s concentration metrics indicate that the top three players account for a dominant share of supply, with the top five capturing an even larger share. This has several pragmatic implications:
Monocyanamide Market
- Margin management and premium positioning: Large integrated producers—especially those that can source or vertically integrate upstream calcium-cyanamide feeds—enjoy structural cost advantages. At the same time, suppliers that invest in purification and quality-certification can command premiums for electronic- and pharmaceutical-grade product lines.
- Supplier risk and diversification: The concentration profile increases the strategic value of diversified supply contracts, dual-sourcing agreements, and regional inventory hubs for buyers seeking continuity of supply.
- M&A and partnership windows: High concentration lowers the number of strategically meaningful acquisition targets but increases the potential strategic impact of bolt-on acquisitions that add grade capabilities or complementary downstream products.
Profiles and recent moves — strategic takeaways
Our supplier analysis highlights a mix of long-established Western producers and a large cohort of Chinese manufacturers supplying global markets. Notable observations include:
Monocyanamide Market
- AlzChem Group AG (Trostberg, Germany): A unique non-Chinese large-scale producer with substantial capacity at its Trostberg site and a focus on high-purity, electronic and pharmaceutical grades. Recent announcements—expanded downstream capacity for nitroguanidine (new plant commissioning targeted in H2 2026) and a capital expenditure program announced in early 2026 to improve electronic-grade purification—signal a strategic push to capture higher-margin specialty demand in Europe. Buyers targeting European electronic manufacturers should prioritize engagement with suppliers making such investments.
- Nippon Carbide Industries Co., Ltd. (Tokyo, Japan): With production experience dating back to the 1930s and an established portfolio covering polymer additives, epoxy curing, and pharmaceutical applications, this supplier represents a profile of long-term reliability and technical know-how—attributes prized by customers in regulated sectors.
- Large China-based cohort: A set of major Chinese manufacturers continues to supply bulk volumes and serves as the backbone of global commodity supply. Their roles are central to feedstock flows and price formation; however, buyers seeking higher-purity grades or regulatory alignment for critical electronics supply chains may face a differentiation trade-off between cost and conformity.
What our report delivers — practical, transaction-ready outputs
PW Consulting’s report is built for immediate operational use by procurement directors, corporate strategists, and M&A teams. Core deliverables include:
- Market-sizing and high-resolution trend models (2020–2032) with scenario stress-tests for demand, price and capex timing.
- Supply-chain maps and supplier risk heatmaps that integrate plant-level announcements and likely outage/maintenance windows—presented in a format that supports contract negotiation or hedging decisions.
- Price modeling templates that use current FOB benchmarks and upstream cost drivers to forecast short- and medium-term price bands for negotiation and budgeting.
- Actionable playbooks for procurement (dual-sourcing templates, inventory thresholds tied to regional lead times, supplier certification checklists for electronic/pharma grades).
- Strategic investment cases and ROI calculators for capex or M&A activity, including sensitivity to raw-material cost changes and regulatory cost projections.
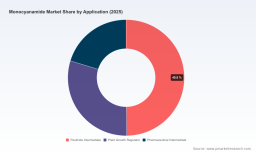
To preserve the commercial integrity of supplier-specific strategies and to guide users to the correct tactical next steps, the report deliberately consolidates but does not publish detailed split-level revenue or percentage shares across regions and applications in this press announcement. Those granular matrices are included in the full report and are essential for transaction execution.
Action roadmap for 2026 — prioritized steps
- Q1 2026 — Price & exposure triage: Run immediate sensitivity checks against the Q1 2026 FOB price signals and your organization’s raw-material exposure. If gross margin sensitivity exceeds internal thresholds, prepare contingency procurement actions.
- Q2 2026 — Supply and quality lock-in: Negotiate dual-sourced contracts with explicit grade and delivery SLAs; prioritize suppliers with announced capex that align with your quality requirements for H2 2026 onward.
- Mid-2026 — Capex & partnership decisions: If pursuing backward integration or JV with upstream calcium-cyanamide producers, target agreements that de-risk at least 60–70% of production OPEX exposure to feedstock cost volatility (our report quantifies typical upstream cost profiles).
- Ongoing — Regulatory & ESG monitoring: Implement a regulatory watch leveraging our compliance matrix to flag changes that would materially alter local sourcing economics or require process investments.
KPIs senior leaders should monitor
- Quarterly FOB benchmark vs. internal cost-of-goods delta
- Percentage of procurement under dual- or multi-sourcing contracts
- Lead-time variance from top three suppliers
- Share of purchases contracted for certified electronic/pharma grades
- Supplier capex announcements vs. anticipated grade-availability windows
Conclusion — the strategic edge for 2026
In a market that is growing steadily but is structurally concentrated and sensitive to upstream raw-material dynamics, 2026 will be the year that separates transactional buyers from strategic, margin-protecting players. Executives who integrate supplier capex calendars, upstream cost exposure, and grade-differentiated demand into procurement and investment decisions will preserve margin and secure continuity in high-value downstream chains. PW Consulting’s Monocyanamide Market report provides the models, supplier intelligence, and execution playbooks to make those decisions with confidence.
Next steps
For access to the full dataset, supplier-level matrices, and our transaction-ready tools, please download the complete report from the PW Consulting website or contact our industry team for a bespoke briefing. Our analysts are prepared to run tailored scenario analyses that align the report’s findings with your 2026 operating and investment calendar.
For detailed analysis of this topic, please visit the official page: Monocyanamide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


