



PW Consulting Predicts IoT MCU Market to Grow at a Robust 12.52% CAGR During 2026–2032

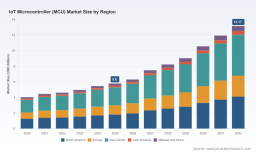
IoT Microcontroller (MCU) Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence
PW Consulting today releases its authoritative market briefing on the IoT Microcontroller (MCU) sector, providing senior executives and investment committees with the strategic context required to make decisive moves in 2026. Anchored on a 2025 base year and a seven-year forecast horizon (2026–2032), the analysis explains why MCUs are shifting from a cost component to a strategic differentiator across consumer, industrial and automotive ecosystems.
IoT Microcontroller (MCU) Market
Why this report matters for 2026 decision-makers
-
Macro momentum: The IoT MCU market that PW Consulting tracked from 2020 through 2025 has entered a rapid expansion phase. Our forecast shows sustained growth into the next decade, with a projected compound annual growth rate (CAGR) of 12.52% across the 2026–2032 window. This trajectory implies that leaders must treat MCU strategy as central to product roadmaps, sourcing plans and security investments, not as a peripheral procurement decision.
IoT Microcontroller (MCU) Market -
Concentration dynamics: Market concentration is moderate — the top three vendors account for a meaningful portion of revenue, and the top five remain collectively influential. That mix creates an environment where tier-1 suppliers can set technical roadmaps and scale economics, yet opportunities remain for focused challengers with differentiated propositions.
IoT Microcontroller (MCU) Market -
Timing is critical: Our base-year vantage (2025) shows the market positioned for accelerated adoption in 2026. Companies that align product feature-sets, compliance programs and supply strategies in the coming 12 months will capture disproportionately higher value over the forecast period.
What the report delivers — operational, actionable intelligence
-
Practical decision templates: executable procurement playbooks, supplier risk scorecards, and BOM-level cost-sensitivity tables calibrated to volatile materials and regional supplier dynamics.
-
Technology roadmaps: comparative analysis of MCU architectures (energy-optimized cores, real-time controllers, and crossover edge-AI platforms) mapped to specific use-case performance and development-effort trade-offs.
-
Security and compliance matrix: end-to-end mapping of certification requirements (including automotive and critical infrastructure standards), and prescriptive steps to achieve compliance without derailing time-to-market.
-
Go-to-market playbook: product segmentation approaches, reference-software stacks, and partner ecosystems that reduce integration risk for device OEMs.
-
Investment and M&A dashboards: scenario models that stress-test valuation assumptions under different consolidation and price-competition scenarios.
Industry dynamics that will shape 2026 strategies
-
Security regulations are accelerating adoption of certified MCUs. Recent rollouts of automotive and IoT security compliance frameworks are not benign policy changes — they reshape supplier selection, vendor certification timelines and total cost of ownership. Organizations integrating connected vehicle or safety-critical capabilities must now bake certification pathways into product development milestones.
-
Pricing pressure from lower-cost suppliers is material and persistent. Independent analyses point to sustained price differentials among supply sources, which has direct implications for margin dynamics and sourcing choices. Buyers need robust scenario planning to balance cost savings against long-term supply-chain and regulatory risk.
-
Materials and labor volatility increase the value of resilient regional supply. The MCU value chain depends on hundreds of specialty materials with concentrated sources; this translates into spot risk for key components and underlines the commercial premium for diversified sourcing and locally assured capabilities.
-
Wireless, security and edge AI are converging at the silicon level. The market is transitioning from single-function MCUs to multifunction SoCs and crossover parts that bundle wireless stacks, security engines and machine learning accelerators — enabling new product capabilities but raising integration complexity.
Competitive landscape — who to watch and why
Our vendor analysis profiles leading and high-impact players across capability bundles, channel coverage and strategic intent. The competitive map shows established incumbents extending into adjacent value pools, and disruptive vendors driving aggressive price-performance moves.
-
Infineon Technologies AG — Infineon’s recent product initiatives underscore a deliberate move to combine ultra-low-power connectivity with strong security credentials. Their new tri-radio Wi‑Fi 7 MCU family and certified automotive/IoT compliance efforts exemplify how a platform-plus-certification strategy can protect higher-margin use cases.
-
NXP Semiconductors — The MCX Arm Cortex-M lineup and crossover i.MX RT parts position NXP at the intersection of edge AI and secure connectivity, making them a natural partner for OEMs that need a rapid route to deployable intelligence at the node.
-
STMicroelectronics — ST’s emphasis on secure, high-performance and ultra-low-power Cortex-based offerings aligns with industrial and smart-node requirements. Their product stack is tailored to customers prioritizing security primitives such as TrustZone.
-
Texas Instruments — TI’s low-power and real-time MCUs, combined with an established RTOS and wide-channel distribution, remain attractive for industrial endpoints where deterministic behavior and ecosystem support matter.
-
Renesas — Renesas continues to focus on ultra-low-power designs with security hardening, targeting metering, home and industrial segments that require long service lifecycles and cloud connectivity.
-
Microchip Technology — Microchip’s broadened Cortex-M family and production-ready edge AI solutions reflect a playbook of modular hardware plus full-stack software — attractive for sensor-node OEMs seeking short integration cycles.
-
Silicon Labs — With wireless SoCs supporting Bluetooth, Zigbee and Matter, Silicon Labs emphasizes low-power wireless stacks and developer tooling, enabling rapid deployments in smart home and constrained industrial applications.
-
Espressif Systems — Espressif’s integrated Wi‑Fi/Bluetooth and RISC‑V efforts continue to pressure price-performance thresholds, particularly for AIoT and multi-protocol use cases where software flexibility is essential.
-
Holtek Semiconductor — Holtek targets cost-sensitive applications with ultra-low-power 8/32-bit devices and wireless-enabled lines that suit consumer and small smart-device markets.
Notable product and compliance milestones (select recent developments)
-
Tier‑1 vendors introduced multi-radio, Wi‑7-capable IoT MCUs and expanded edge‑AI stacks in early 2026 — signaling a next phase of silicon-enabled functionality for node-level intelligence.
-
Key automotive and IoT MCUs have moved through updated certification steps in early 2026, raising the bar on supplier qualification timelines and forcing OEMs to integrate compliance planning into product calendars.
-
Several vendors announced production-ready full-stack edge AI offerings, shortening the path from prototype to high-volume deployment for AI-enabled endpoints.
Strategic implications — five actions for 2026
-
Embed compliance early: Treat certification timelines as a critical path item. Build supplier selection criteria around proven certification programs and maintain certification milestones in product Gantt charts.
-
Adopt a dual-source procurement posture: Balance cost advantages from lower-priced suppliers against geopolitical and regulatory risks. Our procurement playbook lays out threshold tests for where single sourcing is acceptable and where diversification is mandatory.
-
Prioritize platform-based architectures: Choose MCUs that offer an upgrade path — flexible wireless stacks, security acceleration and ML inference capabilities — to protect future feature introductions without repeated hardware redesigns.
-
Hedge on integration services: Secure software and middleware partnerships early. The performance differential in time-to-market increasingly comes from available reference firmware, security libraries and validated dev-kits.
-
Monitor consolidation windows: With mid-level concentration and ongoing margin pressure, strategic buyers and PE sponsors should prepare playbooks for bolt-on acquisition opportunities that accelerate access to differentiated IP or regional capacity.
Risk matrix and scenario planning — what the report hides (and why)
In keeping with PW Consulting’s “trailer” approach to public briefings, this release demonstrates the analytical depth underlying our conclusions — but intentionally omits granular subsegment tables, exact regional shares and proprietary vendor scorecards. These discrete datasets drive the modeled scenarios and vendor-level recommendations in the full report. Organizations that need executable numbers to populate procurement contracts, capital allocation models or M&A valuation decks should consult the complete dataset and interactive models available from PW Consulting.
How executives should use this report
Senior leaders in product, supply chain and corporate development will find the briefing useful to set cadence for 2026 initiatives: align R&D budgets to platform migration timelines; reconcile procurement contracts with exposure to concentrated materials; and prioritize security certifications that unlock regulated market segments. The full report provides the granular inputs and dynamic scenario models required to convert these strategic priorities into measurable KPIs.
Next steps
PW Consulting’s IoT Microcontroller (MCU) Market report is published with interactive tools, vendor scorecards, procurement playbooks and scenario models. To access the full intelligence package, including the confidential segmented datasets and downloadable financial models that informed the strategic recommendations summarized here, please visit our official report page or contact your PW Consulting account representative.
For detailed analysis of this topic, please visit the official page: IoT Microcontroller (MCU) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


