



PW Consulting: Ablation Systems Market to Climb from USD 7.15B in 2025 to USD 13.28B by 2032 at a 9.25% CAGR — North America Leading with USD 2.84B Share

Ablation Systems Market: Strategic Imperatives from PW Consulting’s 2026 Market Research
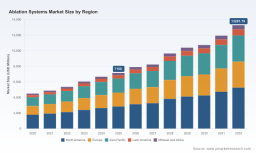
PW Consulting today releases a forward-looking industry perspective drawn from our new Ablation Systems Market Research report — a decision-grade briefing designed to orient executive teams, investors, health systems, and technology partners as they set strategy for 2026 and beyond. Our analysis traces market evolution from a USD 4.5 billion base in 2020 to USD 7.15 billion in 2025 and models a multi-channel expansion through 2032, with the market projected to approach roughly USD 13.3 billion by 2032. The compound annual growth rate during the 2026–2032 forecast window is 9.25% — a pace that rewards timely strategic choices in product, regulatory, and reimbursement execution.
Ablation Systems Market Research
Why 2026 Is an Inflection Point
Several converging forces make 2026 the first practical decision year for companies seeking to accelerate commercialization or defend share in ablation technologies:
Ablation Systems Market Research
- Regulatory momentum: Recent approvals and clearances for pulsed field ablation (PFA), cryoablation, and device-centric robotics have materially altered clinical pathways and hospital adoption scenarios. Notable milestones include late-2024 and 2025 approvals for next‑generation mapping/ablation platforms, multiple 2025 510(k)/marketing authorizations for prostate and breast-local therapies, and a January 2026 clearance enabling robotic-mag‑navigation ablation in select congenital indications. These events compress time-to-adoption for well-positioned technologies.
- Reimbursement architecture shifts: U.S. reimbursement updates — including a finalized concomitant MS‑DRG for certain left atrial appendage closure and ablation procedures and FY2026 IPPS adjustments — change hospital economics for combined procedures and inpatient ablation workflows. These moves alter the incremental revenue and cost calculus for devices that change procedural duration, length-of-stay, or readmission risk.
- Portfolio differentiation across modalities: The market is experiencing parallel advancement across PFA, RF, cryo, microwave, ultrasound, irreversible electroporation, and high‑intensity focused ultrasound (HIFU). Clinical and economic evidence is now the primary gating factor for scaling beyond early adopter centers.
What Our Report Delivers — Practically Actionable, Not Just Academic
PW Consulting’s study is intentionally built to inform executable strategy rather than only describe the market. Core deliverables include:
Ablation Systems Market Research
- Top‑line market sizing and a detailed, reproducible forecasting model (historical 2020–2025, base year 2025, forecast 2026–2032) using a mix of bottom‑up device adoption curves and macro scenario overlays.
- Technology roadmaps that map clinical evidence timelines against regulatory and reimbursement inflection points, enabling prioritization of R&D investments and launch sequencing.
- Go‑to‑market playbooks for hospital and ambulatory settings, including purchase economics, capital planning implications, and bundle pricing recommendations informed by recent IPPS/MS‑DRG changes.
- Clinical evidence and HTA gap analysis to support payer submissions, including comparator frameworks and target endpoints most likely to drive coverage and favorable payment.
- Competitive landscaping with detailed company profiles, new product impact assessments, and a supplier scoring system for capability and execution risk.
- Zones of opportunity: identified niche segments and underserved clinical indications that are attractive for bolt‑on M&A or JV strategies.
- Scenario models and sensitivity analyses (optimistic / base / conservative) that quantify the revenue and margin impacts of alternate technology adoption curves, regulatory timelines, and reimbursement outcomes.
Note: In keeping with our “trailer” approach to this executive summary, we highlight frameworks and directionally indicative numbers here while withholding granular regional, technology-application, and company‑level revenue splits. The full dataset and supporting models are available in the complete report.
Competitive Landscape — Who’s Shaping the Next Phase
The ablation market occupies a middle ground between fragmentary innovation and emerging consolidation. Concentration metrics indicate a market with meaningful leader scale but substantial room for disruption — the top three vendors account for a sizable but not dominant share of market value, and the top five capture less than two-thirds of the market. This dynamic creates both defensive priorities for incumbents and attack vectors for challengers.
- Medtronic — A broad cardiac ablation portfolio that spans cryo and dual‑energy PF/RF approaches positions Medtronic to compete across persistent and paroxysmal atrial fibrillation (AF) segments and in procedure suites that value integrated mapping-to-ablation workflows.
- Boston Scientific — With a PFA system and ongoing investment in RF tumor ablation, Boston Scientific is pursuing a strategy that blends electrophysiology leadership with cross‑therapy oncology opportunities.
- Abbott — Volt PFA and electrophysiology catheter lines make Abbott a direct competitor in the fast‑evolving PFA battlefield focused on AF ablation adoption and scale.
- Johnson & Johnson MedTech (Biosense Webster) — Integration of PFA into mapping platforms exemplifies a high‑value bundling approach that raises switching costs in EP labs.
- AtriCure, AngioDynamics, IceCure, Francis Medical — These and other specialists play crucial roles in surgical AF, oncology (including irreversible electroporation and cryo), and urology/prostate thermal therapies, representing acquisition targets and strategic partners for larger medtechs seeking niche innovation.
- Stereotaxis — Robotic navigation approvals create a pathway for procedural standardization in complex arrhythmia cases — a capability that could reshape high‑mix centers of excellence.
- Platform and specialty players such as CONMED, Olympus, Stryker, Hologic, Terumo, Merit, Biotronik, Avanos, Kardium, and EDAP each anchor specific clinical workflows, from pain management and gynecology to HIFU‑based oncology — collectively expanding the competitive topology beyond EP-focused firms.
Key Strategic Implications for 2026 Decision‑Makers
Our market simulations and stakeholder interviews translate into practical priorities for different constituencies:
- Medtech executives: Accelerate investments in PFA and hybrid-energy platforms where clinical evidence suggests superior safety/efficacy tradeoffs; prioritize regulatory pathways and post‑market evidence generation to capture early-referral centers.
- Investors and M&A teams: Seek differentiated assets in niche ablation modalities (e.g., IRE, HIFU, water‑vapor transurethral systems, cryo for outpatient oncology) where the incumbent concentration is lower and upside from clinical validation is clearer.
- Hospital procurement and clinical leaders: Re‑evaluate capital allocation models in light of MS‑DRG and IPPS changes; focus on devices that demonstrably reduce procedure time, length of stay, or downstream admissions.
- Payers and HTA bodies: Use evidence‑based coverage with conditional reimbursement pathways (coverage with evidence development) to accelerate access while limiting upfront financial exposure.
- Startups and innovators: Design clinical programs that align timing of pivotal evidence with reimbursement windows; evaluate partnering with incumbents for scale and distribution rather than solo commercialization in highly consolidated subsegments.
Methodology & Credibility
PW Consulting’s Ablation Systems study synthesizes primary interviews with clinicians, procurement officers, and payers, triangulated against a proprietary device deployment database and regulatory/reimbursement trackers. The report uses a 2025 base year, covers historical trends from 2020–2025, and provides granular forecasting through 2032 (USD, millions). Our competitive scoring, scenario models, and go‑to‑market playbooks are calibrated with contemporaneous regulatory events and reimbursement code changes to ensure tactical relevance for 2026 planning cycles.
Conclusion — How to Use This Intelligence in 2026
For executives and investors, the central conclusion is straightforward: ablation is moving from modality proliferation to selective consolidation driven by evidence, regulatory timing, and payer economics. The winners in 2026 will be those that align product roadmaps with payer and hospital incentives, accelerate the collection of pragmatic evidence, and choose the right commercial partners or M&A targets. PW Consulting’s Ablation Systems Market Research report converts these pressures into executable options and quantified outcomes — enabling your team to make informed decisions in the coming budget and regulatory cycles.
To access the full dataset, granular segment and regional breakdowns, company revenue estimates, and the downloadable forecasting model, request PW Consulting’s complete Ablation Systems Market Research report through our client portal.
For detailed analysis of this topic, please visit the official page: Ablation Systems Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


