



PW Consulting: Oxindole Market Tops USD 85.5 Million in 2025, Poised for Continued Expansion

Oxindole Market Outlook 2026: Strategic Imperatives for Chemical, Pharma and Specialty Producers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of our Oxindole Market report — an evidence-based toolkit designed to influence executive decisions in 2026. This advisory distills market dynamics, competitive pressures and actionable plays derived from a structured analysis of historical performance (2020–2025) and a seven-year forecast (2026–2032). The objective: equip leadership teams with the context and strategic levers necessary to convert nascent demand signals into durable commercial advantage.
Oxindole Market
Executive snapshot — what the numbers tell us
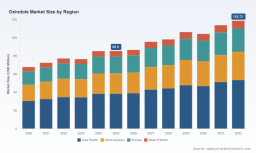
Oxindole has moved from a niche research chemical toward a more diversified specialty intermediate over the past half-decade. On a consolidated basis, the market expanded from USD 67.84 Million in 2020 to USD 85.5 Million in the base year 2025, reflecting both steady end-market adoption and periodic supply-side adjustments. Our forecast models — incorporating demand-side adoption curves, purity-driven pricing dynamics and capacity movements — project the market to grow to approximately USD 86.63 Million in 2026 and to USD 118.72 Million by 2032, reflecting a compound annual growth rate (CAGR) of roughly 4.81% through the forecast horizon.
Oxindole Market
Concentration metrics indicate a moderately consolidated vendor landscape: the top three players account for over 40% of market share while the top five approach six-tenths of the market. This structure enables scale players to influence pricing and quality standards, while leaving room for focused specialists and regional producers to capture pockets of value through niche differentiation.
Oxindole Market
Why this matters for 2026 strategic planning
-
Timing investments to the demand inflection: With the market projected to grow at ~4.8% CAGR, 2026 is a year for calibrated action rather than wholesale expansion. Companies should prioritize flexible capacity options — tolling agreements, modular reactors and contract manufacturing — over large greenfield investments unless they have secured long-term offtake or a clear technical differentiation (e.g., GMP capability, ultrahigh purity manufacturing).
-
Purity and specification as pricing levers: Purity segmentation and end-use requirements drive value far more than raw volume. Investing in analytical capabilities, validated supply chains for critical raw materials, and documented quality systems creates outsized returns when selling into pharmaceuticals or regulated intermediates. Conversely, commodity-oriented players should refine cost-to-serve and logistics to remain competitive in lower-purity streams.
-
Supply resilience and geographic strategy: The market’s supply base spans incumbent Western lab suppliers, Asian bulk producers and specialty European distributors. Buyers increasingly demand traceability, lead-time certainty and GMP-compliant documentation. For sellers, 2026 should be used to shore up dual-sourcing options and diversify manufacturing footprints to mitigate regional bottlenecks.
-
M&A and partnership playbook: Given the market concentration profile, targeted acquisitions (capability fills rather than broad scale plays), minority investments in innovation-stage producers, or strategic alliances around tolling and supply agreements can accelerate market entry or upgrade product mix without excessive capital outlay.
-
Regulatory and quality readiness: Pharmaceutical demand is a primary driver of high-purity and GMP-segment growth. Companies that proactively align facilities to pharma-grade quality systems, and that articulate clear product dossiers for regulatory audits, will command premiums and shorten qualification cycles in 2026.
Competitive landscape — players to watch
Our competitive mapping assessed global catalog suppliers, specialty distributors, and bulk manufacturers across capability, scale, channel reach and regulatory readiness. Core participants include major lab-supply houses and regionally strong manufacturers. The market dynamic is a continuum from research-scale catalog suppliers to GMP-capable bulk producers; each cluster pursues distinct commercial strategies.
-
MilliporeSigma (Sigma-Aldrich) — Burlington, MA: Positioned as a research-grade incumbent, Sigma-Aldrich supplies oxindole at research purities and benefits from integrated distribution channels into pharma R&D. Its strengths are brand trust, catalog breadth and rapid global logistics; its challenge is translating R&D relationships into higher-purity, regulated supply contracts without significant CAPEX.
-
TCI Chemicals — Tokyo, Japan: TCI has a reputation for high-quality reagents and tight analytical characterization. It competes effectively in discovery and materials science segments, where technical datasheets and lot-to-lot consistency are decision factors. Strategic moves to watch: pricing discipline on premium grades and potential expansion of bespoke synthesis services.
-
Thermo Fisher Scientific (Alfa Aesar) — Waltham, MA: Alfa Aesar combines global reach with a familiar catalog interface for researchers. Its advantage lies in penetrating academic and early-stage industrial R&D; the path to higher-margin, regulated supply is contingent on facility certification and strategic partnerships with licensed manufacturers.
-
Combi-Blocks — San Diego, CA & Apollo Scientific — Stockport, UK: These catalog and specialty distributors focus on gram-to-kilogram sales for medicinal chemistry and heterocycle synthesis. Their commercial edge is responsiveness and custom packaging; scale limitations constrain participation in larger industrial flows.
-
Oakwood Chemical — Estill, SC; Hairui Fine Chemicals & Capot Chemical — China: These manufacturers represent the bulk-production cohort. They are critical to industrial supply, offering larger lot sizes and competitive cost structures. The strategic differentiators for these players are GMP capability, supply chain transparency and the ability to rapidly shift capacity between grades.
Collectively, these players form a layered market: catalog suppliers dominate the R&D funnel, while regional producers and specialty manufacturers capture scale-driven industrial demand. For 2026, successful players will be those who manage channel transitions — converting catalog customers into qualified, higher-value purchasers when projects scale.
What the PW Consulting Oxindole report contains (operationally focused)
Our full report is structured to help commercial, technical and M&A teams act quickly and confidently. Highlights include:
-
Robust demand model: A bottom-up forecast through 2032, integrating end-market adoption curves, purity mix scenarios and elasticity assumptions to stress-test multiple growth narratives.
-
Supplier and capability atlas: A matrix mapping global suppliers by scale, geographies, regulatory posture (including GMP readiness), and typical lot sizes — enabling rapid partner selection and contingency planning.
-
Price and margin benchmarking: Scenario-based analysis showing margin sensitivity to purity, lot size and service level commitments — designed to inform commercial negotiations and product strategy.
-
Risk heatmap and mitigation playbooks: Concentration, raw-material exposure, regulatory and logistics risks quantified with prescriptive responses for procurement, operations and commercial leaders.
-
Go-to-market and commercialization templates: Channel strategies, sample SOPs for qualification, and account penetration plans to convert R&D customers into long-term buyers.
-
M&A screening and partnership playbooks: Criteria-driven target screening and integration checklists for capabilitiy-infill acquisitions and tolling partnerships.
Privacy by design: why this release withholds granular splits
In line with our “trailer” approach, this briefing surfaces the actionable strategic insights while intentionally withholding certain granular segmentation data (detailed regional shares, application-by-application percentages and some proprietary pricing points). Those segmented datapoints are central to competitive decision-making and are available in full through the report’s data appendices. The abbreviated public view is calibrated to inform executive strategy without disclosing the proprietary, transaction-critical inputs our clients rely on.
Practical next steps for executives in 2026
-
Immediate (0–3 months): Run a supplier stress-test using the report’s supplier atlas. Verify dual-source viability for critical projects and prioritize contracts with transparent quality documentation.
-
Near term (3–9 months): Pilot a quality upgrade program for at least one product family where higher purity unlocks access to pharmaceutical or regulated industrial demand. Use modular capacity options to avoid long lead-time capital exposure.
-
Medium term (9–24 months): Evaluate bolt-on acquisitions or strategic alliances that fill capability gaps — GMP certification, analytical lab expansion, or logistics hubs close to key demand centers.
-
Continuous: Monitor purity-driven margin profiles and adapt commercial contracts to include escalation and volume-based incentives that reflect the structural growth projected in our CAGR analysis.
Closing perspective
Oxindole’s evolution from a research chemical into a more strategically relevant intermediate creates a nuanced competitive landscape in 2026. The market’s steady growth trajectory through 2032 — underpinned by a ~4.81% CAGR — rewards companies that combine technical excellence with operational flexibility and targeted commercial execution. Scale matters, but so does specialization: premium returns will accrue to players who can certify quality, shorten qualification cycles and align channel economics to the buyer’s commercial life-cycle.
For executives preparing budgets, negotiating supply agreements, or evaluating M&A in 2026, our Oxindole Market report provides the quantitative foundation and the operational roadmaps to convert aspiration into measurable outcomes. To access the full dataset, granular segmentation, supplier scorecards and executable playbooks, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Oxindole Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


