



PW Consulting: Ready-to-Use Cell Culture Media Market to Grow from USD 2,420.21 Million in 2025 to USD 3,963.24 Million by 2032, Driven by a 7.3% CAGR

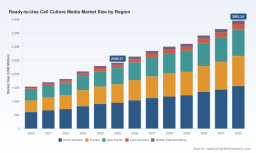
Ready To Use Cell Culture Media: Strategic Playbook for 2026 — A PW Consulting Market Brief
As the ready to use cell culture media market moves from recovery into sustained growth, 2026 represents a strategic inflection point for manufacturers, contract developers, and biopharma end-users. PW Consulting’s latest market research synthesizes five years of historical dynamics with a seven‑year forecast to equip executive teams with the operational and portfolio decisions that matter most over the next planning cycle.
Ready To Use Cell Culture Media Market
Market snapshot: momentum and scale
Our analysis uses 2025 as the base year and covers 2020–2025 historically with a forecast horizon of 2026–2032. The global market has expanded consistently across the historical window, and PW Consulting projects a compound annual growth rate (CAGR) of 7.3% for the forecast period. This trajectory reflects durable demand drivers — rising bioprocessing throughput, expansion of cell and gene therapies, and broader adoption of ready‑to‑use formats in research and diagnostics — that together convert episodic buying into structural growth.
Ready To Use Cell Culture Media Market
Key market architecture features that should inform 2026 decision‑making include a moderate level of supplier concentration (our market concentration metrics indicate that the top three firms control roughly half the market while the top five approach seven‑tenths), and an evolving product mix that increasingly privileges chemically defined, serum‑ and animal‑component‑free formulations. These structural characteristics create both opportunity and competitive pressure for firms across the value chain.
Ready To Use Cell Culture Media Market
Why this matters for 2026 strategy
Executives planning budgets and product road maps for 2026 need to move beyond aggregate growth expectations and translate them into tactical choices across R&D, manufacturing, commercial models, and supply chain resilience. The PW Consulting report is purpose-built to convert market projections into executable options — but at a high level the implications are clear:
- Portfolio prioritization: As end-users shift toward reproducibility and regulatory confidence, prioritize investments in chemically defined and serum‑free products that address contamination and variability risk.
- Regulatory and quality positioning: Firms with certified GMP production and recognized quality accreditations are increasingly preferred as partners for therapeutic development; securing such credentials now will shorten commercial sales cycles in 2026.
- Channel and commercial model innovation: Ready to use formats are adopted across both research and manufacturing workflows; firms should differentiate with value‑added services (application support, kit solutions, bundled cell+media offerings) rather than competing on price alone.
- Supply chain design: Cold‑chain and temperature‑controlled logistics remain a critical cost and risk vector. Investing in logistic partnerships, room‑stable formulations where feasible, and multi‑sourcing strategies will be table stakes for 2026.
What the PW Consulting report delivers (practical, ready‑to‑use content)
Our report is intended as a working tool for strategy teams. It combines proprietary market sizing and forecast models with scenario analysis and commercial playbooks designed for immediate application. Key deliverables include:
- Strategic dashboards mapping market size, growth vectors, and concentration metrics through 2032, enabling rapid slicing for budgeting and M&A screening.
- A decision matrix linking product attributes (e.g., chemically defined, serum‑free, room‑stable) to buyer personas across research, diagnostics, bioprocessing, and cell therapy production.
- Supply chain heatmaps and a cold‑chain cost model that quantify the operational impact of temperature‑sensitive logistics on margins and service levels.
- Regulatory readiness checklist and supplier due diligence templates tailored to FDA/EMA expectations for media used in therapeutic workflows.
- Commercial playbooks with sample pricing strategies, channel segmentation, and partnered go‑to‑market approaches for accelerating uptake of new media formats or kit solutions.
To respect competitive confidentiality and preserve commercial leverage for report subscribers, segmented numerical tables and granular regional/application breakdowns are available exclusively in the full report and accompanying data workbook.
Competitive landscape: who shapes buying decisions
The ready to use media market features an established set of global suppliers together with focused specialists that serve niche technical needs. Several strategic archetypes are apparent:
- Integrated life‑science platforms that bundle media with instruments, services, and reagents. These players leverage broad sales channels and brand trust to capture large accounts seeking simplified procurement.
- Specialist media formulators that compete on technical performance and customization, often serving high‑value cell therapy and viral vector programs requiring tailored, GMP‑grade inputs.
- Regional and application specialists that excel in primary cell and stem cell workflows by offering optimized, ready‑to‑use kits and localized technical support.
Representative firms illustrate these archetypes. Several multinational life‑science companies combine wide portfolios of classical and high‑performance media with global manufacturing and distribution footprints, enabling scale and reliability for large bioprocessing accounts. Other firms are notable for their focus on chemically defined, non‑animal origin media tailored to cell and gene therapy production or stem cell research, and for recent moves to extend GMP and custom‑service capabilities.
Recent industry events underscore strategic shifts. A leading global life‑science company achieved a notable industry cGMP certification specifically for cell culture media production at multiple sites — a credential that materially elevates its suitability as a supplier for regulated therapeutic programs. Additionally, a specialist primary‑cell supplier has launched bundled cell+media kits and expanded into GMP custom media services, signaling intensified competition at the premium, application‑specific end of the market. These developments reinforce the message: certification and solutionization are becoming differentiators that shorten procurement cycles and expand addressable use cases.
Risks, disruptors and opportunity pockets
Three structural risks and three opportunity vectors deserve focused attention from leadership teams:
- Risks
- Raw material volatility: Ingredient supply shocks and pricing dynamics can rapidly compress margins for players without hedging or diversified sourcing.
- Cold‑chain fragility: Failure to control temperature‑sensitive distribution not only harms product quality but creates reputational and contractual liabilities.
- Regulatory escalation: As regulators converge on stricter quality expectations for therapeutic inputs, firms without robust GMP capabilities face narrowing addressable markets.
- Opportunities
- Value‑added kits and integrated solutions: Bundling cells, media and protocolized kits improves reproducibility for customers and creates sticky revenue streams.
- Custom GMP services for cell therapy: Contract development and manufacturing services for tailored media represent a high‑margin adjacency for technically competent firms.
- Room‑stable and benchmarked formulations: R&D investment in room‑stable and high‑performance media can reduce logistics costs for customers and unlock new distribution channels.
Executive actions for 2026 — a tactical checklist
Based on our scenario testing and interviews across the value chain, PW Consulting recommends the following near‑term actions for decision‑makers planning for 2026:
- Fast‑track certification where warranted: If targeting therapeutic customers, prioritize GMP and third‑party certifications to eliminate procurement blockers.
- Refine product segmentation: Reallocate R&D budgets toward chemically defined and serum‑free variants that align to high‑growth applications while maintaining a cost‑competitive classical media line for legacy customers.
- Invest in logistics partnerships: Negotiate dedicated cold‑chain corridors and contingency stock to reduce lead times and service failures.
- Build bundled offerings: Pilot cell+media kits in targeted research segments to validate pricing elasticity and reduce churn.
- Pursue selective M&A or alliances: Use market concentration and customer win‑rate analytics to prioritize tuck‑ins that add GMP capacity, technical depth, or channel breadth.
- Operationalize margin resilience: Implement ingredient hedging and SKU rationalization to protect gross margins against commodity swings.
Conclusion — why the full report matters
2026 will favor firms that convert macro growth into disciplined, executional advantage: demonstrable quality credentials, supply‑chain robustness, and customer‑centric productization. PW Consulting’s Ready To Use Cell Culture Media Market report provides the granular data models, supplier scorecards, cost‑to‑serve analytics, and validated go‑to‑market playbooks that strategy teams need to move from intent to impact.
For executives who require the complete datasets, regional and application breakdowns, and downloadable scenario tools, the full report and interactive workbook are available via PW Consulting’s market research portal. The condensed insight presented here is intended to guide initial priorities — the full intelligence package unlocks the operational details necessary to finalize budgets and M&A screens in 2026.
PW Consulting remains available for tailored strategy workshops, acquisition diligence, and implementation roadmaps built from the report’s models. Contact our Life Sciences practice to convert the market’s momentum into measurable commercial outcomes.
For detailed analysis of this topic, please visit the official page: Ready To Use Cell Culture Media Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


