



PW Consulting: Wafer Front Opening Unified Pod (FOUP) Market to Reach USD 2,228.67 Million by 2032 on 8.19% CAGR

Wafer Front Opening Unified Pod (FOUP) Market: A Tactical Preview for 2026 Decision-Makers
PW Consulting’s latest market intelligence on Wafer Front Opening Unified Pods (FOUPs) delivers a focused, actionable briefing designed for executives, procurement leads, and technology strategists preparing for 2026. Built on a 2020–2025 historical baseline and a 2026–2032 forecast horizon, the report synthesizes macro trajectories, technology-driven demand shifts, supplier positioning, and supply-chain sensitivities into a compact decision toolkit. This preview outlines the strategic value of the full report, highlights priority actions for 2026, and explains why operators and equipment partners should re-evaluate sourcing, product roadmaps, and deployment timing now—while reserving the granular segment tables and proprietary forecasts for the full downloadable report.
Wafer Front Opening Unified Podfoup Market
Why this matters for 2026
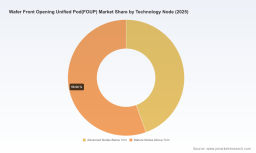
The global FOUP market has transitioned from a niche capital-equipment adjacency to a strategic enabler of wafer fab performance. Our analysis shows the market accelerating from a 2025 base of approximately USD 1,284.5 million and tracking toward a sustained expansion underpinned by a compound annual growth rate (CAGR) of 8.19% across the 2026–2032 forecast window. By 2032 the market trajectory outlined in our models points to a materially larger addressable market, reflecting rising fab automation, the proliferation of advanced-node manufacturing, and evolving requirements for wafer handling that support new substrates and 3D architectures.
Wafer Front Opening Unified Podfoup Market
Top-line takeaways (strategic trailer)
- Adoption inflection: Automated material handling system (AMHS) rollouts and next-generation process flows are the primary demand vectors—planning cycles should prioritize FOUP compatibility early in tool qualification.
- Design evolution: Thinner, warped, and 3D-stacked wafers are driving iterative FOUP design requirements (microenvironment control, non-standard slot accommodation, purge capability).
- Supplier concentration: The sector is consolidated—our concentration analysis shows a high level of market share captured by a small number of global suppliers, creating both supplier- negotiation leverage and single-supplier risk depending on procurement strategy.
- Cost and input risk: Polycarbonate and other polymer feedstock price differentials across regions are producing localized cost pressure and should be monitored as part of total cost of ownership assessments.
What the full PW Consulting report contains (practical, executable content)
The full report is structured to enable immediate operational and strategic action. Core deliverables include:
Wafer Front Opening Unified Podfoup Market
- Market model (2020–2032) with base-year reconciliation and scenario sensitivity to lead times, AMHS adoption rates, and advanced-node wafer penetration.
- Procurement playbook: supplier selection criteria, contract structures, and TCO templates that incorporate lifecycle cleaning, contamination risk, and retrofit compatibility.
- Technology requirements mapping: FOUP features by wafer type (including purge options, EUV readiness, and mechanical allowances for warped/thinned substrates) and a checklist for tool-and-load-port integration.
- Risk register: raw-material exposure (regional polycarbonate price dynamics), regulatory/SEMI compliance requirements, and mitigation strategies for single-source dependencies.
- Competitive benchmarking with vendor capability matrices and recommended partnership archetypes for foundries, IDM, and OSATs.
Market dynamics and drivers
Three structural dynamics are shaping FOUP demand in 2026 and beyond. First, automation: fabs moving to fully integrated AMHS require carriers that provide consistent mechanical interfaces, predictable handling characteristics, and reliable microenvironment management—forcing a replacement or retrofit cadence for carriers that predate modern AMHS specifications. Second, substrate complexity: the rise of 3D-stacked, thinned, and non-standard substrates increases sensitivity to vibrational, thermal, and particulate disturbances during transit. Third, standards and regulatory compliance: FOUPs must meet a broad set of SEMI standards governing dimensional accuracy, automation interfaces, and cleanroom compatibility—these constraints materially affect supplier selection and validation timelines.
Operationally, raw-material volatility is non-trivial. For example, polycarbonate pricing exhibited regional divergence in early 2026—northeast Asia experienced a price easing while Europe saw upward pressure tied to industrial demand. These movements translate into procurement windows and hedging opportunities for large-volume buyers and can shift landed costs across supplier geographies.
Competitive landscape — capabilities that matter
The FOUP vendor ecosystem is a mix of global suppliers, regional manufacturers, and specialists focused on value-add features. The sector’s concentration underscores the influence of a handful of leaders on design norms and industry direction. Our competitive review highlights the following supplier capabilities that will determine partner selection in 2026:
- Microenvironment mastery and advanced isolation: Vendors offering superior internal atmosphere control and wafer isolation for thin/warped wafers reduce process risk for advanced-node manufacturing. Example: Entegris (United States) has positioned products that emphasize microenvironment control and automation compatibility.
- Precision materials and molding: Suppliers with deep expertise in precision molding and polymer formulation deliver long-term dimensional stability and contamination control—tenets for high-throughput fabs. Shin-Etsu Polymer (Japan) and Miraial (Japan) exemplify strengths here.
- AMHS and interface readiness: Modular EFEM/load-port compatibility and SEMI/FIMS compliance shorten integration cycles; ePAK (United States) and several Taiwanese suppliers emphasize modular, automation-ready carriers.
- Feature differentiation: Purge-capable FOUPs, diffuser designs, and EUV-ready pods represent product lines that command premium placement in fab BOMs. Regional exhibitors and product catalog refreshes throughout 2025 signaled a rapid commercialization cadence for these features.
Recent industry moves that validate these competitive vectors include trade-show unveilings of diffuser FOUPs and product catalog releases emphasizing purge and AMHS compatibility. Such developments make it clear that vendors are racing to align product roadmaps with advanced node and automation demands.
Implications for procurement, R&D, and operations in 2026
- Procurement: Reassess supplier scorecards to weight microenvironment performance, SEMI-standard interoperability, and life-cycle cleaning cost—not just unit price. Consider dual-sourcing strategies for mission-critical lines to mitigate concentration risk.
- R&D and product planning: If your roadmap includes thinned or 3D-stacked wafers, accelerate FOUP co-development discussions. Early engagement shortens qualification cycles and reduces rework during ramp phases.
- Fab operations: Update equipment qualification scripts to include purge testing, warped-wafer handling, and AMHS interface stress tests. Expect validation windows to expand unless carriers are specified and ordered well in advance.
- Supply-chain strategy: Factor regional polycarbonate pricing and lead-time variability into make-vs-buy analyses. For high-volume fabs, forward-buying or strategic inventory buffers may prove economical during transient price swings.
Where PW Consulting adds execution value
Our methodology couples bottom-up equipment and process adoption modeling with supplier capability scoring and real-world validation from product releases and trade-show activity. Clients receive a decision-ready template: negotiation levers keyed to supplier concentration metrics, a supplier short-list aligned to product and fab archetypes, and a phased procurement timeline tied to tool install schedules and qualification windows.
We also provide scenario runs that show how modest changes to AMHS rollout rates, purge adoption, or advanced-node mix can materially alter carrier demand and inventory burn rates. These scenarios are particularly useful for capital planners and purchasing teams aiming to align CAPEX schedules to validated carrier deliveries without creating excess inventory.
How to use the full report
Consider the preview above a strategic trailer: it surfaces the macro thesis, supplier dynamics, and the practical actions that matter in 2026. The full PW Consulting Wafer FOUP report contains the proprietary segment-level forecasts, region-and-application breakdowns, and downloadable TCO models that operational teams will need to implement these recommendations. To preserve competitive advantage and ensure actionable integrity, we reserve detailed tables, unit forecasts by carrier type, and supplier share estimates for the full report package.
If you are responsible for fab readiness, procurement, or carrier product strategy, the report will reduce uncertainty ahead of RFP cycles, support negotiation with high-concentration suppliers, and align technical qualification sequences with tool roadmap milestones.
Next steps
- Download the full report for the complete data tables, supplier scorecards, and the procurement playbook needed to enact the 2026 actions outlined above.
- Request a tailored briefing if your organization operates unique substrate types (e.g., thinned, warped, or 3D-stacked wafers) or if you are planning a major AMHS deployment in the 2026–2027 window.
PW Consulting’s FOUP market analysis is designed to convert market intelligence into measurable actions. Use the insight in this preview to prioritize supplier dialogue, adjust procurement timing, and de-risk your 2026 fabs—then consult the full report to execute with the granular forecasts and supplier metrics that will guide contract-level decisions.
For detailed analysis of this topic, please visit the official page: Wafer Front Opening Unified Podfoup Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


