



PW Consulting Market Insight: Renewable Energy Consultancy Poised to Reach USD 34,575.08 Million by 2032

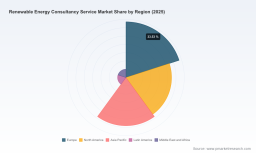
PW Consulting: Renewable Energy Consultancy Services — Strategic Market Research Preview (2026 Outlook)
Executive summary
As governments, utilities, corporates and investors enter a pivotal phase of decarbonisation planning, PW Consulting today publishes a market research preview that frames the decision-making landscape for renewable energy consultancy services in 2026. Our analysis shows a market that has expanded materially since 2020 and is set to continue growing at a double‑digit compound annual growth rate of 10.41% across the 2026–2032 forecast window. From an aggregate base of roughly USD 17.3 billion in 2025, we project the total consultancy market to approach the mid‑tens of billions by the early 2030s, reflecting sustained demand for technical due diligence, grid integration, transaction advisory, and cross‑disciplinary implementation support.
Renewable Energy Consultancy Service Market Research
This briefing is written as a strategic “trailer”: it surfaces the analytical frameworks, material trends and actionable recommendations that will determine which organisations win in 2026, while deliberately reserving the granular segmentation tables and proprietary datasets for subscribers to the full report.
Renewable Energy Consultancy Service Market Research
What the full report delivers — practical, transaction‑ready content
- Market sizing and validated growth scenarios: high‑resolution forecasts, sensitivity testing under alternative policy and supply‑chain stress cases, and topline demand drivers to guide 12–36 month plans.
- Decision frameworks for compliance and tax‑credit risk: playbooks that translate new rules (including FEOC-style foreign entity considerations and recent tax credit adjustments) into operational checklists and safe‑harbor strategies for project sponsors and advisers.
- Due diligence and commercial templates: lender and investor checklists, technical DD scopes, model assumptions for hybrid (solar+storage) and merchant structures, and procurement term sheets shaped for hyperscaler and corporate off‑takers.
- Go‑to‑market and M&A playbooks: integration roadmaps for capability acquisitions, value capture models for platform deals, and playbooks for entering verticals such as green hydrogen and long‑duration storage.
- Operational tools for delivery: staffing and cost‑model matrices that reflect the growing premium for specialised labour (grid engineers, permitting specialists, storage integration experts), plus vendor selection frameworks for digital tools (AI, IoT, trading platforms).
- Case studies and applied scenarios: anonymised engagements that demonstrate how consultancies are structuring financing, grid‑connection solutions and offtake arrangements under real market constraints.
Key dynamics shaping advisory demand in 2026
- Regulatory complexity and compliance as a growth vector — New supply‑chain and foreign‑entity rules enacted for projects commencing construction in 2026 materially increase the need for compliance advisory, contract re‑drafting and safe‑harbor solutions. Consultancies that pair policy expertise with transaction execution will capture disproportionate value.
- Policy reversals and tax‑credit volatility — Recent legislative changes have forced sponsors to reprioritise pipelines and re‑assess deal economics. Advisory services that can stress‑test portfolios and optimise for shifting incentive stacks will be in demand.
- Hyperscaler procurement and hybrid projects — The surge in procurement by large cloud and data‑centre operators has driven complex PPA structures and hybrid integration needs. Expertise in bespoke procurement, route‑to‑market and balancing services will be commercially rewarded.
- Consolidation in capability, not concentration of market share — While the market remains fragmented (with the top providers accounting for a minority share of overall revenues), the pace of capability acquisitions is rising as firms seek to secure technical niches — grid‑connection engineering, ecological permitting, and storage integration being prominent examples.
- Human capital and delivery cost pressure — Specialist labour is a primary operational cost driver. Firms must choose between building in‑house capacity, strategic alliances, or bolt‑on acquisitions to scale delivery without eroding margins.
Strategic implications for corporate and investor decision‑makers in 2026
For executives and investment committees, the report crystallises four immediate strategic moves that should be on every 2026 agenda:
Renewable Energy Consultancy Service Market Research
- Re‑baseline portfolios under regulatory stress cases — Conduct rapid portfolio triage using short‑horizon scenario models to identify at‑risk projects and reallocate capital toward resilient, high‑probability pipelines.
- Prioritise supply‑chain compliance and tax‑credit remediation — Implement an audit and remediation program now to preserve eligibility for incentives and to de‑risk financing events later in 2026–2027.
- Lock early partnerships for grid‑connection and permitting capacity — Given lead times for interconnection and environmental approvals, secure delivery partners or acquisitions that add technical engineering and permitting throughput.
- Design customer‑centric commercial offers for hyperscalers and corporates — Build modular offtake and hybrid product structures (time‑of‑delivery guarantees, capacity‑firming services) tailored to large buyers with sustainability procurement mandates.
Competitive landscape — who is shaping advisory choices
The advisory market is architected by a mix of global strategy houses, large professional services firms, specialist technical consultancies and market‑intelligence providers. Our analysis synthesises strengths across firms that clients repeatedly shortlist:
- Top strategy houses (e.g., global management consultancies) excel at net‑zero planning, portfolio optimisation and scenario modelling — they are frequently engaged for high‑level transition roadmaps and cross‑asset allocation decisions.
- Large professional services and technology integrators bring transaction experience, regulatory advisory and digital enablement — supporting complex PPA platforms, emissions reporting and end‑to‑end transformation programs.
- Specialist engineering and technical consultancies provide the heavy lifting on grid‑connection engineering, technical due diligence, and construction‑phase assurance critical to de‑risking financed projects.
- Market intelligence and forecasting firms supply the data‑driven inputs that underpin valuation, merchant risk modelling and long‑term price curves for power, capacity and hydrogen.
Recent capability plays illustrate the market’s dynamic character: several established consultancies completed acquisitions or announced strategic integrations in late 2025 and early 2026 to bolster offerings in grid‑engineering, ecological consulting and power & energy execution. These moves accelerate time‑to‑market for complex renewables programmes and raise the bar on what buyers expect from advisory partners.
Despite these transactions, concentration metrics show the market remains fragmented — the top three firms account for a modest portion of market revenue and the top five less than a third — creating substantial room for specialist and regional players to scale through targeted capability bets or platform M&A.
How PW Consulting’s methodology supports timely 2026 decisions
Our proprietary approach blends bottom‑up project databases, client engagement debriefs, and policy‑scenario overlays to produce forecasts and decision tools that are directly implementable by corporates, sponsors and advisers. Key methodological pillars include:
- Triangulated forecasting: combining historical project pipelines, recent procurement flows (including hyperscaler activity), and policy scenario stress tests to produce both baseline and adverse case pathways.
- Actionable templates: deliverables are designed for immediate use — due diligence scopes that map to lender requirements, procurement term sheets, and implementation checklists for interconnection processes.
- Capability gap matrices: diagnostic tools that quantify internal vs. external sourcing needs across technical, regulatory and commercial functions, tied to hiring vs. M&A decision frameworks.
- Validated benchmarks: time‑to‑permit, expected engineering lead times and typical cost bands for specialist services are provided as operational planning inputs (note: granular regional and application splits are reserved for the full report).
Recommended next steps for market participants
- For sponsors and asset owners: run an immediate compliance audit and re‑price your development pipeline under the report’s policy stress scenarios.
- For utilities and grids: prioritise investments in interconnection engineering capacity and flexibility market participation playbooks; partner with engineering consultancies that demonstrate on‑the‑ground delivery across permitting and grid codes.
- For consultancies and service providers: accelerate capability acquisitions or partnerships in niche technical areas (grid‑connection, ecological permitting, hydrogen engineering) and invest in digital delivery platforms to protect margin.
- For investors and lenders: incorporate service delivery risk and specialist labour scarcity into financing covenants and pricing; use our due diligence templates to standardise lender review processes.
Accessing the full intelligence
This strategic preview is an extract designed to clarify the near‑term decision architecture for 2026. The full Renewable Energy Consultancy Service Market Research report from PW Consulting contains detailed segmentation, proprietary datasets, regional and application breakdowns, client‑ready templates, and subscription access to our interactive scenario modelling tool. To obtain the full report and supporting materials, please visit the PW Consulting reports page or contact your PW Consulting account lead.
In a market that is growing at a sustained double‑digit pace and where regulatory change and hyperscaler demand are re‑shaping deal economics, the right advisory choices made in 2026 will materially alter portfolio outcomes for the rest of the decade. PW Consulting’s research is built to make those choices clearer, faster and more defensible.
For detailed analysis of this topic, please visit the official page: Renewable Energy Consultancy Service Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


