



PW Consulting: Double Fed Wind Turbine Market to grow at 5.25% CAGR — from USD 18,450 Million in 2025 to USD 26,396.79 Million by 2032

Double Fed Wind Turbine Market — Strategic Briefing for 2026 Decision Makers
Executive summary
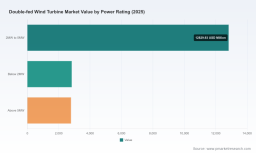
PW Consulting’s latest market study on the Double Fed Wind Turbine market distills five years of historical performance and a seven-year forecast into a decision-grade playbook for 2026. The global market, measured on a USD Million revenue basis, reached an estimated USD 18,450 Million in our base year (2025) and is modeled to grow at a compound annual growth rate (CAGR) of 5.25% through our forecast horizon (2026–2032). By 2032 the model shows the market approaching the mid-twenty thousands in USD Million, driven by steady onshore additions, repowering programs in mature markets, and continued technology optimization of Type III DFIG platforms.
Double Fed Wind Turbine Market
Why this report matters for 2026 corporate strategy
2026 will be a crossroads year for turbine OEMs, component suppliers, IPPs, and grid operators. Several converging trends—tighter grid codes, step-changes in rare-earth pricing, and a wave of repowering initiatives in Europe and parts of Asia—mean organizations that rely on legacy assumptions about cost, performance and market share risk strategic missteps. PW Consulting’s report is designed as an operational strategy tool: it translates macro projections into mid-term portfolio decisions, procurement roadmaps, capex prioritization and M&A screening criteria that are executable in calendar-year 2026.
Double Fed Wind Turbine Market
Market outlook — what the top-line numbers reveal
-
Trajectory: After a period of recovery and adjustment across 2020–2025, the double fed turbine market is on a stable growth path into the late 2020s, reflected in a 5.25% CAGR for the 2026–2032 forecast window.
Double Fed Wind Turbine Market -
Scale: The 2025 market level provides a meaningful base for scenario testing—our layered forecasts show how variations in repowering intensity, commodity price shocks and regulatory tightening can move the 2032 outcome by several percentage points, underlining the importance of adaptive investment planning.
-
Concentration: Market concentration is moderate—our CR3 and CR5 indicators show that while a few OEMs hold a strong foothold, there remains room for strategic entry, partnerships and regional champions to capture value.
Technology and supply‑chain dynamics shaping 2026 choices
Double-fed induction generator (DFIG) platforms remain a core technology for onshore wind and for many repowering programs because of their proven maturity, partial converter architecture and cost profile versus full-converter permanent-magnet solutions. But that calculus is rapidly evolving under three practical pressures:
-
Grid-code complexity: New requirements for voltage control, frequency regulation and fault ride-through are increasing the demands on DFIG systems. We document how incremental investments in power electronics and controls are now prerequisites for large-scale interconnection in many markets.
-
Commodity volatility: Rare-earth dynamics—particularly upward pressure on neodymium—are changing generator cost comparisons. While DFIG architectures typically use less rare-earth material than permanent-magnet generators, suppliers and buyers must re-run component-level cost models to avoid margin surprises in procurement contracts signed in 2026.
-
Functional evolution: Research and demonstration projects (including recent demonstrations of Type III DFIGs operating in grid-forming modes) show that DFIG technology can be adapted to meet higher-stability grid roles. The report assesses the operational and certification pathways OEMs and operators should pursue to convert this capability into commercial value.
Competitive landscape — practical implications for OEMs and buyers
Our competitive analysis synthesizes OEM strategies, technology footprints and route-to-market plays for leading participants. Key findings:
-
Global incumbents with diversified portfolios and local manufacturing bases maintain advantages in repowering and large onshore deployments. Their scale enables multi-market warranty programs and financing support that matter to big IPPs.
-
China-based OEMs continue to press both domestically and internationally with a combination of cost competitiveness and rapid product cadence. Their presence is particularly relevant to buyers evaluating total cost of ownership and delivery timelines for 2026 deployables.
-
Specialist mid‑tier vendors retain strategic opportunities by focusing on niche value propositions—serviceability, local content partnerships, or tailored drivetrain optimizations for specific wind regimes.
Profiles in the full study include detailed capability matrices and go‑to‑market analysis for the industry’s most consequential players—ranging from long-established European and American manufacturers to leading Chinese OEMs—plus tactical recommendations for sourcing and partnership negotiations.
Repowering, project execution and near-term revenue pools
Repowering is one of the most actionable near-term opportunities for DFIG technology, especially in markets with high early deployment density. Recent European repowering programs that replace older units with higher-capacity DFIG-based turbines have demonstrated attractive output uplift per site. The April 2026 milestone at a major offshore project underscores that DFIG configurations retain relevance in the repowering mix and in hybrid project designs where cost and grid support services must be balanced.
For project developers and asset owners, the report provides a replication-ready checklist that converts high-level repowering potential into site-level execution plans, including capex/opex modeling, permitting timelines, and retrofit risk matrices.
What the report contains — operational, not academic
-
Bottom‑up market sizing and a 2026–2032 scenario suite calibrated to multiple repowering, commodity and regulatory pathways.
-
Technology assessment comparing DFIG variants against alternative drivetrains across lifecycle cost, serviceability, and grid-compliance vectors.
-
Supply‑chain heatmap and supplier risk scoring that highlights single‑source dependencies and mitigation strategies for critical subsystems.
-
Competitive benchmarking and commercial playbooks—negotiation templates, warranty structuring guidance, and choice architecture for buy vs. partner decisions.
-
Regional go‑to‑market implications and an actionable repowering toolkit that translates model outputs into project-level KPIs and IRR sensitivities for 2026 investment approvals.
-
M&A and JV screening models with target profiles and integration checklists for acquirers seeking scale or vertical capabilities.
Strategic recommendations for 2026 (executive checklist)
-
Re-run procurement models with 2026 commodity assumptions. Even modest shifts in rare-earth pricing materially change the cost-benefit analysis between DFIG and full-converter layouts.
-
Prioritize grid-compliance upgrades in product roadmaps. Certification-ready power-electronics suites and validated fault‑ride‑through strategies will be entry tickets in several key markets.
-
Make repowering a core business unit focus. The near-term revenue pool from repowering is underpriced in many strategic plans—early movers who can streamline logistics and retrofit engineering will capture outsized margins.
-
Design flexible commercial frameworks. Offerings that combine supply, extended service, and performance guarantees reduce offtaker procurement friction and create recurring revenue streams.
-
Use data‑driven M&A screening. Target assets that plug immediate supply-chain gaps or bring validated grid‑stability solutions, rather than diversifying purely by geography.
How to use this research in 2026 planning cycles
PW Consulting’s study is built for integration into annual planning and three‑year tactical roadmaps. We provide templates to translate market scenarios into budget impacts, procurement timing, and supplier engagement calendars. For executive teams, the most immediate value is in risk-reduction: the report supplies market-calibrated sensitivities that let CFOs and Heads of Projects quantify downside exposure and buffer margins with targeted hedges or contractual clauses.
Next steps — where to find the full intelligence
This briefing has highlighted the strategic contours and operational implications of the Double Fed Wind Turbine market as you set priorities for 2026. PW Consulting’s full report contains the granular models, supplier scorecards and downloadable financial templates that senior teams need to move from insight to execution. To obtain the complete dataset, interactive forecast files and bespoke advisory support for 2026 decision-making, please access the full study through the PW Consulting portal.
For detailed analysis of this topic, please visit the official page: Double Fed Wind Turbine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


