



PW Consulting Report: Used Golf Cart Market Poised for 6.25% CAGR Through 2032

Used Golf Cart Market — 2026 Strategic Brief: What Corporate Leaders Must Know
Executive snapshot
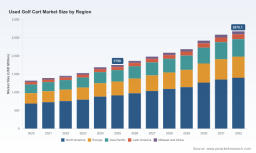
PW Consulting's latest Used Golf Cart Market study (base year 2025) delivers a focused, decision-ready view of a market that has moved from niche afterthought to strategic asset for OEMs, dealers, fleet operators and private equity players. Our analysis shows the global used golf cart market reached approximately USD 1,750.0 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 6.25% through our forecast window (2026–2032), reaching an estimated USD 2,675.1 Million by 2032. That trajectory builds on steady historical expansion from about USD 1,320.5 Million in 2020 to the 2025 base, reflecting accelerating electrification, dealer program sophistication and demand diversification beyond traditional golf-course buyers.
Used Golf Cart Market
Why this report matters for 2026 corporate decisions
- Industry inflection around battery technology. Lithium-ion adoption is moving from optional feature to de facto standard in many segments of the secondary market, driven by year-on-year battery system cost declines (roughly 5–10% annually in recent industry assessments). The practical effect for used-vehicle economics is twofold: higher residual values for lithium-equipped units and new refurbishment pathways centered on battery remanufacture and certified exchange.
- Regulatory and logistics constraints are material. Safety and compliance developments—UL 2271 for lithium cells and tighter European battery regulations (CE marking and mandatory Battery Management Systems)—are not academic: they materially affect refurbishment scope, cross-border trade and certified pre-owned (CPO) program design. Shipping constraints introduced at the start of 2026 (air transport state-of-charge limits for larger packs) change the cost and timing assumptions for national and international distribution of refurbished packs.
- Market structure supports both focused consolidation and local specialization. The market concentration is meaningful but far from monopolistic: the three-largest players account for a meaningful share of sales while the five-largest expand that footprint further, leaving space for regional champions, fleet specialists and value-focused entrants. That structure favors a dual approach—strategic M&A to secure scale where needed, and targeted organic investment to build differentiation in service, software or local fulfillment.
- Near-term economics favor vertically integrated refurbishers. Falling lithium costs (48V full sets roughly in the USD 1,000–1,600 range as of early 2026) make in-house battery refurbishment or certified supply arrangements commercially compelling. For operators managing fleet turn-ins, unlocking margin in battery lifecycle management becomes a core source of competitive advantage.
What’s inside the PW Consulting report (operationally focused)
The report is intentionally practical for 2026 decision cycles. Highlights include:
Used Golf Cart Market
- Top-down market sizing and scenario-driven forecasts through 2032 (baseline, upside and downside paths) that stress-test volume, price and replacement cycles under alternate electrification scenarios.
- Competitive benchmarking across OEMs, fleet refurbishers and dealer networks, including program archetypes for Certified Pre-Owned (CPO), warranties, refurbishment tiers and digital resale platforms.
- Modular playbooks for CPO program design that cover inspection checkpoints, battery certification, warranty stratification, pricing ladders and marketing positioning.
- Battery economics pack: total cost of ownership (TCO) models by powertrain, lifecycle calculators for battery reuse/refresh, and decision trees for remanufacture vs. replacement.
- Regulatory and logistics compliance checklist that operational teams can use to align refurbishment, sales and export processes with UL and EU battery rules and post-2026 air-transport constraints.
- Actionable M&A screening (target profiles by capability) and a prioritized list of integration value levers for buyers seeking rapid scale in used inventory or refurbishment capacity.
- Case studies and playbooks derived from leading market participants, plus a dataroom of anonymized transaction economics for benchmarking.
Competitive dynamics — what the leading firms are signaling
Observing OEM and aftermarket moves through 2025–early 2026 reveals three durable strategic plays:
Used Golf Cart Market
- OEM-led certified pre-owned as a brand-defense and revenue extension. Incumbent OEMs with broad dealer networks are formalizing multi-tier CPO programs—refurbishment with standardized new components, battery options (including lithium), and staged warranty packages—to capture resale margin and preserve brand equity as vehicles age. Recent model updates and CPO program refreshes showcase how OEMs are turning certified used units into an extension of their product roadmap.
- Electrification-first challengers building volume into the secondary market. New and rapidly scaling electric manufacturers are generating high flows of pre-owned inventory; their product design and modular battery architectures make refurbishment and certified resale more straightforward, expanding options for value buyers in residential and neighborhood electric vehicle segments.
- Fleet and utility orientation drives separate economics. Utility and commercial-use carts (including those sold under utility-focused brands) create different refurbishment cycles and TCO priorities compared to personal/residential use. Firms with strong fleet refurbishment processes and logistic capabilities can extract higher repeatable margins.
Strategically, the recent product and program moves from leading vendors illustrate these points: enhanced CPO offerings with lithium options and theatrical seating models; model-year refreshes integrated into refurbishment pipelines; and introduction of street-legal LSV variants that expand resale channels. These initiatives are reshaping inventory profiles, warranty exposure and aftermarket services in real time.
2026 strategic playbook — recommended priorities
- Design a certified program now, not later. Whether you are an OEM, dealer group or independent refurbisher, a transparent, tiered CPO program that aligns refurbishment standards to warranty pricing will be the baseline expectation for buyers in 2026.
- Invest in battery lifecycle capability. Build or partner for BMS-enabled diagnostics, UL 2271/CE compliance workflows, and remanufacturing cells/packs to capture margin and reduce exposure to pack replacement costs.
- Embed regulatory and logistics compliance into operating models. Integrate EU battery tracking and air-transport state-of-charge constraints into sales, distribution and aftermarket processes to avoid costly retrofits and delayed shipments.
- Use telematics as resale currency. Collect and standardize vehicle health data to reduce asymmetry in the used-market and to command price premiums on certified units.
- Segment go-to-market by buyer economics. Treat golf-course fleet, commercial/utility buyers and personal/residential customers as distinct product and service streams with tailored warranties, financing and service bundles.
- Hedge supply with pragmatic M&A and partner networks. Use acquisition selectively to secure refurbishment capacity, battery remanufacture, or regional dealer control—where scale matters—while pursuing partnerships for local last-mile fulfillment where geography or regulation imposes costs.
Risk posture and sensitivity
- Raw material and component volatility. While lithium costs have eased recently, price shocks remain possible and can compress refurbishment economics rapidly.
- Regulatory friction. New battery rules and transport limits can raise compliance costs and require capital investment in testing, labels and logistics changes.
- Inventory saturation risk. High-volume electric model introductions increase used-vehicle supply; opportunistic entrants may drive price pressure in the mid-tier segment.
- Environmental liabilities. End-of-life battery handling and disposal regulations will increasingly shape lifecycle economics and reputational risk.
Closing — the strategic moment
The used golf cart market is no longer an ancillary channel; it is a strategic avenue to extend brand touchpoints, grow margin pools and influence future new-vehicle purchasing decisions. With the market expanding from approximately USD 1.32 billion in 2020 to USD 1.75 billion in 2025 and a projected path to roughly USD 2.68 billion by 2032 at a 6.25% CAGR, 2026 is the pivotal year to institutionalize certified programs, battery lifecycle capability and regulatory-compliant logistics.
PW Consulting’s report provides the granular playbooks, scenario-tested financial models and competitive benchmarks that executives will need to convert the secondary market into a predictable, profitable channel. For full datasets, segmented forecasts, and the complete suite of operational checklists and anonymized transaction economics, download the full report on the PW Consulting website or contact our advisory desk for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Used Golf Cart Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


