



PW Consulting: Fertility Drugs Market to Rise from USD 5.32B in 2025 to USD 8.05B by 2032 at a 6.1% CAGR — Injectables (USD 4.21B) and Gonadotropins Lead, North America Tops at USD 1.86B

Fertility Drugs Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
PW Consulting’s latest market study on Fertility Drugs synthesizes five years of historical dynamics and a forward-looking seven-year forecast to give executives, investors, and policy-makers the actionable intelligence they need for 2026 planning. Anchored on a 2025 base year and an independently modeled forecast through 2032, the report combines granular commercial scenarios, supply-chain stress testing, and competitor playbooks to inform high-stakes choices across R&D, manufacturing, and go-to-market strategy.
Fertility Drugs Market
Market at a Glance: Robust Growth, Concentrated Supply
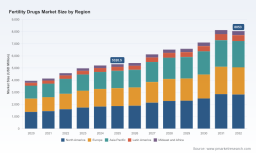
From 2020 through 2025 the global fertility drugs market expanded from roughly USD 3.95 billion to about USD 5.32 billion, reflecting sustained demand for assisted reproductive technologies and wider therapeutic use of fertility agents. PW Consulting’s forecast anticipates continued expansion from 2026, with a compound annual growth rate of approximately 6.1% over the 2026–2032 horizon, arriving at a market size in the vicinity of USD 8.05 billion by 2032.
Fertility Drugs Market
Two structural observations are vital for strategic planners: first, the market is meaningfully concentrated at the top—our concentration metrics show that the three largest players control a commanding share of revenue, with the top five firms representing an even larger portion. Second, revenue remains skewed toward biologics and injectable formats, which drives different commercial, regulatory, and manufacturing considerations than markets dominated by oral generics.
Fertility Drugs Market
Why 2026 Is a Pivotal Year for Corporate Decision-Making
- Policy pressure and pricing reform: Recent policy initiatives, including government-backed programs introduced in late 2025 that target IVF drug pricing, are reshaping payer dynamics and creating new reimbursement risk and opportunity. Companies must present defensible value-for-money propositions and new distribution models that align with emerging public procurement mechanics.
- Supply fragility and raw material risk: Shortage updates for key gonadotropins in 2026 highlight the fragility in biologics supply chains. Organizations that can de-risk active pharmaceutical ingredient access and scale flexible manufacturing will obtain a near-term competitive advantage and preserve clinic relationships.
- Generics and biosimilar momentum: The market is entering a phase in which launches of generics and biosimilars for core fertility agents are accelerating. This will pressure prices in certain segments and open choices for payers and clinics—requiring incumbent innovators to rethink lifecycle and access strategies.
Report Deliverables: Practical Tools for Executives
The PW Consulting report is intentionally operational. Rather than providing static charts, it equips decision makers with models and playbooks they can apply directly to 2026 initiatives. Key deliverables include:
- Revenue and scenario models: A set of deterministic and probabilistic models covering base, accelerated-generic, and disruption scenarios—calibrated to our 2026–2032 forecast. These models support sensitivity tests around price erosion, reimbursement shifts, and clinic utilization changes.
- Launch and access playbooks: Tactical guidance for new compound introductions, biosimilar market entry, and line extensions—covering pricing corridors, formulary submission timing, and clinic partnership frameworks.
- Supply-chain resilience tool kit: A prioritized set of interventions (dual-sourcing strategies, contract manufacturing partnerships, fill/finish optimization, and inventory hedging templates) tailored to biologics-heavy portfolios.
- Payer and procurement impact assessments: Country-level reimbursement scenarios and payer negotiation scripts that reflect evolving public initiatives and private clinic networks.
- Competitive response playbooks: Market-entry, defense, and consolidation tactics specific to the fertility drugs landscape, with actionable M&A scouting lists and partnering archetypes.
Competitive Landscape: Strategic Implications for 2026
The competitive map combines large multinational innovators, specialized reproductive medicine players, and a growing cohort of generics and biosimilar entrants. Our analysis of incumbents and challengers yields the following strategic takeaways:
- Incumbent innovators (e.g., established branded portfolios): Firms with comprehensive fertility portfolios retain scale advantages in clinic relationships, clinical evidence, and integrated service offerings. To defend position in 2026 they should prioritize: (a) value-based contracting pilots with large clinic groups and payers, (b) manufacturing partnerships to shore up supply, and (c) targeted lifecycle investments—such as digital adherence and bundled services—that increase switching costs.
- Specialist reproductive medicine companies: These players can exploit clinical intimacy and product specificity to maintain margin resilience. Strategic options include co-development of biosimilars with regional partners, exclusive clinic agreements, and development of adjacent services (e.g., diagnostics, patient navigation) to deepen revenue per patient.
- Large diversified pharma: Global pharma companies bring scale manufacturing, regulatory muscle, and distribution reach—assets that facilitate rapid response to shortages and large procurement opportunities. However, to compete in price-sensitive segments they will need lean product versions, focused go-to-market models, and often local partnerships.
- Generics and biosimilar entrants: Cost-driven manufacturers in India, China, and established generic players are poised to exploit price arbitrage and address shortages. Their success will hinge on regulatory approvals, supply reliability, and strategic partnerships with clinic networks.
Recent industry developments reinforce these dynamics. The market has seen generic launches of core ovulation-inducing agents and expanded access to generic antagonists, while regulators have issued shortage notices for critical gonadotropins—amplifying opportunity for biosimilars and alternative supply chains.
Key Strategic Moves for 2026
For executive teams planning 2026 priorities, PW Consulting recommends a three-pillar approach:
- Defend revenue through differentiated value: Invest in bundled care offerings, digital adherence tools, and clinic-level service packages that make switching to lower-cost alternatives less attractive for physicians and patients.
- Prepare for biosimilar and generic pressure: Accelerate biosimilar development where scientifically and commercially viable; pursue licensing or co-marketing agreements to capture volume economics; and deploy selective price-led tactics in low-margin segments.
- Harden supply and margin resilience: Map critical raw materials and biologics nodes, qualify alternate suppliers, and negotiate flexible contract-manufacturing arrangements that can be scaled under shortage scenarios.
What Our Competitive Profiles Reveal
Our company-level profiling goes beyond product lists to assess strategic posture—R&D pipelines, manufacturing footprints, commercial reach, and partnership appetites. Examples of insights readers will find in the full report:
- How leaders with established gonadotropin portfolios can leverage clinical evidence and patient-support programs to sustain premium pricing in key markets.
- Where specialist companies should focus clinical and market access investments to convert performance advantages into share gains.
- How large pharmas can deploy global supply chains to arbitrage shortages and rapidly scale generic or biosimilar introductions where regulatory paths are favorable.
- Which generics manufacturers are positioned to capitalize on short-term supply gaps and lower-cost clinic channels—creating near-term volume opportunities.
Regulatory and Reimbursement Watch — Implications for Action
Regulatory shifts and reimbursement reform are accelerating. Recent policy statements targeting IVF drug pricing introduce a new layer of public procurement dynamics, and agency shortage notices have already changed clinic behavior. Our report includes an up-to-the-minute regulatory tracker and practical templates for engaging with payers and regulators—essential for companies that must balance patient access with commercial viability.
Next Steps: How to Use This Intelligence
PW Consulting’s Fertility Drugs Market report is designed as both a strategic compass and a tactical manual for 2026. Companies engaged in any of the following will find immediate value:
- R&D leaders prioritizing biosimilar or reformulation projects;
- Commercial teams planning market access, pricing, and clinic partnerships under new procurement regimes;
- Supply-chain and operations executives building resilience into biologics manufacturing footprints;
- Investors and corporate development teams evaluating M&A targets, partnerships, and licensing opportunities.
To preserve the strategic edge for our clients, PW Consulting has deliberately presented overarching market sizing, concentration metrics, and forward growth rates here while reserving detailed segment-level matrices, country-by-country forecasts, and proprietary price-elasticity models for the full report. Those datasets and our interactive scenario models enable precise quantification of revenue risk and opportunity at the product, regional, and channel level.
Accessing the Full Analysis
For decision teams preparing budgets, partner strategies, or R&D roadmaps for 2026, the full PW Consulting report provides the empirical backbone necessary to commit capital with confidence. The comprehensive package includes downloadable models, competitor scorecards, and bespoke consulting hours for tailored workshops.
Contact PW Consulting to arrange a briefing and to obtain the full dataset and scenario tools that underpin the findings summarized above. Our team stands ready to help translate these market dynamics into defensible, revenue-driving actions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Fertility Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


