



PW Consulting: Brake Hoses Market Hits USD 22,030 Million in 2025, Poised for 4.12% CAGR Through 2032

Brake Hoses Market — 2026 Strategic Preview
Executive summary
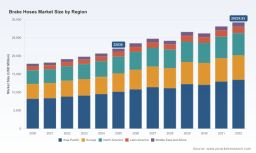
As original equipment and aftermarket dynamics converge under intensifying safety standards, the global brake hoses market presents a stable, predictable growth corridor for 2026 decision-making. Our analysis shows the market expanded from approximately USD 17,850 million in 2020 to roughly USD 22,030 million in 2025, and PW Consulting projects a continuation of expansion across the 2026–2032 horizon with an implied compound annual growth rate of 4.12%. By 2032 the market is modeled to approach the upper end of the next decade’s demand band, underpinned by incremental vehicle production, regulatory reinforcement and selective material migration toward higher-performance constructions.
Brake Hoses Market
Why this report matters for 2026 planning
- Actionable foresight: The friction between OEM performance expectations and aftermarket cost pressures makes 2026 a pivotal year for supplier selection, costing models and certification roadmaps. This report translates macro trajectories into operational choices that reduce implementation risk.
- Regulatory timing: With FMVSS 106 and SAE J1401—and their associated certification and DOT registration obligations—remaining non-negotiable, companies must align product design, testing and supplier onboarding timelines to compliance milestones. Our report maps those timelines against procurement and certification lead-times.
- Capital allocation: Whether your organisation is considering capex to localize production, invest in stainless/PTFE manufacturing lines, or pursue M&A, the report offers investment-grade scenario outputs that link market growth, margin pressure and concentration metrics to expected return windows.
Market dynamics shaping 2026
The next 12–18 months will be defined by three convergent forces: regulatory intensification, vehicle fleet transitions (including hybrid and electric architectures), and selective material substitution. Synthetic rubber remains the baseline for cost-sensitive applications; however, stainless steel braid and PTFE solutions are gaining traction where thermal performance and corrosion resistance materially alter total lifecycle cost.
Brake Hoses Market
Regulatory requirements continue to set the floor for product performance. FMVSS 106 prescribes labeling and baseline performance thresholds while SAE J1401 drives test protocols for expansion, burst strength and environmental endurance. In practice, OEMs frequently specify test passports that exceed statutory minima, creating a bifurcated demand profile: large-scale, standardized rubber assemblies for mass-market fitment, and higher-value specialized hoses for premium and commercial segments.
Brake Hoses Market
Supply-chain realities—raw material pricing volatility for synthetic rubber and the logistics footprint for braided assemblies—will pressure lead times and working capital in 2026. The market concentration profile is moderate: the top three players account for roughly one-third of industry revenue, and the top five approach the mid-forties percentage mark, indicating a competitive field where scale helps but niche specialists retain influence.
Competitive landscape — strategic implications
We assessed incumbent and rising players through the lens of capability clusters: scale manufacturers, specialized high-performance suppliers, vertically integrated OEM partners, and regionally dominant independents.
- Scale and breadth — Global industrial players that include brake hoses as part of broader fluid power portfolios provide reliability of supply and global logistics platforms. These firms typically win OEM programs where cost-optimization and multi-region sourcing matter.
- Technology and performance — Suppliers with advanced materials expertise and high-throughput testing regimens command premium positioning for thermal- or chemical-resistant applications. Their value proposition is less about price and more about lifecycle risk mitigation.
- Vertical integration and aftermarket reach — Vertically integrated manufacturers that control assembly, testing and distribution are advantaged in tightly regulated aftermarket channels where DOT registration and traceability are decisive procurement filters.
- Regional champions and specialist OEMs — Companies with near-monopolistic presence in particular national markets or strong OEM relationships can act as defensive partners or attractive acquisition targets, depending on a buyer’s strategic intent.
Representative profiles illustrate these dynamics:
- A Japan-headquartered specialist with dominant domestic share exemplifies how focused incumbency secures margin and program continuity for local OEMs while selectively exporting expertise.
- Global industrial suppliers headquartered in North America and Europe leverage diversified product portfolios to bundle fluid-transfer solutions for customers seeking single-source complexity reduction.
- Highly specialized European and Asian manufacturers maintain differentiation through rigorous testing standards and customer-specific engineering for heavy commercial and high-performance passenger applications.
- Newer vertically integrated producers that secured early DOT approvals have rapidly captured aftermarket share across multiple OEMs by shortening certification cycles and controlling assembly traceability.
Recent signals and what they mean for 2026
- Trade-show participation and technology showcases reflect ongoing product innovation and the continued importance of industry forums for specimen approval and procurement relationships.
- New product launches that emphasize compliance to SAE and FMVSS testing indicate suppliers are balancing cost with incremental performance — a sign that incremental design improvements are a primary battleground.
- Updated certification lists and compliance registries highlight an administrative burden that, if mishandled, introduces market access risk for both aftermarket players and component exporters.
Strategic playbook for 2026 — five practical moves
- Certify early, test often: Accelerate SAE J1401 and FMVSS 106 testing cycles for any new material or end-fitting design. Early certification de-risks ramp and opens aftermarket channels faster.
- Diversify supplier archetypes: Combine scale suppliers for base volumes with niche specialists for premium programs. This hybrid supplier model balances cost, performance and resilience.
- Prioritise traceability: Implement serialized packing and assembly traceability where DOT registration is required; aftermarket and fleet operators are increasingly demanding end-to-end supply chain visibility.
- Material strategy alignment: Define material roadmaps that map rubber for high-volume cost control and stainless/PTFE for performance-critical fitments; allocate R&D and capex accordingly.
- Prepare M&A and partnership playbooks: Look for targets that plug capability gaps (e.g., certification know-how, vertical assembly, geographic distribution), and structure earn-outs tied to certification milestones and OEM approvals.
What PW Consulting’s full report delivers (practical, not platitude)
The published Brake Hoses Market report is designed as an operational toolkit for procurement leaders, product managers and M&A teams. Key deliverables include:
- High-resolution top-down market model (base year 2025; forecast 2026–2032) with scenario sensitivities tied to vehicle production, regulatory tightening and material-cost swings.
- Supplier scorecards that evaluate capability across certification, production footprint, testing regime, vertical integration, and aftermarket reach—scored and ranked for fast shortlist creation.
- Regulatory impact matrix that translates FMVSS 106 and SAE J1401 obligations into program-level action items and project timelines for certification, labeling and DOT registration.
- Commercial playbooks: procurement negotiation levers, volume/price breakpoint models, inventory policy recommendations and penalty-avoidance clauses tailored to brake-hose supply contracts.
- Technology deep dives on material substitution, assembly techniques and end-fitting design trade-offs, including relative lifecycle cost frameworks (CAPEX, OPEX, warranty exposure).
- M&A diagnostics and target-filter templates that prioritize candidates by capability gaps, integration risk and near-term certification hurdles.
- Implementation timelines and a staged roadmap that align R&D, testing, supplier onboarding and go-to-market for a 12–24 month activation horizon.
To respect commercial sensitivities and our “teaser-first” approach, the public summary demonstrates methodology and strategic pathways while withholding the full granular segmentation tables and company-level revenue breakdowns that corporate teams need for contracting and bid preparation. Those are available in the complete report and via tailored consulting engagements.
How to use the insight in 90 days
- Month 0–1: Run supplier diagnostic using our scorecard tool to create a shortlist aligned to certification risk and volume needs.
- Month 2: Initiate concurrent testing cycles for prioritized designs; begin DOT registration where required and lock temporary supply lines for high-volume rubber assemblies.
- Month 3: Finalize supplier commercial terms anchored to our breakpoint models; trigger any strategic M&A or joint-venture diligence for capability gaps that cannot be cost-effectively built in-house.
Final note — where to get the full intelligence
The 2026 planning window rewards organisations that combine regulatory discipline with pragmatic supplier strategies. PW Consulting’s Brake Hoses Market report turns industry dynamics into executable priorities—mapping certification deadlines to procurement actions, and linking material choices to warranty and lifecycle outcomes. For teams ready to convert insight into contract language, capex decisions and M&A moves, the full dataset, supplier-level diagnostics and scenario workbooks are available on PW Consulting’s research portal or through our advisory team.
Contact PW Consulting to schedule a briefing; we will walk your leadership through the supply-side stress tests, certification calendars and a bespoke action plan calibrated for your geographic and product footprint.
For detailed analysis of this topic, please visit the official page: Brake Hoses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


