



PW Consulting: Linear Sorter Market to Expand from USD 3,240.5 Million in 2025 to USD 5,289.3 Million by 2032 at a 7.25% CAGR

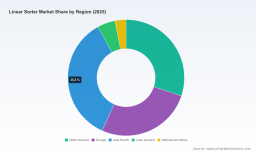
Linear Sorter Market 2026 Strategic Outlook: Why 2026 Is the Decision Year for Sortation Investment
Executive summary
PW Consulting’s latest Linear Sorter Market report (base year 2025, forecast 2026–2032) synthesizes seven years of market dynamics into a practical roadmap for executives making capital and operational choices in 2026. Our top-line modelling shows the global linear sorter market expanding from roughly USD 3.24 billion in 2025 to an expected USD 5.29 billion by 2032, representing a compound annual growth rate (CAGR) of approximately 7.25% over the forecast period. That trajectory reflects both the maturing adoption of high-throughput sortation and an acceleration driven by shifting fulfillment models, modular system designs, and continued automation investments across logistics-intensive sectors.
Linear Sorter Market
Why 2026 matters to boards and COOs
- Investment windows are compressing. Equipment lead times, integration complexity and supplier roadmaps mean procurement choices made in 2026 will shape throughput capacity and cost profiles for the next decade.
- Modularity is no longer optional. Facilities moving from seasonal spikes to continuous omnichannel fulfillment require sortation solutions that scale in discrete, low-risk increments.
- Macro forces are tightening margins. Labor pressures, rising logistics unit costs and input-price volatility (notably steel and components) make capital efficiency and predictable TCO critical selection criteria.
- Regulatory and labor constructs are shifting operations. Recent craft and workforce determinations in major postal systems are changing how induction and sortation tasks are staffed — an operational risk that must be resolved during solution selection and rollout.
Market trajectory in practical terms
The market’s growth profile — mid-single-digit CAGR with a clear acceleration in the latter half of the decade — signals a broad class of adopters moving from pilot projects to system-wide deployments. For 2026 decision-makers, this implies two immediate priorities: accelerating proof-of-concept cycles where legacy systems constrain throughput, and negotiating procurement terms that lock in performance and price protections against raw-material swings.
Linear Sorter Market
Dynamics that will shape vendor selection and deployment
- Demand-side drivers: Continued e-commerce expansion and parcel density require systems that accommodate heterogeneous parcel mixes and provide deterministic sort accuracy at scale.
- Supply-side constraints: Steel and component supply cycles remain a source of lead-time and price volatility; procurement strategies should embed escalation clauses, staged delivery, and alternative sourcing scenarios.
- Technology evolution: Architectural diversity — from sliding-shoe to cross-belt and narrow-belt solutions — affords choice but raises integration complexity. The right architecture is less about the “latest gadget” and more about throughput profile, footprint, energy use, and maintainability.
- Consolidation and competition: The market exhibits moderate concentration at the top; our concentration metrics indicate that the three largest suppliers capture a meaningful share of the market but that a broader field of regional specialists and OEMs remain influential. This market structure creates opportunity for strategic sourcing (competitive tendering, multi-supplier deployments) and for partnerships that combine global OEM capability with local engineering services.
Competitive landscape — capabilities to watch
Our vendor assessment synthesizes product capability, global delivery footprint, service models and roadmap clarity. Key players in the competitive set demonstrate differentiated strengths:
Linear Sorter Market
- Fives Intralogistics (France) — Notable for high-speed shoe-sorter platforms aimed at parcel operators and for a visible presence at major trade venues, signaling an aggressive new-product cadence and expanded systems integration focus.
- BEUMER Group (Germany) — Integrates linear sortation within broader loop and distribution portfolios; attractive to customers seeking a single-vendor approach for large-scale automated hubs.
- Dematic (KION Group, Germany/USA) — Offers proven high-volume FlexSort solutions and brings deep software and intralogistics integration expertise for complex distribution scenarios.
- Wayzim & ConfirmWare (China) — Regional specialists pushing compact, space-optimized layouts and narrow-belt designs that appeal in dense urban facilities and mixed-load environments.
- Honeywell Intelligrated / Transnorm (USA/Germany) — Known for modular, high-throughput sliding-shoe families and robust aftermarket services, positioning them for customers prioritizing uptime and throughput guarantees.
- Vanderlande, Okura Yusoki, Intralox and Gosunm — Each contributes unique technical differentiators: integration of cross-belt architectures, specialized carton handling, container-directed sorting and solutions for complex package geometries.
Recent vendor activity underscores product and commercial momentum: in late 2025 several vendors exhibited next-generation sortation platforms at regional and global trade events, and major contract awards for specialized sorter modifications highlight ongoing innovation in induction and bundle handling. These near-term moves will influence supplier roadmaps and should be reflected in RFP timelines for 2026 projects.
What the PW Consulting report delivers — practical assets for decision-makers
Our research is structured to support procurement, engineering and corporate strategy teams with executable tools rather than abstract forecasts. Deliverables include:
- Concise executive dashboards that map demand scenarios to required throughput and footprint for 2026–2028 deployment waves.
- Vendor scorecards and a weighted selection matrix covering TCO, integration risk, service SLAs and roadmap alignment.
- CapEx, OpEx and payback models calibrated to real-world throughput ramps and labor-replacement scenarios, with sensitivity to steel and component cost swings.
- Implementation playbooks: phased rollout sequencing, brownfield retrofit guidance, and mechanical/electrical integration checklists for seven common facility archetypes.
- Pilot-to-scale templates: KPI definitions, acceptance criteria, and commissioning checklists that shorten time-to-value and reduce go-live risk.
Importantly, in keeping with our “trailer” approach, this communiqué presents the market arc and strategic implications while preserving detailed, transaction-level tables and proprietary segmentation models for licensed report access. Those datasets include regional and application-level sizing, vendor revenue shares by segment, and granular CAPEX assumptions that materially affect procurement negotiations.
Actionable implications for 2026 planning cycles
- Procurement: Issue staged RFPs that separate core sortation hardware from value-added software/integration to enable multi-sourcing and to reduce vendor lock-in.
- Operations: Prioritize modular installations that can be validated in a single shift window; require vendors to deliver deterministic commissioning timelines and spares strategies.
- Finance: Use scenario-linked TCO models to compare refresh vs. retrofit outcomes under commodity-price stress and seasonal demand variance.
- Risk & Compliance: Account for evolving labor determinations and craft assignments in tender specifications; build labor contingency line items into OPEX models.
- Strategic M&A and Partnerships: Consider bolt-on relationships with regional integrators to combine global OEM technology with local installation and aftermarket capabilities.
How executives should use this report in 2026
Boards and senior operational leaders should treat the PW Consulting Linear Sorter Market report as a decision-enabling dossier: it converts macro trajectory into specific, testable procurement strategies, and supplies the commercial levers necessary to manage price, schedule and risk. The report is designed to inform three front-line actions in 2026 — fast-prototyping of one high-value site, disciplined tendering for a multi-site deployment, and renegotiation of maintenance terms to reflect increased automation utilization.
Next steps & where to get the full intelligence
This press release outlines the strategic contours and practical implications of the linear sorter market through 2032. For teams preparing 2026 capital plans and vendor selections, the full PW Consulting report includes the granular models, regional and application splits, and vendor revenue benchmarking required to finalize procurement strategies. We intentionally reserve those detailed tables and bespoke scenario outputs for report subscribers and corporate clients; visit our report page to download the executive summary, request a vendor briefing, or commission a tailored workshop.
Authored by: Senior Strategic Advisor & Chief Industry Analyst, PW Consulting — delivering market clarity and executable plans for supply-chain and intralogistics leaders preparing for the critical decisions of 2026.
For detailed analysis of this topic, please visit the official page: Linear Sorter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


