



PW Consulting: Anti-Drone System Market to Expand at 26.35% CAGR, Reaching USD 13,775.4 Million by 2032

PW Consulting Release: Anti-Drone System Market — 2026 Strategic Imperatives for Decision-Makers
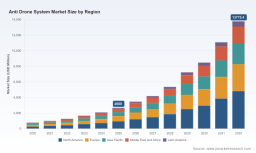
PW Consulting today publishes an executive market brief accompanying our full Anti Drone System Market report, designed to arm procurement leaders, defense planners, critical-infrastructure operators, and strategic investors with the evidence-based insights necessary to make high-consequence decisions in 2026. The market for anti-drone systems has evolved from niche airspace-protection products to an integrated platform market: after accelerating from under USD 1 billion in 2020 to USD 2.68 billion in 2025, our model forecasts continued rapid expansion to roughly USD 13.78 billion by 2032 — a compound annual growth rate (CAGR) of 26.35% across the 2026–2032 forecast window. This release explains why 2026 is an inflection year and how the report translates that macro trajectory into practical, action-ready guidance.
Anti Drone System Market
Why 2026 Is a Strategic Inflection Point
-
Regulatory and procurement forces are aligning. Recent policy shifts — from tightened FAA enforcement against dangerous drone operations to expanded counter-UAS authorities in the FY 2026 NDAA — mean organizations can no longer treat counter-UAS as optional. Standardization and testing regimes (including the Pentagon’s and NATO’s recent activity) are creating clearer paths to fielding and certification.
Anti Drone System Market -
Operational demand is maturing into programmatic spending. Governments and large enterprises are moving from one-off buys toward capability programs and recurring service models. The Department of Homeland Security’s new program executive office and associated procurement funding for major-event protection exemplify a broader shift toward organized, accelerated adoption.
Anti Drone System Market -
Technology bifurcation is accelerating. Advances in sensor fusion, AI-driven C2, RF-cyber options, and directed-energy effectors are creating differentiated value propositions. At the same time, increased investment in long-range radar and detection R&D has raised the performance floor for viable solutions.
-
Competitive and capital dynamics are intensifying. Large prime awards and high-profile funding rounds are reshaping supplier economics and partnership opportunities across the value chain.
What Our Report Delivers — Actionable, Operational, and Procurement-Grade
PW Consulting’s Anti Drone System Market report is built for decision-makers who need more than high-level statements. The deliverable translates market dynamics into operational programs and procurement playbooks. Key practical contents include:
-
Proprietary market-sizing and forecasting models (2020–2032) with scenario variants tied to policy, conflict, and technology adoption drivers.
-
A technology taxonomy and performance matrix that maps detection, tracking, classification, and defeat technologies to mission profiles — enabling side-by-side capability comparisons and fit-for-purpose selection frameworks.
-
Vendor profiling and capability scorecards for all material suppliers, including architecture-level interoperability assessments and maturity indicators.
-
Procurement playbooks and RFP templates that embed testing, verification and validation (TV&V) checkpoints, data-rights considerations, and privacy/legal compliance language aligned to current US and allied guidance.
-
Operational deployment roadmaps, including pilot-to-scale decision gates, total-cost-of-ownership (TCO) models, and crew/system training requirements for multi-vendor deployments.
-
Risk and resilience primers covering supply-chain dependencies, obsolescence pathways (hardware and software), sanctions/export controls, and cyber-vector mitigations for counter-UAS platforms.
-
Investment and M&A advisory sections identifying capability adjacencies and white-space entry points for private capital seeking exposure to the sector.
Competitive Landscape — Structure, Leaders, and Strategic Implications
Our competitive analysis finds a market that is neither a pure oligopoly nor completely fragmented. The top three vendors account for roughly one-third of market revenues, and the top five cover just over half — a concentration profile that creates both defensive scale advantages for primes and room for focused specialists to win program-level roles.
-
Prime systems integrators. Large defense primes have leveraged their radar, sensor, and effector portfolios to offer layered counter-UAS architectures. These suppliers emphasize integration with existing air-defense ecosystems, large-system warranties, and programmatic contracting advantages derived from scale and institutional trust.
-
Specialists and software-native vendors. A cohort of smaller firms is competing on innovation velocity — AI-driven C2 platforms, RF detection suites, and non-kinetic mitigation options. These firms often win initial deployments based on speed of implementation and lower per-site acquisition costs, and they frequently serve as technology partners to primes.
-
Emerging disruptors backed by capital. Recent funding rounds and targeted contracts are enabling new entrants to scale sensor development and long-range detection capabilities rapidly. Capital-backed firms are becoming attractive acquirers or JV partners for incumbents seeking to supplement product roadmaps.
Representative examples (non-exhaustive) illustrate market roles and trajectories: established defense integrators delivering layered radar-to-effector solutions; RF- and AI-first companies providing fast-to-deploy detection and classification stacks; and specialist vendors offering innovative mitigation modes, from RF-cyber takeover to autonomous capture. Recent high-profile events — NATO’s counter-drone testing at its new Innovation Range, the DHS program office launch with targeted funding for major-event security, substantial private capital injections into radar startups, and large prime contract awards for integrated radar and effector packages — crystallize these trends and the competition for both capability leadership and programmatic share.
Strategic Recommendations for 2026 Decision-Makers
Drawing on our quantitative models and qualitative vendor assessments, PW Consulting highlights seven priority actions for organizations choosing how and when to invest in counter-UAS capability this year:
-
Design for layers, procure tactically. Adopt a layered architecture (detection, classification, defeat) but procure via pilot programs that validate each layer’s contribution to mission outcomes before enterprise-wide rollouts.
-
Require open integration and modularity. Contracting teams should mandate modular interfaces, defined data models, and an upgrade path for sensor and software modules to reduce lock-in and enable rapid capability refresh.
-
Use standardized V&V gates. Insist on standardized testing and certification as part of procurement (leveraging emerging NATO and DoD guidance), including privacy and communications-interception compliance checkpoints.
-
Prioritize software and AI investments. Software-defined detection and classification deliver outsized improvements over incumbent sensor-only upgrades; budget for lifecycle software support and AI model retraining.
-
Plan supply-chain resilience. Map critical components, assess supplier concentration, and include contingency sourcing in acquisition contracts to mitigate geopolitically driven disruptions and export control impacts.
-
Balance buy-build-partner decisions. For many organizations, a hybrid approach—buy core detection capability, build integration, and partner for specialized defeat modes—offers the fastest path to operational readiness with manageable risk.
-
Align procurement cadence with policy windows. The current regulatory momentum and dedicated program funding present a narrow window to secure favorable contract terms and pilot funding; program leaders should accelerate readiness activities to match procurement timelines.
How This Report Supports Board-Level and Program-Level Decisions
For executive teams and program sponsors, our report converts market trajectory into a decision framework: when to accelerate capital allocation, which capabilities to prioritize for immediate risk reduction, and what shape a multi-year procurement road map should take to balance performance, compliance, and lifecycle costs. For investors, the analysis highlights where returns are most likely to accrue — platforms that combine high-margin software services with recurring operations and maintenance revenue, and specialists that can be scaled or folded into prime ecosystems.
For readers ready to move from strategy to action: the full PW Consulting Anti Drone System Market report contains the detailed segmentation, vendor scorecards, downloadable datasets, and procurement templates necessary to operationalize the guidance summarized here. In keeping with our “trailer” approach, this press brief presents the strategic signals and high-level market contours; the detailed, source-level tables and segment breakdowns are available exclusively in the full report.
Next Steps
-
Download the full report to access market models, supplier scorecards, procurement RFP templates, and TV&V protocols.
-
Contact PW Consulting for a tailored advisory engagement: we support program design, vendor selection, pilot execution, and M&A due diligence aligned to your operational and business goals.
PW Consulting’s Anti Drone System Market report is authored by our defense and airspace-security practice and reflects synthesis of proprietary modeling, primary interviews with procurement officers and technologists, and a continuous monitoring of policy and capital flows. As threats and regulations evolve, so must the procurement playbook — this brief sets the 2026 agenda; the full study provides the tools to execute it.
— PW Consulting, Strategic Advisory and Industry Analysis
For detailed analysis of this topic, please visit the official page: Anti Drone System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


