



PW Consulting: Solid-State Lasers for Laser Processing Market Poised to Expand at 7.72% CAGR as Asia-Pacific Leads Growth

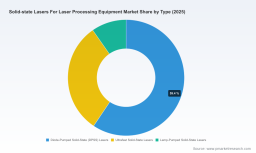
Solid State Lasers for Laser Processing Equipment Market — Strategic Outlook for 2026 Decisions
As manufacturers, OEMs, and strategic investors plan capital allocation and product roadmaps for 2026, the solid state lasers for laser processing equipment market will be a pivotal battleground. PW Consulting’s new market research briefing synthesizes five years of historical dynamics and a seven-year forecast to deliver actionable guidance for executives who must balance technology differentiation, supply‑chain resilience, and regulatory compliance. The market reached USD 3,142.5 Million in our 2025 base year and, with a projected compound annual growth rate (CAGR) of 7.72% across the 2026–2032 forecast horizon, is expected to approach the mid‑single‑billion range by 2032. That trajectory creates both disruptive opportunities and tactical risks for firms that move too slowly or without a calibrated playbook.
Solid State Lasers For Laser Processing Equipment Market
Why this report matters for 2026 decision‑makers
2026 will be a make‑or‑break year for many players in the laser processing ecosystem. Demand patterns that accelerated through 2020–2025 — driven by higher precision requirements in micro‑machining, tighter tolerances in medical device production, and increased throughput needs in electronics assembly — are evolving from product‑led to system‑level competition. Companies that understand where to invest (platforms vs modules), how to hedge raw material exposure, and which regulatory pinch points to anticipate will materially outperform peers. Our report is expressly designed to convert market data into executable decisions: capital allocation frameworks, go‑to‑market segmentation, and M&A scouting lists calibrated to 2026 timing windows.
Solid State Lasers For Laser Processing Equipment Market
Key strategic takeaways (executive summary)
- Market momentum: The market’s steady expansion through 2025 and the 7.72% CAGR expected over 2026–2032 indicate sustained demand for higher‑precision and higher‑productivity laser processing systems. That growth supports continued investment in next‑generation solid‑state architectures (ultrafast and high‑brightness fiber‑based solutions).
- Concentration & competitive pressure: The market displays mid‑to‑high concentration among leading vendors (three‑company and five‑company concentration metrics indicate a market where large incumbents retain meaningful share while room exists for specialized challengers). This structure favors M&A and partnership plays to accelerate access to end markets and technologies.
- Technology differentiation is decisive: Innovations such as pulse‑on‑demand ultrafast delivery, high‑brightness fiber modules, and picosecond platforms are shifting purchase criteria from raw power to controllability and process yield — making software, beam shaping, and application engineering as important as laser hardware.
- Regulatory & export constraints will shape market entry: Safety standards and export control frameworks create non‑technical barriers that must be integrated into commercial strategy and localization decisions.
What we found: growth drivers and tactical implications
- Application intensity over raw volume: Customers are increasingly buying for end‑process outcomes (microstructures, minimal heat‑affected zones, cycle time reduction) rather than for peak wattage alone. For 2026 product roadmaps, prioritize demonstrable process KPIs — repeatability, cycle time, yield uplift — over headline power numbers.
- Shift toward modularization: The move to modular laser subsystems simplifies integration into factory automation stacks and supports aftermarket services. Companies that provide clear migration paths (module upgrades, retrofits) will see higher lifetime revenue per install.
- Service and software monetization: Predictive maintenance, process recipes, and closed‑loop quality control will become differentiators. Licensing models for software and analytics can materially increase margins versus pure hardware sales.
- Supply‑chain volatility: Rare‑earth dopants (notably neodymium and ytterbium) remain a supply‑side risk, with price volatility observed in recent years. Hedging, multi‑sourcing, and substitution strategies should be part of 2026 procurement plans.
Regulation, standards and export control — constraints that shape strategy
- Safety and machine standards: Compliance with IEC 60825‑1 and the ISO 11553 series is non‑negotiable for machine builders and integrators. Product roadmaps must include safety engineering and certification timelines to avoid go‑to‑market delays.
- Export control implications: High‑power systems above certain thresholds fall under multilateral export control regimes. For vendors with international sales ambitions, product line segmentation and localized assembly may be required to maintain global market access.
- Raw material governance: The mining and processing concentration of key dopants creates geopolitical exposure. Our analysis shows that procurement strategies that incorporate inventory management, supplier qualification, and material substitution pilots are effective mitigants.
Competitive landscape — how incumbents and challengers are positioning
The competitive environment is shaped by a mix of industrial stalwarts and specialized innovators. Incumbent players combine deep manufacturing scale with broad service networks; challengers compete on niche performance features or cost efficiency.
Solid State Lasers For Laser Processing Equipment Market
- Trumpf (Ditzingen, Germany): Leveraging disk and rod solid‑state platforms, Trumpf focuses on industrial cutting and micromachining. Recent product introductions emphasize ultrafast pulse control and process integration, positioning them strongly where production throughput and microprecision converge.
- Coherent (Saxonburg, PA, USA): Coherent continues to expand its high‑power picosecond and ultrafast offerings with platforms targeted at industrial micromachining. Their portfolio strategy blends proprietary modules with application engineering services.
- IPG Photonics (Marlborough, MA, USA): While widely known for fiber lasers, IPG’s high‑brightness fiber modules remain central to many cutting and welding applications. Their focus on brightness and beam quality supports adoption in automated manufacturing lines.
- Lumibird (Lannion, France): With a history in Q‑switched Nd:YAG products, Lumibird serves marking, engraving, and precision ablation niches that prioritize pulse energy and reliability.
- Spectra‑Physics (MKS Instruments, Santa Clara, CA, USA): Spectra‑Physics’ ultrafast series targets high‑precision microstructuring and surface modification, emphasizing short pulse durations and fine control.
- ROFIN‑SINAR (Coherent subsidiary, Hamburg, Germany): Offers pulsed solid‑state systems for drilling and cutting metals; part of strategic consolidation in the market.
Recent product launches and trade‑show demonstrations across these vendors underscore two themes: (1) competition is increasingly technology‑led (picosecond/ultrafast and pulse‑on‑demand features), and (2) go‑to‑market execution — integration services and application engineering — is the decisive differentiator.
Where to prioritize investment in 2026
- Product R&D: Allocate budget to features that enable process repeatability (pulse control, beam shaping) and to reduce total cost of ownership through higher wall‑plug efficiency and reduced consumable dependency.
- Aftermarket services & software: Build or acquire capability in process analytics, remote diagnostics, and recipe libraries. These generate recurring revenue and strengthen customer lock‑in.
- Supply‑chain resilience: Implement supplier diversification for dopants, negotiate strategic inventory agreements, and pilot alternative materials where feasible.
- Regulatory readiness: Embed certification milestones into product development calendars, and assess whether localized manufacturing is required to avoid export restrictions for higher‑power systems.
- M&A and partnerships: Opportunistic acquisitions should target complementary application engineering teams, niche ultrafast IP, or regional service platforms — all of which can accelerate market access without materially increasing unit manufacturing complexity.
What PW Consulting’s report delivers
The full report is intentionally practical and execution‑oriented. It includes:
- Scenario‑based forecasts with sensitivity analysis across demand drivers and regulatory outcomes for 2026–2032;
- Competitive benchmarking and technology roadmaps for leading vendors and notable challengers, including product feature matrices and go‑to‑market approaches;
- Commercial templates: pricing models, ROI calculators for common industrial use cases, and procurement checklists for laser module vs. platform buys;
- Due‑diligence materials for M&A: technical validation checklists, integration risk matrices, and prioritized target lists;
- Operational playbooks for supply‑chain hedging and compliance workflows aligned to IEC and ISO standards and export control regimes.
Note: While this briefing outlines the strategic directions and headline macro numbers, the granular split by region, application, and laser type — essential for detailed prioritization — is accessible in the full report and associated datasets. Our “trailer” approach here is deliberate: the tactical segmentation and revenue‑share tables that drive precise market entry and investment sizing are proprietary to the report and available via the PW Consulting data portal.
Final recommendation — a 90‑day action plan for 2026
- Immediate (0–30 days): Run an internal audit of product roadmaps vs. process KPIs; identify gaps in pulse control, beam quality, and software integration.
- Short term (30–90 days): Secure alternative dopant suppliers and begin certification planning aligned to IEC/ISO timelines; start pilots for aftermarket subscription offerings.
- Medium term (90–180 days): Evaluate M&A or partnership candidates that close capability gaps in ultrafast IP or regional service coverage; finalize localization strategy if export controls affect product access.
2026 demands decisions that balance technical ambition with commercial pragmatism. Firms that combine differentiated laser competence with robust service propositions, regulatory foresight, and supply‑chain resilience will capture disproportionate value. PW Consulting’s full Solid State Lasers For Laser Processing Equipment Market report equips leaders with the data, scenario tools, and playbooks to make those decisions with confidence.
Learn more
For the complete dataset, granular segmentation, and bespoke advisory engagement options, visit the PW Consulting report page. Our analysts are available to brief executive teams and tailor the findings into a 2026 operating plan aligned to your strategic objectives.
For detailed analysis of this topic, please visit the official page: Solid State Lasers For Laser Processing Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


