



PW Consulting: Luxury SUV Market to Reach USD 329.75 Billion by 2032 at an 8.0% CAGR — Asia Pacific Leads with USD 74.19B

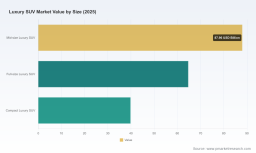
Luxury SUV Market 2026: Strategic Imperatives from PW Consulting’s Market Intelligence Brief
Introduction — Why 2026 Is the Pivotal Year
The luxury SUV segment has entered a new strategic inflection. After five years of robust expansion, the global market that stood at approximately USD 125.1 Billion in 2020 expanded to about USD 192.4 Billion by 2025. Our analysis projects continued expansion through the forecast window (2026–2032), reaching roughly USD 330 Billion by 2032 at an average compound annual growth rate of 8.0%. For executive teams setting budgets, product roadmaps, and M&A priorities in 2026, these macro dynamics require a recalibration of near-term investments and medium-term structural strategies.
Luxury Suv Market
What This Brief Offers — Executive Value in One Page
- Actionable foresight: a set of scenario-driven recommendations that translate growth trajectories into specific investment and portfolio choices for 2026.
- Competitive heat-maps: qualitative and strategic positioning of incumbent and emerging players, with implications for pricing power, platform strategy, and brand stretch.
- Supply-chain & regulatory stress-tests: how battery-material shocks, recycling mandates, and regional CO2 standards materially alter cost curves and time-to-market for electrified luxury SUVs.
- Commercial playbooks: go-to-market, retail transformation, and residual-value management templates tailored to premium segments.
Market Snapshot: Growth, Structure, and Elasticities
Our top-line projection — from USD 192.4 Billion in 2025 to roughly USD 330 Billion by 2032 at an 8% CAGR — conceals important heterogeneity. Growth is being driven by three reinforced dynamics: the rapid rise of electrified variants within premium model lines, continued consumer appetite for utility and status embodied in SUVs, and the accelerating migration of ultra-luxury buyers toward highly customized, low-volume offerings. While regional footprints and application-level splits are detailed in the full report, executives should note two universal effects visible across markets: (1) higher average transaction values for electrified luxury models, and (2) increasing margin pressure from software, warranty, and battery-legacy-cost provisions if product strategies are not tightly aligned to procurement and recycling commitments.
Luxury Suv Market
Strategic Implications for 2026 Decision-Making
- Capex reallocation toward electrified platforms: Firms that delayed platform investments now face steeper marginal costs. Our scenario work shows that prioritizing scalable EV architectures in 2026 shortens payback on battery-related capex and preserves optionality for premium derivatives.
- Supply-chain hedging is non-negotiable: Firms should secure diversified battery raw-material relationships and invest in circular-material capabilities (recycling, second-life). Regulatory tailwinds — including upcoming recycled-content thresholds in certain jurisdictions — will convert supply-chain resilience into a competitive moat for compliant players.
- Portfolio rationalization with a premium lens: Rationalize mid-cycle refreshes to concentrate resources on high-ASP, high-margin variants. Consider carving out ultra-luxury and performance sub-brands to protect mainstream brand equity while extracting premium pricing from bespoke offerings.
- Commercial model innovation: Subscription, usage-based services, and software-enabled features will increasingly influence lifetime value. Companies should pilot recurring-revenue models in priority markets in 2026 to validate economics ahead of broader rollouts.
- M&A and alliance prioritization: Bolt-on acquisitions that accelerate electrification, battery know-how, or digital retail capabilities yield outsized returns versus greenfield investments in tightly contested premium segments.
What’s Inside the Full Report — Practical Tools for Executives
- Scenario engine: Four demand and cost scenarios that stress-test product, supply-chain, and regulatory sensitivities, with clear triggers for strategic pivots.
- Playbook modules: Ready-to-deploy modules covering platform prioritization, dealer transformation, pricing architecture for electrified models, subscription bundling, and residual-value insurance mechanisms.
- Regulatory compliance roadmap: Stepwise actions for meeting recycled-content mandates and CO2 targets, including timing, capex profiles, and supplier engagement calendars.
- Supplier risk matrix: Qualitative and quantitative assessments of critical-mineral exposure, single-source dependencies, and geopolitically sensitive nodes.
- Market-entry and exit decision templates: A decision support tool that maps profitability thresholds and strategic fit for new-market launches or brand exits.
Competitive Dynamics — Who’s Shaping the Premium Landscape
The competitive map in luxury SUVs remains dominated by established premium OEMs that combine brand cachet with increasingly sophisticated electrification roadmaps. Several themes emerge from our company-level review:
Luxury Suv Market
- Incumbent German luxury houses continue to wield broad platform portfolios: they balance internal-combustion legacy models with rapid rollouts of battery-electric (BEV) and plug-in hybrid variants, leaning on deep dealer ecosystems and global brand recognition to defend pricing power.
- Heritage marques that emphasize craftsmanship and exclusivity (ultra-luxury players) monetize bespoke customization and maintain elevated margins despite lower volumes. Their strategic choices in electrification are selective — focused on preserving brand cues while meeting bespoke clients’ sustainability expectations.
- Japanese and Korean premium divisions blend reliability narratives with hybrid technology, pursuing a dual approach: defend existing combustion/hybrid customers while accelerating BEV offerings where infrastructure and demand align.
- New entrants and EV-native luxury players are compressing competitive timeframes by introducing high-range, tech-rich SUVs that expand the premium EV market and increase expectations for digital service and OTA updates.
Recent market actions underline these dynamics: marquee launches and model refreshes indicate a continued reinvestment in luxury SUV portfolios, while high-profile EV launches demonstrate the sector’s drive toward range, charging performance, and premium experience differentiation.
Supply Chain, Raw Materials and Regulation — From Cost Curve to Compliance Curve
Battery economics are a central axis of strategic planning. Independent analyses suggest a substantial decline in battery-pack costs driven by material cost reductions and scale; this is material to luxury OEMs because falling pack costs reshape feasible price points for long-range, feature-rich BEVs. Yet, downside risks persist: critical-mineral concentration in processing and geopolitical exposures remain a top strategic risk. PW Consulting’s stress tests show that single-sourcing or over-reliance on specific processing geographies could create episodic cost shocks and release timing penalties that erode luxury margins.
Regulation is converging on both environmental and circularity objectives. New recycled-content mandates in major markets introduce compliance costs and create supply advantages for upstream players who invest early in recycling and traceability. Luxury OEMs should treat compliance not as a cost center but as a competitive differentiator — demonstrating certified recycled content can be a premium marketing and brand-protection lever.
Risk Scenarios and Hedge Strategies
- Scenario A — Accelerated Electrification: Rapid EV adoption and faster-than-expected battery-cost declines favor players who scale BEV architectures quickly and can monetize software and services. Hedge: accelerate platform consolidation and secure long-term supply contracts with recycling clauses.
- Scenario B — Material Squeeze: Geopolitical disruptions elevate key-material costs. Hedge: diversify supply sources, invest in alternative chemistries, and expand recycling investments to shorten material cycles.
- Scenario C — Regulatory Tightening: Stricter emissions and circularity rules increase compliance overhead. Hedge: integrate regulatory-lifecycle assessments into product launch approval gates and create modular product updates to reduce retrofit cost.
How Senior Executives Should Use This Analysis in 2026
- Translate macro growth into internal targets: Use the report’s scenario outputs to set conservative, base, and aggressive volume and revenue targets for 2026 planning cycles.
- Test product roadmaps against supplier realities: Before committing to new derivatives, stress-test supply agreements under the report’s adverse material-price scenarios.
- Prioritize pilot investments that de-risk scale: Fund two to three regional pilots in 2026 for subscription services, digital retail, and battery second-life programs rather than rolling out universally.
- Embed regulatory compliance into KPIs: Link recycled-content and emissions milestones to executive compensation for design and procurement heads to accelerate alignment.
- Use competitive playbooks to inform M&A screening: Target small-to-midscale acquisitions that fill capability gaps in battery tech, software monetization, or circular-material handling.
Conclusion — The Strategic Premium of Informed Action
The luxury SUV market presents a distinctive paradox for 2026: expanding demand and higher transaction values coexist with tightening regulatory demands and concentrated material risks. Firms that convert macro visibility into disciplined, scenario-informed action — reallocating capex, hardening supplier relationships, and innovating commercial models — will capture disproportionate upside. PW Consulting’s full Luxury SUV Market report provides the granular decision-support tools, scenario models, and competitive analytics necessary to operationalize these strategic choices.
For teams preparing budgets, product plans, or M&A screens this year, the report functions as both a calibration instrument and a tactical playbook. Detailed segment breakdowns, regional trajectories, and the complete set of tactical recommendations are available in the full report — download access is provided on PW Consulting’s insights portal.
For detailed analysis of this topic, please visit the official page: Luxury Suv Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


