



PW Consulting Forecasts Primary Cell Culture Market to Climb from USD 6,854.2 Million in 2025 to USD 15,632.35 Million by 2032 at a 12.5% CAGR — North America and Primary Cells Set to Lead

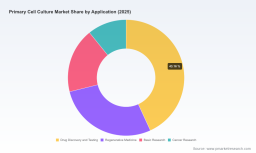
Primary Cell Culture Market — Strategic Insights for 2026 Decision-Makers
PW Consulting announces a tactical market intelligence brief designed to inform investment, commercial and operational decisions across the primary cell value chain
As companies prepare budgets and strategic roadmaps for 2026, PW Consulting’s new Primary Cell Culture Market report delivers a practical, risk-aware playbook rooted in an updated market sizing and a forward-looking scenario set. The market has demonstrated robust expansion over the past half-decade, growing from a multi-billion-dollar base in 2020 to an enlarged footprint by 2025. PW Consulting projects continued acceleration through the 2026–2032 forecast window at a compounded annual growth rate (CAGR) of 12.5%, with demand trajectories pushing the market well into the tens of billions by the end of the period. This release highlights the report’s decision-grade value without revealing the granular segment and regional tables reserved for subscribers.
Primary Cell Culture Market
Why this report matters for 2026
-
Fast-evolving regulatory expectations and R&D funding are reshaping buyer priorities. Recent public guidance and targeted funding have elevated the role of primary cell models in IND-enabling studies and organ-on-chip platforms — dynamics that materially alter product roadmaps and commercial positioning.
Primary Cell Culture Market -
Raw-material and supply-chain stress are now front-and-center in supplier selection and contract negotiation. Price pressure and export controls affecting key inputs have introduced new cost and access risks that alter margin modeling and geographic go-to-market choices.
Primary Cell Culture Market -
Market consolidation and specialization are co-occurring. The market remains concentrated among a handful of established vendors while a healthy tier of specialized challengers is expanding capabilities in areas such as 3D scaffolds and metabolically competent primary hepatocytes. Our concentration metrics — which show top-three and top-five aggregate positions — indicate a landscape in which scale and niche expertise both confer advantages.
Core dynamics shaping strategy in 2026
-
Regulatory acceleration: Regulatory authorities are increasingly recognizing primary-cell–based models as critical components of IND-enabling packages for specific therapeutic areas. This shifts buyer willingness to pay for validated, traceable cellular products and accompanying QC data, raising the bar for supplier certifications and documentation.
-
Research funding and technological substitution: Large-scale public investments in organ-on-chip and complex in vitro models increase the total addressable market for high-fidelity primary cells and specialized culture media — but they also invite competition from emerging integrated systems vendors offering bundled solutions.
-
Input cost volatility and sourcing constraints: Upstream price shocks — notably in serum and other biologics — have squeezed supplier margins and led some customers to pursue serum-free alternatives or multi-supplier sourcing strategies. Export control tightening in certain jurisdictions has created regional access differentials that matter for clinical and commercial supply plans.
-
Commercial sophistication: Buyers demand more than catalog access — they want authenticated provenance, donor metadata, lot-level QC, and co-development capability. Vendors that pair product breadth with services (e.g., assay development, custom donor sourcing) are gaining preferential supplier status among large pharma and CRO customers.
Strategic implications — five priority actions for 2026
-
Rebalance product portfolios toward validated, higher-value offerings. Firms should identify which primary cell formats and complementary media/assay services move from “nice-to-have” to “must-have” under revised regulatory expectations and payer coverage changes. Prioritize investments where scientific validation and data provenance command price premiums.
-
Operationalize supply-chain resilience. Build multi-tier supplier maps, implement stress-test scenarios for critical inputs, and negotiate conditional pricing or capacity commitments. Consider nearshoring or regional stocking strategies where export controls and logistics disruption pose material risks to clinical timelines.
-
Monetize data and quality. Packaging provenance, batch-level analytics, and regulatory-ready documentation as part of a premium offering can unlock new revenue streams and strengthen switching costs. Vendors should develop standardized data deliverables that align with client regulatory dossiers.
-
Adopt a partnership-first commercial model. Biotech and academic customers increasingly prefer co-development arrangements for custom primary-cell solutions. Structured partnership templates and milestone-based pricing reduce time-to-adoption for complex assays and help distribute development risk.
-
Prepare for selective M&A and bolt-on acquisitions. Target acquisitions should be evaluated for immediate revenue synergies, access to specialized cell types or culture platforms, and regulatory-qualified manufacturing capabilities. Due-diligence checklists must include sourcing transparency, IP status, and QC reproducibility benchmarks.
What’s in the PW Consulting report — operational and commercial tools
The report is intentionally tactical. Beyond a validated market-size model and growth scenarios, subscribers receive plug-and-play deliverables designed to accelerate decision-making in 2026:
-
Executive decision matrix mapping investment options to NPV sensitivities under three regulatory and pricing scenarios.
-
Vendor scorecard templates that weigh product breadth, QC rigor, geographic access, and service capability — built for easy integration into procurement RFPs.
-
Supply-chain stress-test models and risk mitigation playbooks, including alternative sourcing ladders for critical biological inputs and contingency warehousing options.
-
Commercial playbooks for segment-specific GTM — from academic accounts to enterprise pharma — with sample contractual clauses and SLAs oriented to cell provenance and traceability.
-
M&A due-diligence checklists focusing on biological validation, regulatory clean-room status, and backward traceability of primary cell lots.
-
Regulatory impact matrix aligning changing agency guidance and reimbursement updates to product development and labeling strategies.
Competitive landscape — positioning and recent moves
The market is anchored by established life-science and specialty suppliers that combine global reach with validated product portfolios, alongside nimble niche players that push technical differentiation. PW Consulting’s competitive analysis evaluates capability stacks across product depth, service overlay, QC standards, and go-to-market execution.
-
Thermo Fisher Scientific — A global platform player with a broad primary-cell brand recognized across drug discovery and toxicology workflows. Recent portfolio expansions into pulmonary cell types underscore a strategy of filling disease-model gaps to serve large pharma customers seeking regulatory-ready inputs.
-
Lonza — A supplier combining cryopreservation expertise with optimized culture media; recent catalog updates emphasize donor-matched offerings that appeal to developers prioritizing reproducibility and lot-to-lot consistency.
-
Merck KGaA (Sigma-Aldrich) — A broad bioscience supplier with an extensive cell catalog; their emphasis remains on providing diverse primary-cell types to research markets backed by distribution scale.
-
ATCC — A quality- and authentication-focused provider whose credentials make it a preferred source when regulatory-grade provenance is required. Recent trade-show activity signaled deeper engagement with immuno-oncology end-users.
-
Sartorius (PromoCell) — Differentiates through specialized cell types and serum-free media kits; recent ISO certification activity strengthens its position for clinical and regulated applications.
-
ScienCell, Celprogen, AcceGen, BioIVT and other specialists — These vendors push technical differentiation (3D scaffolds, large catalogs, metabolically competent hepatocytes, etc.) and often serve as nimble partners for bespoke assay development.
Recent vendor moves—product expansions, catalog updates, certification achievements, and trade-show showcases—signal an industry that is both innovating and professionalizing. PW Consulting’s vendor heat maps and capability matrices help buyers and investors separate transient marketing moves from durable capability shifts.
Risk factors to monitor entering 2026
-
Regulatory unpredictability: Shifts in agency guidance can materially affect product acceptability in regulatory submissions; firms should track guidance cycles and maintain alignment dossiers.
-
Input-cost inflation and sourcing restrictions: Volatility in biological-supply markets can compress margins and delay projects; hedging strategies and alternative-medium investments deserve priority.
-
Technological substitution risk: Integrated organ-on-chip and synthetic biology platforms may absorb growth that otherwise would have accrued to traditional primary cell sales; assess partnership and integration pathways early.
How to use the report in your 2026 planning cycle
Procurement leaders can reuse PW Consulting’s vendor scorecards and supplier negotiation playbooks to reduce sourcing risk and improve TCO. R&D heads should apply the regulatory impact matrix and technology adoption scenarios to reprioritize assay roadmaps and external collaborations. Corporate development teams will find the M&A diligence templates and scenario-based valuation adjustments useful to triage targets and set realistic price corridors. Finally, commercial teams can implement the go-to-market playbooks immediately to refine customer targeting and packaging strategies in light of evolving reimbursement and regulatory signals.
Access and next steps
PW Consulting’s Primary Cell Culture Market report combines a validated market-size model, concentration metrics, scenario-driven forecasts for 2026–2032, and hands-on operational tools to accelerate execution. To preserve the competitive edge for clients, the report intentionally withholds line-item segmentation tables and granular regional splits from public excerpts. For organizations preparing 2026 strategy, the report serves as both a compass and a toolkit — turning macro trend intelligence into actionable plans.
Contact PW Consulting to request the full report, data workbook, and the suite of plug-and-play deliverables that will support your 2026 strategic decisions.
For detailed analysis of this topic, please visit the official page: Primary Cell Culture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


