



PW Consulting: Hydroelectric Generator Repair Market to Reach USD 7,317.12 Million by 2032, Driven by a 5.22% CAGR

Hydroelectric Generator Repair Market 2026: Strategic Imperatives from PW Consulting’s Latest Study
PW Consulting’s new Hydroelectric Generator Repair Market report delivers actionable intelligence for executive teams preparing capital, operational, and M&A decisions in 2026. Drawing on an integrated analysis of historical trends (2020–2025), market forecasts (2026–2032), supply‑chain dynamics, and primary interviews with operators and OEMs, the study maps where repair demand will emerge, how cost pressures will reshape procurement choices, and which capabilities will determine winner‑take‑advantage outcomes in the next investment cycle.
Hydroelectric Generator Repair Market
Why 2026 Is a Decisive Year for Repair Investment
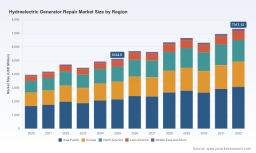
Hydropower operators and service providers are converging on a narrow window to upgrade existing assets and capture value from flexibility and resilience requirements. Our base‑year assessment (2025) places the global hydroelectric generator repair market at USD 5,124.5 Million, with modelled demand jumping to USD 5,685.7 Million in 2026 and continuing on a path to roughly USD 7,317.1 Million by 2032 under a compound annual growth rate of 5.22% for the forecast period. These macro figures reflect both cyclical project timing coming out of pandemic‑era delays and structural drivers — an aging fleet, electrification‑driven metals demand, and renewed policy incentives for refurbishment.
Hydroelectric Generator Repair Market
For corporate leaders, the implication is straightforward: 2026 is not a routine maintenance year. It is a strategic inflection point to accelerate modernization programs, optimize spare‑parts sourcing, and capture premium pricing for fast, reliable outage execution.
Hydroelectric Generator Repair Market
Key Market Dynamics Shaping Repair Strategy
-
Aging fleet and deferred modernization: Nearly two in five hydropower units globally are beyond four decades of service life, creating an outsized cohort of major generator rewinds, rotor refurbishments, and bearing replacements. These are capital‑intensive, technically complex interventions that favor suppliers with integrated engineering, field capabilities, and project management systems.
-
Raw material volatility and lead‑time risk: Copper and steel remain central to generator repairs. Recent industry data shows marked increases in copper prices and producer price indices for copper/brass mill shapes, which elevate repair bill uncertainty and extend procurement timelines for custom components. Long lead times for specialized forgings and machined parts make early procurement planning a competitive advantage.
-
Policy tailwinds and financing levers: Incentive programs and infrastructure funding in major markets have begun to lower the hurdle rate for refurbishment projects. Capital support that targets efficiency upgrades and environmental mitigation is expanding owner willingness to undertake beyond‑routine repairs that also enhance flexibility for grid services.
-
Digitization and performance engineering: Recent refits that couple mechanical overhaul with digital monitoring — for example, turbine‑generator overhauls that include condition monitoring and analytics — are creating new service tiers and recurring revenue streams. Digitally enabled refurbishments reduce unplanned downtime and allow performance‑based contracting models that align OEM incentives with owner outcomes.
What the Report Provides: Practical Tools for 2026 Decisions
PW Consulting designed this study as an operational playbook for in‑year decision making. Highlights include:
-
Investment prioritization framework — A validated scoring matrix to sequence units for repair based on technical urgency, grid value, regulatory eligibility for incentives, and supply‑chain exposure.
-
CapEx phasing and cash‑flow modelling templates — Scenario models that map repair timing to cash‑flow impacts and illustrate the sensitivity of project economics to metal price swings and lead‑time delays.
-
Vendor selection and contracting playbook — Procurement checklists, technical acceptance criteria, and contract clauses that mitigate warranty, logistics, and aftermarket spare‑parts risks.
-
Supply‑chain risk heatmap — Country and supplier risk profiles for long‑lead components, plus recommended hedging and dual‑sourcing strategies to protect schedules.
-
Technology assessment guide — Decision trees for when to pursue component replacement versus in‑situ repair, and conditions under which digitization or minor retrofits deliver disproportionate value.
-
Practical case studies — Detailed anonymized examples of recent overhauls showing timelines, cost drivers, supplier coordination challenges, and measurable post‑refurbishment performance gains.
Competitive Landscape: Capabilities That Win
The repair ecosystem combines global OEMs, specialized service houses, and regional field providers. Market concentration is moderate: the top three suppliers account for roughly 28.4% of identifiable market engagement, and the top five aggregate closer to the low‑forties percent range — a structure that rewards both scale and niche technical capability.
Key competitors profiled in the study include:
-
ANDRITZ HYDRO (Austria) — Offers end‑to‑end rehabilitation, modernization and maintenance services with substantial installed generator capacity worldwide. Their integrated delivery model is advantageous for multi‑unit refit programs requiring single‑contract accountability.
-
Voith Hydro (Germany) — Strong in full electromechanical solutions and modernization projects; competitive on turnkey refurbishments that bundle turbine and generator scopes under unified engineering management.
-
GE Vernova (United States) — Brings rotor repair expertise and manufacturing scale for new rotors; well positioned where owners value OEM‑level parts traceability and factory warranties.
-
RESA Power, HECO, Jenkins Electric, H&N Electric (United States) — These specialist players provide high‑touch maintenance, rewinds, and testing services that are frequently contracted for fast turnaround emergency work and planned rewinds.
-
Goltens and Metalock Engineering — Deliver in‑situ machining and advanced repair techniques that reduce disassembly and shorten outage duration — a critical capability for operators prioritizing availability.
-
Nidec ASI and Ansaldo Energia — Focus on generator upgrades and partial replacements where modernization aims to extend operating envelopes and integrate new control/excitation systems.
-
Regional and specialist firms (e.g., TurbinePROs, Advanced Hydro Solutions) — Often preferred for local knowledge, rapid mobilization, and specific OEM legacy equipment expertise.
Our competitive analysis goes beyond static profiles: the report rates firms across delivery metrics (turnkey capability, field engineering depth, spare parts ecosystem, digital services, and contract flexibility) and identifies which supplier archetypes are best suited to different owner strategies — from minimal‑capex life extension to full modernization that supports grid‑firming revenue streams.
Recent Signals: Projects and Policy That Matter
-
Operational modernization with digitization: A major North American overhaul recently combined mechanical refurbishment with digital upgrades to improve low‑cost clean generation — a blueprint for high ROI refurbishments that reduce forced outages.
-
Large public solicitations: High‑profile solicitations for turbine replacements and generator rewinds signal continued public investment in critical dam infrastructure, which tends to catalyze regional service demand and supplier mobilization.
-
Penstock and civil support: Ongoing penstock refurbishments in long‑running fleets highlight cross‑discipline project risk: generator repairs are frequently coupled with civil and hydraulic scopes, necessitating integrated project delivery capabilities.
-
Data consolidation at policy level: Updated national reports emphasize incremental capacity gains through refurbishments and support more aggressive refurbishment pipelines in regulated markets.
Strategic Recommendations for 2026
-
Adopt a prioritized, staged approach to overhauls: Use a scoring framework to sequence units for intervention — prioritize projects that unlock ancillary revenue or reduce high‑probability failure risk.
-
Hedge raw‑material exposure and de‑risk long‑lead items: Negotiate supplier commitments for critical copper and steel components early, and build conditional contracts that allow schedule flexibility while protecting price risk.
-
Leverage digital retrofits to defray capex: Where full mechanical replacement is not immediately necessary, deploy condition monitoring and analytics to extend life while creating a data‑backed path to future modernization.
-
Choose contracting models to align incentives: Performance‑based contracts that tie supplier payments to availability and efficiency gains can transfer execution risk and improve lifecycle outcomes.
-
Invest in multi‑discipline supplier relationships: Integrated projects that include civil, mechanical, and electrical scopes favor suppliers capable of cross‑scope coordination — owners should evaluate supplier ecosystems, not just unit prices.
How This Report Helps Executives Make Better 2026 Calls
Executives face three concurrent uncertainties in 2026: the timing of project cash flows, material cost volatility, and supplier capacity constraints. PW Consulting’s report converts these uncertainties into decision levers. By combining a transparent market forecast (with base‑year sizing and a clear CAGR trajectory), scenario modelling templates, and a supplier capability matrix, the study lets leaders align capital allocation with operational risk tolerance and strategic objectives — whether that objective is maximizing generation availability, extending asset life at low cost, or positioning assets for new grid‑service revenue.
Importantly, the report acts as a “decision accelerator.” It provides not only the diagnostic — where risk and opportunity are concentrated at the market level — but also the prescriptive playbooks, procurement language, and case examples that enable faster, lower‑risk execution during the 2026 contracting season.
Next Steps
For executives preparing 2026 budgets and procurement plans, the report offers immediate value: actionable frameworks, validated market forecasts, and tactical guidance to reduce outage duration and materially improve project economics. PW Consulting invites operators, investors, and supplier executives to engage with the full study for proprietary segmentation, supplier scoring, and downloadable modelling tools that support rapid prioritization and contracting execution.
For detailed analysis of this topic, please visit the official page: Hydroelectric Generator Repair Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


