



PW Consulting Forecasts Modular CNG Fueling System Market to Reach USD 2,458.8 Million by 2032, Growing at a 6.75% CAGR

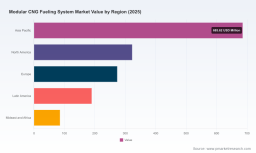
Modular CNG Fueling System Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
PW Consulting’s new Modular CNG Fueling System Market report (base year 2025, forecast 2026–2032) delivers the targeted market intelligence executive teams need to make high‑confidence decisions in 2026. The market has expanded from approximately USD 1,120 million in 2020 to USD 1,556.7 million in 2025 and is projected to continue growing at a compound annual growth rate of 6.75% through the forecast window, reaching an expected USD 2,458.8 million by 2032. These topline metrics frame a market that is maturing but still offers room for technology differentiation, localized execution models, and new commercial structures.
Modular Cng Fueling System Market
Why 2026 Is Pivotal
-
Policy inflection points: Proposed and enacted incentives in North America and select subnational programs (notably credits and negative carbon intensity scores for bio‑CNG) are materially improving project economics for renewable natural gas (RNG) and CNG applications. New guidance on the U.S. Section 45Z Clean Fuel Production Credit and ongoing proposals for RNG vehicle credits are reshaping subsidy timing and eligibility — a key consideration for projects breaking ground in 2026.
Modular Cng Fueling System Market -
Fuel price context: Natural gas spot prices are currently at levels that improve operating economics for CNG fleets versus some liquid fuels; volatility remains an operational risk but also an opportunity for hedged supply models and virtual pipeline solutions.
Modular Cng Fueling System Market -
Execution momentum: Leading operators and OEMs are deploying modular, plug‑and‑play architectures and microgrid‑enabled compression solutions, shortening time‑to‑commissioning and lowering early‑stage capex hurdles for fleet customers and remote sites.
What the Report Delivers — Practical, Transaction‑Ready Intelligence
-
Strategic market sizing and validated growth paths: multi‑year historical tracking and a granular forecast framework that supports portfolio planning, M&A diligence, and greenfield investment timing.
-
Decision models and scenario engines: interactive total cost of ownership (TCO) templates and scenario stress tests that quantify the impact of fuel price shifts, incentive timing, and utilisation rates on project returns.
-
Technology and CAPEX/OPEX playbook: component‑level guidance (compressors, storage, dispensing, control systems), lifecycle cost levers, and procurement checklists to shorten vendor selection cycles.
-
Regulatory and carbon pathway analysis: implications of evolving federal and subnational programs — including proposed U.S. 45Z regulations and low‑carbon fuel standards — and practical compliance checklists for project eligibility.
-
Operational readiness and permitting: siting, safety compliance, and real‑world commissioning timelines supported by case studies and a permitting risk matrix for common jurisdictions.
-
Commercial playbooks: contracting templates, offtake structures (including virtual pipeline models), and risk allocation approaches for developer‑owner and fleet operator partnerships.
-
Competitive intelligence and investment scorecards: vendor benchmarking, go‑to‑market strategies, and playbooks for partnerships, licensing, and acquisitions.
Note: This briefing is intentionally high‑level; the full report contains the granular datasets, regional demand curves, cost tables and vendor scorecards required to underwrite investments and procurement decisions. Access to those datasets is available in the full report.
Competitive Landscape — Who Matters and Why
The Modular CNG fueling market displays a measured level of concentration: the top three suppliers capture just under 40% of identifiable share, while the top five account for roughly 52.6%. That market structure produces a dual dynamic — incumbents exert commercial scale and validated product platforms, while regional suppliers and system integrators remain highly relevant for tailored deployments and local service economics.
-
CMD Alternative Energy Solutions (Appleton, Wisconsin): Strength in portable, scalable systems for fleet markets and strong compliance credentials across NFPA/NGV/UL/ASME/ISO standards. Their emphasis on modularity and compliance reduces commissioning friction for customer fleets.
-
Galileo Technologies (Argentina/global): Focused on plug‑and‑play compressor modules designed for quick installation and biogas compatibility — a logical partner in markets prioritizing RNG integration.
-
BAUER Kompressoren (Germany/global): Positions as a turnkey technology provider with emphasis on investment protection and high‑reliability compressor hardware, catering to projects where lifetime reliability and resale value are primary concerns.
-
ANGI Energy Systems (part of Gilbarco Veeder‑Root): Offers end‑to‑end station delivery with validated field testing and priority control systems — attractive for fleet operators seeking single‑vendor accountability.
-
Chart Industries: Brings broader fuel systems experience across cryogenic and modular infrastructure components, enabling cross‑fuel platform opportunities for mixed CNG/LNG portfolios.
-
CORE Fueling: Differentiates with virtual pipeline and delivery models that eliminate near‑term pipeline dependency for remote or distributed fleet fueling.
-
Regional and OEM players (e.g., Neftgen/Cubogas, GRASYS, Trillium/ Love’s Alternative Energy, IMW, Enric, Atlas Copco): Provide localized execution, aftermarket service and competitive price points, often winning on proximity and integration into national fleet networks.
Key Industry Developments Impacting Investment Decisions
-
Deployment activity: Major network expansions and new retail stations continue to demonstrate commercial bankability for the segment — exemplified by recent network openings and municipal commissioning projects led by established operators.
-
Technology synergies: Orders for auxiliary power and microturbine systems that support on‑site power at compression stations signal a trend toward integrated energy systems for reliability and grid‑independence.
-
Policy changes: Proposed tax credits and carbon accounting rules are time‑sensitive triggers for project economics; understanding eligibility windows is essential to capture peak subsidy value.
Strategic Recommendations for 2026 Decision‑Makers
-
For fleet operators: Prioritize piloting modular fast‑fill and time‑fill hybrids at scale‑relevant depots to validate utilization profiles. Include RNG and LCFS credits in TCO models and partner with virtual pipeline providers in low‑density regions.
-
For station developers and operators: Adopt modular, standardized station designs to shorten lead times and reduce permitting complexity; structure offtake contracts to capture emerging build‑period incentives and long‑term fuel credits.
-
For equipment OEMs: Invest in biogas‑compatible compression and controls, and bundle remote monitoring and predictive maintenance to increase lifetime value and provide service differentiation.
-
For investors and financiers: Use staged capital deployment tied to regulatory milestones and commissioning triggers; underwrite project returns with conservative fuel price scenarios and include upside pathways for credit capture (e.g., 45Z, LCFS).
-
For policymakers: Design incentive phasing and feedstock rules with clear transition paths to avoid cliff effects; enable streamlined permitting templates to accelerate procurement for municipal and public fleet deployments.
Scenario Planning: Triggers That Move Projects from Planning to Build
-
Base case (aligned with PW Consulting’s market forecast): Steady adoption driven by fleet conversions, infrastructure modularization, and modest policy support — supports a multi‑year roll‑out strategy tuned to fleet replacement cycles.
-
Upside scenario: Rapid RNG scale‑up and favorable tax credits accelerate project IRRs and compress payback timelines — suitable for aggressive roll‑outs and platform investments in modular refueling networks.
-
Downside scenario: Prolonged low incentive uptake or unexpected regulatory constraints slow deployment; recommended mitigants include flexible station designs, convertibility to mixed‑fuel operations, and lease/fee‑for‑service commercial models.
How to Use This Intelligence in 2026
-
Underwrite projects with the report’s TCO templates and scenario outputs to align financial close timing with incentive windows.
-
Shortlist vendors using the vendor scorecard and field‑performance checklists to reduce commissioning risk.
-
Design procurement with modular specifications and service level agreements that anticipate future regulatory compliance and biogas readiness.
-
Use the policy and carbon pathway analysis to inform lobbying priorities and public‑private partnership structures where applicable.
PW Consulting’s Modular CNG Fueling System Market report is intended as the operational playbook for 2026 — combining market scale, executable tools, and vendor intelligence to move leaders from strategy to deployment. For the complete dataset, model files, vendor scorecards and jurisdiction‑level permitting guides, please consult the full report and data package on PW Consulting’s website.
For detailed analysis of this topic, please visit the official page: Modular Cng Fueling System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


