



PW Consulting: Electromechanical Robot End Effectors Market to Expand from USD 2,100 Million in 2025 to USD 4,789.47 Million by 2032 at a 12.52% CAGR (2026–2032) — Asia Pacific, Electric Grippers and Automotive Manufacturing Lead; Top‑3 Hold 42.15%

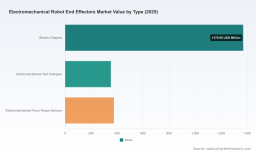
Electromechanical Robot End Effectors Market — Strategic Preview for 2026 Decisions
PW Consulting’s forthcoming Electromechanical Robot End Effectors Market report (base year 2025; historical period 2020–2025; forecast 2026–2032) synthesizes actionable market intelligence to guide executive decision-making as companies plan for accelerated automation investments in 2026. The segment has moved from an estimated USD 1,150 Million in 2020 to USD 2,100 Million in 2025 and, under our central forecast, is set to expand at a compound annual growth rate (CAGR) of 12.52% through 2032 — reaching roughly USD 4,789 Million by the end of the forecast window. This preview highlights the strategic value of our analysis while withholding the granular segmentation that appears in the full report, designed to drive readers to the source for complete, transaction-grade detail.
Electromechanical Robot End Effectors Market
Why this report matters for 2026
-
Actionable timing: 2026 will be a pivotal year for converting pilot automation to production-scale deployments. The report maps where adoption curves are steepening and identifies the product characteristics — modularity, force-sensing, and software integration — that accelerate enterprise ROI.
Electromechanical Robot End Effectors Market -
Investment clarity: With sustained double-digit CAGR expected, leaders must prioritize where to allocate R&D, M&A capital, and channel resources. PW Consulting quantifies near-term TAM expansion and highlights where margin pools are densest without exposing the sensitive micro-splits reserved for subscribers.
Electromechanical Robot End Effectors Market -
Risk-adjusted planning: Our analysis integrates supply-chain signals, regulatory shifts, and raw-material volatility into scenario-based forecasts so CFOs and procurement heads can stress-test inventory, hedging, and sourcing strategies for 2026.
What’s inside the full report (operational highlights)
-
Validated market sizing and seven-year forecast model (2026–2032) with scenario sensitivity to material costs, policy shocks, and cobot adoption rates.
-
Demand-driver diagnostics covering application vectors, technology stacks, and buyer personas — from high-throughput automotive lines to delicate food handling and pharma aseptic operations.
-
Technology and product roadmaps that benchmark electric grippers, electromechanical tool changers, and force/torque sensors against performance, cost, and integration ease.
-
Go-to-market playbooks for OEMs, system integrators, and component suppliers: pricing strategies, channel orchestration, and service-augmented offers to convert trials into recurring revenue.
-
Competitive landscaping and capability matrices — including market concentration metrics and capability gaps analysis — supporting business development, alliance, and M&A targeting.
-
Regulatory and standards compliance checklist (safety, CE, and sector-specific rules) with recommended product design adaptations and certification roadmaps for 2026 market-entry timelines.
Competitive landscape: who to watch
The market shows a moderate level of concentration: the top three global players account for a meaningful portion of installed base strength, while the top five capture a clear majority of organized market revenue — an important signal for strategy teams crafting either challenger or incumbent plays. Leading industrial players and nimble specialists are actively shaping product architectures that prioritize ease-of-integration for both traditional industrial robots and collaborative platforms.
-
SCHUNK GmbH & Co. KG — world-leading clamping and gripping systems provider, with a broad modular portfolio aimed at heavy industrial automation and high-duty-cycle applications.
-
OnRobot A/S — plug-and-play specialist targeting fast deployment on cobots and mainstream robot brands; recent demonstrations include new force/torque sensing and electric gripper launches showcased at major trade events.
-
Robotiq Inc. — focused on cobot-oriented grippers and sensors tailored to SMEs, updating adaptive gripper performance to capture lower-volume, higher-mix use cases.
-
Piab AB , Festo AG , Zimmer Group , and ATI Industrial Automation — each bringing distinct strengths in vacuum handling, precision actuation, modular tool changers, and multi-axis sensing respectively. These firms are increasingly integrating software and diagnostics into hardware offers.
-
Smaller innovators such as Soft Robotics , IPR GmbH , and Gimatic continue to push differentiated value in soft-touch handling, high-speed picking, and compact gripper form factors that enable new addressable applications.
Recent product and market activity underscores the rapid iteration cycle across the vendor landscape: new sensor and gripper launches were demonstrated at Automate and other industry shows in 2024 and 2023, while several incumbents refreshed compact electric slides and miniaturized gripper families to capture the growing cobot segment.
Key market dynamics shaping 2026 strategy
-
Standards and safety: Collaborative robot safety standards (e.g., ISO/TS 15066) are driving design requirements toward force-limiting and compliant end effectors. Companies that embed safety as a feature rather than a compliance cost will see faster adoption in mixed human-robot environments.
-
Regulatory complexity: Updates such as the EU Machinery Regulation require robust CE compliance pathways. Early investment in certification programs reduces time-to-market friction in key regions.
-
Supply-side pressures: Aluminum and other commodity stabilization in late 2024 improved visibility, but tariff regimes and geopolitical trade measures continue to introduce sourcing risk that favors diversified procurement strategies.
-
Labor economics: Rising manufacturing labor costs in multiple markets are accelerating ROI arguments for automation, but they also elevate expectations for solution economics — particularly around ease of programming and maintenance.
Strategic playbook: recommended moves for 2026
-
Prioritize modularity and open integration. Product teams should converge on architectures that minimize robot-side customization and maximize plug-and-play compatibility with mainstream robot controllers and popular cobot platforms.
-
Shift from hardware-only to product+services. Offerings that bundle predictive maintenance, remote diagnostics, and consumable replenishment drive stickiness and reveal higher-margin service revenues.
-
Design for certification early. Integrate regulatory and safety testing into development sprints to avoid launch delays in regulated regions.
-
De-risk supply chains with regional capacity. Hybrid sourcing strategies and localized assembly reduce tariff exposure and shorten lead-times — essential for capturing time-sensitive 2026 deployments.
-
Invest in channel enablement and system integrator partnerships. Training, fast-start kits, and co-marketing programs lower friction for integrators and accelerate project conversion.
-
Targeted M&A and alliances. Buyers should prioritize bolt-on acquisitions that add sensing, software, or vertical application expertise to accelerate entry into higher-margin service-led segments.
-
Commercial model innovation. Consider outcome-based pricing or consumption models where appropriate, particularly in logistics and high-mix manufacturing where predictable throughput is measurable.
How to use the full PW Consulting report
Consider this preview a strategic orientation. The full report contains the granular segmentation, competitive benchmarking matrices, and downloadable model that procurement, R&D, and corporate development teams require to build investment cases and operational plans for 2026. Subscribers gain access to: detailed regional and application splits, supplier scorecards, product feature taxonomies, and scenario-modeled P&L impacts by strategic choice.
For executives preparing capital allocation, launch roadmaps, or M&A outreach in 2026, the report turns market momentum and policy signals into executable options — prioritizing speed, compliance, and resilience without sacrificing profitability. PW Consulting’s analysis is designed to be the single-source strategic brief that aligns board-level ambition with engineering and commercial execution.
Closing perspective
Electromechanical end effectors are no longer peripheral components; they are strategic leverage points in automation initiatives. From 2026 onward, winners will be those that combine robust product engineering with services, regulatory foresight, and supply chain agility — precisely the areas PW Consulting’s full report illuminates. For a complete, transaction-ready view of the market, including all segmented detail and our forecasting model, consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Electromechanical Robot End Effectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


