



Steady Climb Ahead: PW Consulting Forecasts Rosin Resin Market to Expand at a 4.42% CAGR Through 2032

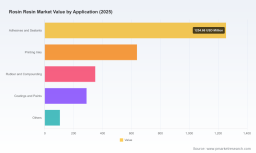
Rosin Resin Market 2026 Strategy Brief — PW Consulting Strategic Snapshot
As companies recalibrate growth plans for 2026, PW Consulting’s new Rosin Resin Market report (base year 2025; forecast 2026–2032) reframes how procurement, product, and corporate strategy teams should approach this specialty feedstock. Our modelling shows the industry at a clear inflection point: after steady expansion through the early 2020s, the global rosin resin market is projected to continue its growth trajectory at a compound annual growth rate (CAGR) of 4.42% over the 2026–2032 forecast window. In monetary terms, the market registers roughly USD 2.64 billion in 2025 and is expected to move toward the upper end of the multi‑billion-dollar range by 2032 under the central scenario — a scale that keeps rosin resin a strategically important ingredient for adhesives, inks, coatings and rubber compounding.
Rosin Resin Market
Why this matters for 2026 decision-makers
-
Margin pressure and supply volatility demand proactive procurement strategies: raw material volatility and trade policy adjustments have tangible effects on formulation costs and availability.
Rosin Resin Market -
Sustainability is now a commercial lever: bio‑based rosin derivatives and low‑VOC formulations are shifting commercial conversations from compliance to value creation.
Rosin Resin Market -
Competitive differentiation is moving upstream: control of feedstock and specialty derivative capacity has become a source of resilience and margin capture.
What PW Consulting’s report delivers (practical, board‑level and operational intelligence)
-
Proprietary top‑down and bottom‑up market models that reconcile historical 2020–2025 performance with a 2026–2032 forecast suite (central, upside, downside) — designed for scenario planning and capital allocation.
-
Price‑sensitivity and raw‑material risk matrices including alternative sourcing pathways, tolling, and inventory strategies tailored by company archetype (integrated producers, formulators, distributors).
-
Regulatory and sustainability dashboards that translate low‑VOC and bio‑product trends into actionable product roadmaps and go‑to‑market briefs for Europe, North America and APAC.
-
Commercial playbooks: customer segmentation, margin waterfall analyses, and route‑to‑market recommendations for adhesives, printing inks, coatings and rubber applications.
-
M&A, JV and capex decision tools: valuation multipliers, integration risks, and structural arbitrage opportunities across upstream (pine resin/tall oil supply), intermediate processing (esters, hydrogenated derivatives) and downstream formulators.
-
Supplier heatmaps, primary interview insights and case studies that surface operational levers (toll agreements, co‑location benefits, contract structures) for the next 12–24 months.
Note: In keeping with our "trailer" approach, this brief highlights strategic implications and modelling outcomes but deliberately omits detailed sub‑segment tables and split‑level numbers. The full dataset and drill‑downs are available in the report package.
Market dynamics that should shape 2026 plans
-
Demand vectors are shifting in composition (sustainability, packaging growth, and specialty adhesives). While traditional end‑uses remain material, growth pockets are emerging where bio‑based, low‑VOC solutions command pricing and preference advantages.
-
Feedstock volatility persists. Raw pine‑resin supply cycles and regional tapping patterns produced material price swings in recent years; procurement teams should expect intermittent supply tightness and price spikes tied to climatic and local tapping decisions.
-
Policy and trade friction are real considerations. Reciprocal tariff actions and selective exemptions implemented recently mean that cross‑border sourcing economics can shift quickly — a key reason to stress‑test supplier portfolios.
-
Product innovation is accelerating. Leading suppliers introduced new bio‑based and heat‑activated derivatives in 2024–2025, signalling a migration toward higher‑value, performance‑oriented rosin chemistries.
Competitive landscape — who matters and why
The market remains moderately fragmented by global standards (our concentration metrics show three‑player concentration well below levels typical of highly consolidated specialty chemical markets, with the five‑player group still under forty percent market share). This dynamic creates opportunity for mid‑sized players to carve differentiated positions while allowing large competitors to leverage scale for downstream integration.
-
Eastman Chemical Company (Kingsport, Tennessee, USA) — broad portfolio of rosin esters and hydrogenated resins; recent product launches extend capabilities in heat‑activated adhesive segments.
-
Harima Chemicals Group (Japan) — pine‑chemical specialization with a strong pipeline of eco‑oriented rosin products targeting packaging and construction adhesives.
-
Arakawa Chemical Industries, Ltd. (Japan) — focused on rosin esters and hydrogenated derivatives used in tackifiers and specialty chemistries.
-
Kraton Corporation (Houston, USA) — tall oil derivatives and bio‑based resin initiatives that intersect with adhesives, sealants and rubber supply chains.
-
DRT (Dérivés Résiniques et Terpéniques) (France) — pine‑derived resins with cross‑industry reach into coatings and fragrance raw materials.
-
Regional and specialty producers — prominent manufacturers across Asia, Latin America and Europe provide competitive options for formulators seeking cost and proximity benefits; several mid‑tier players are active in capacity expansion and product differentiation.
Recent product developments evidence strategic moves: new bio‑based rosin resin launches for adhesives and packaging, plus heat‑activated ester innovations, indicate that incumbents are prioritizing performance and sustainability premium capture.
Strategic recommendations for 2026 — three priorities
-
Protect margins through active raw‑material strategies. Adopt layered approaches: (a) selective long‑dated contracts with indexed pricing, (b) strategic safety stocks and blended sourcing to mitigate localized tapping reductions, and (c) commodity hedges for players with sufficient balance‑sheet flexibility. Scenario testing should be standard in procurement reviews.
-
Accelerate transition to specialty and sustainable derivatives. Where feasible, prioritize R&D and pilot commercialization of bio‑based or hydrogenated variants that meet low‑VOC regimes and command formulation premiums. Investment in downstream co‑development with key customers reduces time‑to‑value and protects share.
-
Deploy selective vertical moves. For companies facing recurring supply risk or margin squeeze, evaluate targeted upstream investments (tolling arrangements, minority stakes in pine‑resin suppliers) and downstream partnerships with adhesive formulators to lock demand and capture part of the value chain uplift.
12–24 month tactical playbook
-
Run a supplier stress‑test and a three‑scenario sourcing model (base, disrupted, accelerated demand) to quantify inventory and contract exposure.
-
Execute two pilot launches of differentiated rosin‑based formulations (one bio‑based, one performance‑oriented) with priority customers to validate price elasticity and pathway to margin uplift.
-
Negotiate flexible offtake or tolling arrangements in priority geographies to secure capacity without heavy capex.
-
Institute a regulatory watch and rapid compliance play: align formulation pipelines with evolving low‑VOC rules in key markets to avoid last‑minute reformulations.
-
Prepare an M&A playbook focused on specialty derivatives and upstream feedstock positions; pre‑identify 3–5 targets or JV partners and perform rapid valuations under multiple price scenarios.
Investment and M&A lens
Given the market’s moderate concentration and imminent margin uplifts tied to specialty and sustainable product adoption, the most attractive targets in 2026 are those that combine one or more of the following: proprietary derivative chemistries, access to secure pine‑resin feed, and strong customer co‑development relationships. Our transactional models identify clear arbitrage when platform buyers rationalize overlapping production and when strategic buyers secure upstream supply to de‑risk their formulations business.
Why PW Consulting’s intelligence is transaction‑ready
-
Our forecast is built from a fusion of primary interviews, plant‑level capacity reconciliations, and end‑market consumption modelling — enabling quick translation into capex, procurement and product decisions.
-
We provide ready‑to‑execute templates: term‑sheet language for tolling/minority stakes, a procurement KPI dashboard, and commercialization scorecards for new rosin derivatives.
-
Our price‑scenario engine is parameterised for upstream weather and tapping cycles, trade‑policy shocks, and downstream substitution — facilitating board‑level stress tests.
Concluding view — call to action for 2026
For firms that treat rosin resin as a passive commodity, 2026 will feel like a year of recurring cost surprises and squeezed opportunities. For organizations that treat it as a strategic lever — integrating procurement, product and M&A choices — rosin resin can become a tangible source of competitive differentiation. PW Consulting’s Rosin Resin Market report equips leaders with the models, playbooks and transaction readiness needed to convert uncertainty into value.
To obtain the complete dataset, sub‑segment tables, regional and application breakouts (with our recommended supplier shortlist and M&A target list), and the full suite of scenario models, access the full report through PW Consulting’s Rosin Resin Market report page or contact your PW Consulting engagement lead. The granular tables and the supplier heatmaps are intentionally omitted from this brief to preserve the value of the full report package.
For detailed analysis of this topic, please visit the official page: Rosin Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


