



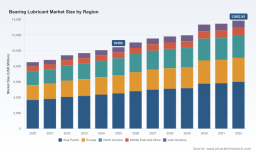
PW Consulting: Bearing Lubricant Market Set to Reach USD 13,862.95 Million by 2032 at 4.12% CAGR — Asia Pacific Leads with USD 4,528.46 Million in 2025

Bearing Lubricant Market — Strategic Outlook for 2026: Evidence-Based Guidance for Executive Decision-Making
PW Consulting’s latest Bearing Lubricant Market report provides a decision-grade view for executives planning resource allocation, product strategy, and M&A activity in 2026. Anchored on a 2025 base year, the study combines proprietary primary research, firm-level financial analysis, and market-price intelligence to deliver an evidence-led forecast. The global market is estimated at USD 10,450 Million in 2025 and is projected to grow at a 4.12% CAGR over the 2026–2032 horizon, reaching a forecasted market value that underscores steady, structurally supported expansion through early next decade.
Bearing Lubricant Market
Executive summary — the strategic problem statement
Market participants face a confluence of forces in 2026: continued equipment electrification, accelerated demand for higher-performance greases and synthetics, evolving regulatory constraints on specialty chemistries, and renewed raw-material volatility. At the same time, industry concentration metrics show that while a set of global incumbents maintain sizable footprints, meaningful opportunities remain for focused specialists and regional challengers. This report explains where those opportunities will arise, which levers create defensible margin improvements, and how to operationalize resilience into procurement and R&D plans.
Bearing Lubricant Market
Why this study matters for 2026 planning cycles
- Capital allocation: Actionable sizing and scenario outputs enable CFOs to stress-test capex and working-capital plans against commodity shocks and tariff regimes.
- Product roadmap: R&D leaders receive prioritized application clusters and performance targets (temperature, longevity, contamination tolerance) to align formulations with evolving OEM requirements.
- Commercial strategy: Sales and marketing teams can design channel, specification, and value-based pricing models informed by competitive positioning and end-market shifts.
- Regulatory & compliance planning: Legal and regulatory functions get a mapped impact of upcoming standards and restriction timetables to de‑risk product portfolios.
Report scope and methodological foundations
Our analysis spans 2020–2025 historical performance with a primary forecast period of 2026–2032. The study integrates: (a) supplier-level revenue and product mix analysis; (b) price and raw-material trend models; (c) interviews with OEMs, lubricant formulators, and distributors; and (d) scenario-based demand projections across product types, end-use applications, and regions. The segmentation framework covers regional, product-type and application-level views — the report provides full segment-level time-series and elasticities in downloadable modeling workbooks for subscribers.
Bearing Lubricant Market
Market dynamics: What is driving growth and margin pressure in 2026?
- Electrification and system integration: Higher RPM and tighter tolerances in electric motors and EV drivetrains push demand for low-torque, high-temperature-stability formulations and advanced greases tailored for precision bearings.
- Premiumization of lubricant portfolios: OEMs and plant operators increasingly favor synthetic base stocks and additive packages that extend service intervals — shifting value from commodity oils toward engineered greases and services.
- Regulatory transformation: Chemical restrictions and standards are reshaping formulation roadmaps. Notably, the phase-out of select PFAS chemistries under EU regulatory frameworks and updated international standards emphasizing oxidation stability materially influence product development priorities.
- Input-price volatility and trade policy: Base oil and synthetic feedstock price swings, together with recent tariff adjustments affecting cross-border trade, are compressing margin for lagging suppliers and creating arbitrage opportunities for vertically integrated players.
Competitive landscape — who matters and why
The market shows a mix of global lubricant majors, specialty formulators, and bearing/OEM-aligned suppliers. Market concentration indicates the top three firms hold a meaningful share of industry revenue and the top five extend that dominance — an environment that favors scale in R&D and distribution, but still leaves room for specialist value plays.
- Klüber Lubrication (Germany) — known for high-performance greases and oils in automotive, industrial and wind-energy applications. Recent product introductions emphasize food-grade and high-speed bearing formulations.
- Shell Lubricants (Netherlands) — leverages large-scale formulation capability and brands targeting heavy-duty and EV bearing use cases; expanded availability of EV-focused greases is a strategic priority.
- Mobil (ExxonMobil, USA) — strong in electric-motor and high-speed bearing segments with series optimized for temperature extremes and regulatory compliance.
- SKF (Sweden) — develops grease series aligned to bearing design, actively updating formulations to meet new chemical regulations affecting end-market durability.
- Timken, Fuchs, Dow Corning (DuPont/Molykote), TotalEnergies, Castrol (BP), Chevron — each plays differentiated roles across industrial and specialized applications, from mining and steel to aerospace and food-safe lubricants.
Recent vendor moves exemplify strategic priorities: a leading specialist launched a new food-grade, high-speed grease now certified for H1 use; a major bearing supplier updated a flagship grease to meet revised chemical restrictions for renewable-energy bearings; and a global lubricant producer expanded its offering for EV bearing applications. Those developments make clear how vendors are prioritizing regulatory compliance, application-specific performance, and coverage of electrification-driven use cases.
Key strategic implications — select insights (teaser)
- Formulation roadmap = market access. Firms that invest early in PFAS-free chemistries and oxidation-stable additive stacks will secure OEM partnerships and service contracts in regulated geographies.
- Price management and hedging matter. Given recent base oil and synthetic price volatility, procurement strategies that mix long-term supply agreements, local sourcing, and alternative feedstocks materially reduce margin risk.
- Service-led differentiation. The growing adoption of condition-based lubrication and IoT-enabled bearing monitoring creates margins beyond product sales — offering recurring revenue through service contracts and analytics.
- Channel optimization. Distributors and regional players can win by offering bundled logistics and specification compliance services; global majors must balance scale with localized formulation agility.
- M&A and partnerships will re-shape footprints. Expect acquisition activity focused on specialty chemistries, testing capabilities, and regional supply resilience throughout 2026.
Risk radar and mitigation playbook
Primary risks identified for 2026 include raw-material price shocks, accelerated regulatory bans on legacy chemistries, and tariff-driven cost pass-throughs. Each risk has a tailored mitigation strategy:
- Raw-material shocks — establish multi-sourced PAO and additive supply lines, adopt staged price pass-through clauses, and quantify margin sensitivity in rolling forecasts.
- Regulatory constraint — accelerate alternative-chemistry formulation programs, secure pre-market approvals where possible, and engage proactively in standards committees.
- Trade and tariff exposure — re-evaluate regional manufacturing footprints, exploit FTAs where applicable, and consider toll-blending arrangements to localize sensitive components.
- Technological disruption — invest selectively in condition-monitoring partnerships and licensing models to capture downstream service revenue while protecting product IP.
What the full report delivers (practical outputs)
PW Consulting’s full report is deliberately operational. Subscribers receive:
- Granular market-model workbooks covering 2020–2032 with scenario toggles for commodity-cost, tariff and regulatory outcomes.
- Segment and regional demand curves, channel economics, and price-elasticity estimates suitable for commercial planning (note: detailed segment tables are available in the subscriber portal).
- Supplier scorecards and a short‑list of target acquisition targets by capability and geography, with estimated synergy profiles.
- Actionable product-roadmap templates and specifications for priority applications (EV motors, wind turbines, food-grade bearings, high-speed electronics).
- Regulatory compliance matrix and a timeline for transitioning away from legacy chemistries in key jurisdictions.
How to use this intelligence in your 2026 playbook
- For CEOs and Strategy teams: prioritize investments in R&D that reduce regulatory and feedstock risk while enabling premium positioning.
- For CFOs: integrate the report’s commodity-sensitivity modules into quarterly forecasting and treasury hedging frameworks.
- For Product and Technical Directors: adopt the provided test protocols and specification thresholds to fast-track compliance and OEM qualification.
- For Commercial leaders: use the scenario outputs to refine channel economics and to structure service contracts around condition-based maintenance.
Closing — the trailer principle
This executive brief surfaces the strategic contours of the bearing lubricant market and provides the critical context needed for robust 2026 decision-making. The report’s public summary intentionally teases strategic directionality and supplier dynamics while preserving detailed segment tables, regional splits, and downloadable financial models for subscribers. For teams that require model-ready data, supplier-level benchmarking and full scenario outputs (including the 2026–2032 forecast workbooks), PW Consulting’s full report and accompanying toolkits are available through our research portal.
Contact PW Consulting to schedule a brief with our lead analysts or to request a demonstration of the forecast modeling tool — the fastest way to convert these insights into an executable 2026 playbook.
For detailed analysis of this topic, please visit the official page: Bearing Lubricant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


