



PW Consulting: Helicopter Crash Resistance Seats Market to Expand from USD 1,650.45 Million in 2025 to USD 2,331.65 Million by 2032 at a 5.06% CAGR

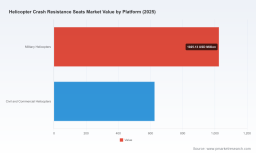
Helicopter Crash Resistance Seats Market: Strategic Imperatives for 2026 Decision-Making
As global defense priorities recalibrate and civil aviation operators increasingly prioritize occupant survivability, the helicopter crash resistance seats market has entered a period of measured expansion and technical consolidation. PW Consulting’s latest market research—anchored on a 2025 base year and projecting through 2032—maps this evolution with actionable intelligence aimed at executives preparing strategic moves in 2026. Our analysis finds the market poised for steady growth, with a compound annual growth rate (CAGR) of 5.06% over the 2026–2032 forecast period. From a sizing perspective, the industry sits comfortably in the low‑to‑mid billions (USD, revenue unit: Million) today and is forecast to climb materially by 2032.
Helicopter Crash Resistance Seats Market
Why this market matters in 2026
- Regulatory momentum is non-negotiable: Certification regimes from FAA (14 CFR §27.562), EASA (CS-27/29 dynamic crash requirements), and military standards such as MIL‑STD‑1290(AV) continue to raise the baseline for seat performance. These rules shape procurement timelines and create a persistent demand pull for certified upgrades and replacements.
- Modernization drives mixed demand: Military recapitalization programs, civil rotorcraft modernization, and retrofit cycles for high-utilization fleets are synchronizing across markets—producing a healthy replacement market alongside OEM orders.
- Material & design innovation compresses trade-offs: Advances in carbon fiber composites, cellular energy absorbers, and modular restraint systems are enabling improved energy attenuation at lower weight penalties, creating clear competitive differentiation in both OEM bids and aftermarket STCs.
What senior leaders need from a market study in 2026
We structure our research to answer the questions that matter to strategy teams, procurement heads, product leaders and M&A professionals. These stakeholders require more than directional insight: they need decision-grade inputs that align with capital planning cycles, certification timelines and supplier selection frameworks.
Helicopter Crash Resistance Seats Market
- Return‑focused procurement guidance—trade-offs between retrofit/upgrades and new‑build OEM integration;
- Regulatory roadmaps showing certification lead times and test protocols that materially affect go‑to‑market timing;
- Supply‑chain exposure analysis for key inputs (e.g., aluminum honeycomb cores, carbon composites) and scenario modelling of raw material cost shocks;
- Competitive benchmarking and supplier capability matrices that connect technical differentiators to contracting outcomes;
- M&A and partnership playbooks tailored to capture the aftermarket and secure long‑tail revenue from STCs and service agreements.
Report coverage — practical modules that drive near-term action
PW Consulting’s Helicopter Crash Resistance Seats Market report is designed as an executable intelligence package, not a high‑level summary. Core deliverables include:
Helicopter Crash Resistance Seats Market
- Market sizing and forecast model (2020–2032) with scenario layers (base, upside technology adoption, downside raw material shock) to stress test investment choices;
- Certification & regulatory matrix mapping FAA, EASA and MIL standards to testing milestones and expected approval durations for common helicopter platforms;
- Supplier due diligence templates and a CR/GR (capability, risk / growth, revenue) scoring system for shortlisting partners and acquisition targets;
- Technology deep dives—energy absorbers (cellular composites vs. honeycomb), frangible pan designs, modular restraint systems—and their operational impacts on weight, maintenance and lifecycle cost;
- Procurement playbooks for operators: retrofit pathways, Total Cost of Ownership (TCO) comparisons, maintenance and warranty implications, and contracting strategies for aftermarket STCs;
- Supply‑chain risk maps that quantify exposure to raw material volatility and identify mitigation levers such as dual‑sourcing, vertical integration, and stockpile strategies;
- M&A and partnership scenarios, including valuation sensitives tied to certification status, STC ownership and installed base footprint.
Competitive landscape — who matters and why
The market shows a moderate level of concentration: the top three firms account for nearly half of industry revenues, while the top five capture roughly two-thirds. This structure creates a landscape where established OEMs and specialist suppliers coexist with nimble niche providers—each with different risk/return profiles for potential partners or acquirers.
Key participants profiled in our research include (representative examples):
- Martin‑Baker Aircraft Co. Ltd. (Denham, UK) — renowned for crashworthy seating certified to MIL‑STD‑1290 and FAA standards, with proven energy‑absorbing systems for heavy military platforms. Their long heritage in ejection and crash systems gives them a technical moat in high‑intensity military applications.
- Safran Seats (Issoudun, France) — a strong incumbent in both civil and military markets, offering seats that meet EASA CS‑27/29 and FAA Part 27/29 dynamic crash requirements. Safran’s integrated supply chain and certification expertise make them a go‑to partner for complex OEM programs.
- IPECO Holdings Ltd. (Droitwich, UK) — modular crashworthy solutions with design features such as frangible pans and stroke mechanisms tailored for common medium‑lift platforms; well positioned for retrofit programs on models like AW139 and NH90.
- DART Aerospace (Mississauga, Canada) — notable for aftermarket upgrade kits and a pragmatic STC-focused commercial model. Recent certifications (TCCA STC for H135 and FAA STC for Bell 505) demonstrate an effective regulatory pathway that accelerates adoption among operators seeking cost‑effective upgrades.
- SKYDEX Technologies Inc. (Englewood, CO, USA) — provider of cellular composite energy‑absorbing technologies used in U.S. military validation programs; their patented materials technology is a differentiator in energy attenuation without weight penalties.
- Gentex Corporation (Carbondale, PA, USA) — manufactures integrated crew seats designed to meet MIL‑STD‑1290, combining systems integration capabilities with military program portfolio depth.
Recent market signals validate the importance of certified retrofit pathways and materials innovation: DART’s 2023 and 2022 STC approvals for H135 and Bell platforms, and SKYDEX’s contract award to support U.S. Army seat technology validation, all point to a bifurcated opportunity—OEMs continue to pursue integrated solutions, while aftermarket specialists capture accelerated retrofit demand.
Strategic implications for 2026 planning
For C‑suite leaders plotting 2026 moves, several strategic imperatives emerge from our analysis:
- Prioritize certification‑as‑a‑capability: Certification timelines are a gating factor for revenue realization. Firms that internalize testing and regulatory expertise will shorten time‑to‑market and improve bid success rates.
- Match technology to contract risk: High‑intensity military programs favor proven, heavy‑duty solutions even when costlier; civil and HEMS markets are more sensitive to weight and lifecycle cost. Segmenting go‑to‑market by tolerance for new materials will sharpen targeting without exposing commercial offers to unnecessary risk.
- Build retrofit playbooks: Retrofit STCs remain a lucrative route to market—especially for vendors able to deliver modular solutions with rapid certification pathways and operator-friendly maintenance regimes.
- Mitigate supply‑chain exposure: Firms should model raw material scenarios (e.g., aluminum honeycomb price spikes) and pursue hedging, alternative material tech (carbon fiber composites) or strategic supplier partnerships to reduce single‑source risk.
- Consider M&A selectively: Given market concentration metrics, acquisitive strategies that add certification assets, STC portfolios, or unique materials IP can be a faster route to scale than organic development—provided integration risks and certification liabilities are properly underwritten.
The PW Consulting advantage — how this report supports 2026 decisions
PW Consulting’s report does three things for leaders preparing policy, procurement or investment decisions in 2026:
- It converts regulatory and engineering complexity into program timelines and cost buckets that directly feed capital planning models;
- It links supplier capabilities to contracting outcomes so executives can prioritize partners whose strengths match program risk profiles;
- It offers scenario tools that let boards and strategy teams stress‑test plans against raw material shocks, certification delays, and accelerated retrofit demand.
We intentionally present comprehensive, decision‑ready analyses while reserving detailed proprietary segment tables, platform‑level share breakouts and full supplier scorecards for the full report. That level of granularity is essential if you are evaluating bids, modeling acquisition synergies, or structuring multi‑year supply contracts—and it is available through PW Consulting’s report portal.
Next steps for executives
- Download the executive brief to access condensed forecast scenarios and a one‑page supplier shortlist tailored to civil vs. military procurement strategies;
- Commission a short‑form due diligence pack if you are considering an acquisition or strategic partnership (includes legal/certification liability assessment and STC valuation);
- Engage our advisory team to run a 6‑week “go‑to‑market readiness” sprint aligned to your 2026 procurement or product launch calendar.
As the crash resistance seats market grows at an anticipated mid‑single digit CAGR through the early 2030s and continues to be shaped by certification demands and materials innovation, the decisions made in 2026 will determine who secures the most profitable share of OEM contracts, retrofits and long‑term service agreements. PW Consulting’s Helicopter Crash Resistance Seats Market report equips leaders with the market sizing, regulatory mapping, and supplier intelligence required to make those decisions with confidence.
Access the full report
For the full dataset, proprietary segment tables, supplier scorecards and downloadable scenario models, visit PW Consulting’s report page to obtain the comprehensive Helicopter Crash Resistance Seats Market report and supporting advisory options.
For detailed analysis of this topic, please visit the official page: Helicopter Crash Resistance Seats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


