



PW Consulting Report: High Dielectric Plastic Films Market to Reach USD 2,851.21 Million by 2032, Expanding at a 6.48% CAGR

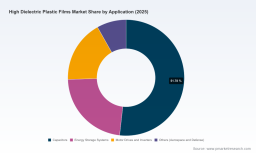
High Dielectric Plastic Films Market: Strategic Imperatives for 2026 — A Preview of PW Consulting’s In-Depth Market Study
PW Consulting’s latest industry report on the High Dielectric Plastic Films market delivers a concise but intellectually rigorous briefing that is designed to inform strategic decision-making in 2026. The market, which had an estimated global value of roughly USD 1.83 billion in the 2025 base year, is forecast to resume mid-single-digit expansion — a compound annual growth rate (CAGR) of approximately 6.48% through our 2026–2032 forecast horizon. By 2026 the market is expected to approach the USD 2.0 billion threshold, setting a platform for technology-led and application-driven expansion toward the decade’s end.
High Dielectric Plastic Films Market
Why this report matters for 2026 planning
-
Timing for capex and capacity decisions: The market’s steady growth profile, together with recent capacity announcements and product launches among leading producers, creates a narrow window to scale manufacturing ahead of demand waves in high-voltage capacitors, advanced motor drives, and energy storage modules. Our report highlights the near-term demand inflection points that should guide 2026 capital deployment and contract commitments.
High Dielectric Plastic Films Market -
Supply-chain resilience and margin protection: Upstream cost volatility — notably a double-digit year-on-year increase in fluoropolymer resin pricing — plus new freight surcharges and trade actions materially affect landed costs. The study translates these dynamics into actionable tactical levers (hedging, inventory posture, supplier qualification thresholds) that procurement and finance teams can implement immediately.
High Dielectric Plastic Films Market -
Regulatory and compliance gating: New chemical restrictions and certification standards are already influencing product eligibility in major demand markets. The report synthesizes regulatory scenarios and their likely commercial impact, enabling product and legal teams to prioritize compliance investments in 2026.
What’s inside the report — practical, decision-grade deliverables
-
Market sizing and growth scenarios: A clear presentation of the market’s historical trajectory and an evidence-based forecast through 2032. Multiple scenarios model demand under alternative adoption curves for electrification, power electronics, and aerospace/defense uses.
-
Segment priorities and technology roadmaps: Comparative analysis of film chemistries (e.g., polypropylene, polyester, fluoropolymers and specialty high-performance polymers) against performance criteria that matter to OEMs — dielectric constant, breakdown voltage, thermal stability, and manufacturability. The report provides a ranked technology-readiness map for product teams to inform NPI roadmaps without disclosing client-sensitive segment-level numbers.
-
Commercial benchmarking and supplier benchmarking toolkits: A modular framework to evaluate incumbent suppliers on cost-to-serve, quality metrics, environmental compliance, and capacity flexibility. Included are templates for request-for-proposal (RFP) language and short-list scoring that procurement can use immediately.
-
Regulatory playbooks and certification timelines: Practical checklists for achieving UL and regional compliance, with scenario timing that shows when regulatory constraints could become binding for product launches or market access.
-
Risk-adjusted pricing and margin modeling: A set of TCO and pass-through sensitivity models that account for raw-material swings, transport surcharges, and tariff regimes so pricing teams can preserve margins under stress.
-
M&A and partnership criteria: A decision framework identifying the strategic attributes (technology, capacity, customer relationships, geographical foothold) that make target assets attractive — and the valuation multiples that are defensible under multiple demand outcomes.
Competitive landscape — who to watch and why
The market exhibits moderate concentration: the three largest players account for a meaningful but not overwhelming share of global revenue, and the top five increase that concentration materially. This structure creates opportunities for both scale-driven incumbents and well-capitalized challengers that can exploit specialization.
-
DuPont — a major incumbent with deep materials science capabilities and broad electronics market relationships. DuPont’s legacy film products remain a benchmark in high-dielectric applications. Their recent capacity enhancements underscore a strategic bet on continued electronics demand; the company’s vertical integration and brand credibility make it a preferred partner for tier‑1 capacitor and power-electronics OEMs.
-
Toray Industries — a technology-focused player with targeted innovations for electric vehicle (EV) power modules and high-voltage capacitors. Toray’s product launches in late 2025 signal aggressive movement to capture higher-value segments where elevated breakdown voltage and thermal tolerance command premium pricing.
-
3M — leverages application engineering and system-level partnerships. Recent certification updates highlight 3M’s emphasis on market access and customer assurance, important differentiators when certification timelines determine procurement decisions.
-
Saint‑Gobain and AGC Inc. — both bring strong European and Asian footprints respectively, with deep experience in fluorinated polymers and specialty dielectric solutions. Their global distribution and capacity for engineered materials position them to serve high-reliability sectors such as aerospace and defense.
-
Tekra (Materion) and specialized suppliers such as Polyflon Technology — smaller but strategically important players that compete on customization, rapid prototyping, and application-specific dielectric enhancements. These firms are frequently the source of the incremental, high-margin wins in nascent use-cases and flexible electronics.
Recent developments that change the playing field
-
New product introductions by leading fluoropolymer manufacturers are shifting technical performance baselines, particularly for EV power modules and compact, high-energy capacitors.
-
Capacity expansions among incumbents are tightening windows for new entrants or late movers to secure long-term contracts with OEMs.
-
Upstream input shocks — including a notable increase in fluoropolymer resin costs due to feedstock constraints — materially alter supplier margin dynamics and the calculus around vertical integration versus long-term supply agreements.
Market dynamics and near-term risks
-
Raw-material cost inflation: Fluoropolymer resin price pressure has been a recent driver of input-cost inflation. For firms where fluorinated chemistries are integral, this increases both unit cost and the risk of supply disruption.
-
Regulatory friction: EU restrictions on certain per‑ and polyfluoroalkyl substances (PFAS) create potential product-market exclusions unless an essential-use derogation is granted; affected manufacturers must plan for reformulation risk and certification timelines.
-
Trade and tariff exposure: Elevated tariff measures affecting some trade lanes increase the landed cost of imports and may motivate reshoring, nearshoring, or regional-sourcing strategies for 2026 procurement plans.
-
Logistics and transport cost changes: Recent classifications that attract hazardous-material surcharges have added measurable freight cost to global shipments of certain fluoropolymer films, pressing supply-chain leaders to reassess distribution footprints.
-
Certification gating: High-permittivity films (permittivity above certain thresholds) now require stringent flammability and safety certifications prior to commercial deployment; this has implications for product launch schedules and cost-to-market.
What PW Consulting recommends for 2026 decision-makers
-
Prioritize supply visibility and multi-sourcing: For critical film chemistries, secure second-source agreements with performance and capacity SLAs, and build inventory hedges calibrated to customer demand and certification lead times.
-
Implement dynamic price‑pass models: Embed trigger-based price adjustments in customer contracts to protect margins against commodity swings while remaining competitive.
-
Invest selectively in high-value chemistries and co‑development: Focus R&D and licensing partnerships on film properties that unlock higher ASPs in EV power electronics, grid energy storage, and compact motor drives.
-
Accelerate compliance programs: Map products to regulatory pathways (REACH derogations, UL certifications), and front-load testing and dossier preparation to avoid go‑to‑market delays.
-
Reassess geographic exposure: Use tariff and freight scenarios to evaluate nearshore production or toll-manufacturing arrangements for key end markets, balancing cost with time-to-customer.
-
Refine M&A and JV criteria: Pursue targets that provide either strategic raw-material access, complementary technology, or immediate route-to-market with tier‑1 OEMs. Our M&A checklist in the report helps quantify synergies and integration risk without reliance on narrative assumptions.
How to use the full report
This preview is designed as a tactical briefing to orient senior leaders and functional heads preparing strategy cycles in 2026. The full PW Consulting report contains the proprietary models, supplier heat maps, regulatory timelines, and scenario workbooks that operational teams will need to execute against the strategic priorities outlined above. To preserve competitive value for our clients, the report intentionally withholds certain granular segment-level datapoints in this summary — those datasets, along with interactive spreadsheets and supplier scorecards, are available in the full publication.
Next steps
Executives preparing budgets, R&D leaders prioritizing product roadmaps, and procurement heads negotiating supplier contracts will find immediate, implementable value in PW Consulting’s full report. For access to the complete analysis, segment-level forecasts, and customizable decision tools, please consult PW Consulting’s market intelligence portal. Our analysts are also available for bespoke workshops that adapt the report’s models to your company’s balance sheet, product portfolio, and regulatory footprint.
For detailed analysis of this topic, please visit the official page: High Dielectric Plastic Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


