



PW Consulting: Robot Joint Precision Reducers Market Poised to Reach USD 11,462.27 Million by 2032 on a 15.81% CAGR

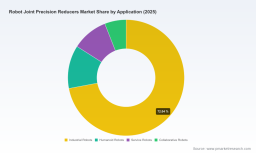
Robot Joint Precision Reducers Market: Strategic Outlook for 2026 — PW Consulting Industry Brief
Executive snapshot
The robot joint precision reducers market is entering an accelerated growth phase that will shape strategic choices through 2026 and beyond. Our new market study, anchored on a 2025 base year, projects expansion from a global market value of USD 4,102.5 Million in 2025 to USD 11,462.3 Million by 2032, representing a compounded annual growth rate of 15.81% over the 2026–2032 forecast window. This trajectory reflects intensified automation investment across manufacturing, new commercial robotics applications, and technology-driven upgrades to meet Industry 4.0 reliability requirements.
Robot Joint Precision Reducers Market
Why this matters to corporate decision‑makers in 2026
- Market momentum is both broad and punctuated: growing demand for higher torque, lower backlash, and more compact reducer families is forcing OEMs and suppliers to recalibrate product roadmaps and supply footprints.
- The market structure signals strategic leverage: the top three and top five suppliers account for a significant portion of industry revenue (CR3 ~64.8%; CR5 ~77.5%), implying meaningful barriers to entry for premium segments, while also opening partnership and consolidation opportunities for mid‑tier firms.
- Input cost and capacity dynamics have become critical variables in supplier selection, sourcing strategy, and pricing models. Our analysis shows raw‑material fluctuations and strategic capacity investments are already reshaping cost curves and delivery risk profiles.
Market trajectory and financial outlook (concise)
After steady growth in the first half of the decade, the precision reducer market crosses an inflection point in 2026. The combination of accelerating humanoid and collaborative robot programs, semiconductor and EV assembly needs, and industrial automation refresh cycles will drive above‑average growth for precision gear systems. From a market value of USD 4,102.5 Million in 2025, Pw Consulting’s scenario modelling indicates a pathway to USD 11,462.3 Million by 2032 at a 15.81% CAGR. This is not a linear expansion: the market will be shaped by episodic product launches, capacity ramps, and procurement cycles from major OEMs.
Robot Joint Precision Reducers Market
Competitive landscape — what 2026 decision‑makers must know
The competitive structure combines legacy technology leaders, precision specialists, and high‑volume manufacturers. Key observations:
Robot Joint Precision Reducers Market
- Nabtesco Corporation (Tokyo) remains a benchmark for cycloidal RV solutions, emphasizing high torque, rigidity and wide adoption among industrial OEMs. Its recent product introductions and plant investments indicate a dual focus on product refinement and capacity to capture next‑wave demand.
- Harmonic Drive Systems (Tokyo) continues to lead on strain‑wave architectures, where zero‑backlash and compact precision remain decisive for collaborative and humanoid applications. Their 2025–2026 product refreshes underscore continued innovation in miniaturization and performance per unit volume.
- Sumitomo Heavy Industries and Wittenstein represent premium alternatives in high‑performance and high‑speed niches, combining mechanical innovation with an emphasis on efficiency and vibration control.
- European and Japanese incumbents continue to define high‑end benchmarks, while a cohort of Chinese and Eastern European suppliers (including volume producers and specialist actuator firms) are expanding production and competing principally on cost, scale and integrated actuator offerings.
- Smaller specialists such as SPINEA are gaining traction by offering differentiated cycloidal architectures and actuator integration that appeal to integrators looking for compact, zero‑backlash performance without bespoke engineering overhead.
Recent vendor activity in late 2025 and early 2026 — new compact product lines, exhibitions focused on humanoid robotics, and refreshed catalogs — indicates supplier strategies are bifurcating between premium innovation and scalable cost‑effective platforms.
Supply chain, input risks and cost management
Two operational forces will be decisive for 2026 procurement and manufacturing strategies:
- Raw‑material volatility: Hot‑rolled coil prices rose substantially in early 2026, tightening margins for precision gear manufacturers and accelerating pass‑through pressures. Buyers must account for this volatility in long‑term supplier contracts, consider hedging options, and evaluate vertical integration or localized sourcing to stabilize costs.
- Capacity realignments: Major Japanese and European suppliers are investing in expanded production and automation to serve semiconductor, automotive and humanoid segments. These investments will shift lead‑time dynamics and create windows of opportunity for OEMs to secure preferential access through strategic partnerships, offtake agreements, and co‑development arrangements.
Technology and product trends to act on in 2026
- Miniaturization and high torque density: New series and size extensions introduced recently reflect an industry push to increase performance per unit volume — particularly relevant to humanoid and collaborative robots where mass and inertia are constraints.
- Integrated actuator solutions: Suppliers offering reducers as part of actuator assemblies are winning design wins by simplifying integration, reducing total system cost, and shortening time‑to‑market.
- Reliability and lifecycle services: With Industry 4.0 deployment, buyers increasingly prize reducers that support predictive maintenance and digital twin models; warranty and aftermarket service terms are becoming key competitive differentiators.
- Standardization vs customization: The tension between standardized modular units (for cost and speed) and bespoke high‑precision solutions (for performance) will dictate supplier selection strategies across OEM segments.
Strategic playbook for corporate leaders (practical 2026 decisions)
For engineering, procurement, M&A, and product strategy teams, the following imperatives should guide 2026 planning:
- Adopt a tiered supplier strategy: segment suppliers by capability (premium precision, integrated actuators, cost‑scale producers) and allocate volume to multiple tiers to balance performance and supply security.
- Negotiate outcome‑based commercial models: move beyond price‑per‑unit to performance and uptime SLAs, life‑cycle costing, and shared R&D milestones for co‑developed reducer solutions.
- Invest in qualification pipelines: shorten supplier qualification cycles by standardizing test protocols, agreeing digital interfaces, and using predictive analytics to model long‑term wear and backlash performance.
- Prepare for targeted consolidation and partnerships: given high market concentration at the top, M&A or strategic JV activity should target capability gaps (e.g., actuator integration, advanced materials) rather than volume alone.
- Hedge input cost exposure: incorporate commodity clauses, build buffer inventory for critical components, and identify alternative materials or suppliers to mitigate short‑term raw‑material shocks.
What the PW Consulting report delivers (practical content overview)
This market study is designed as a decision‑support toolkit for 2026 planners. It combines high‑resolution market sizing, scenario financial models, supplier scorecards, a technology roadmap, and buyer playbooks. Highlights include:
- Proprietary multi‑scenario financial models that let you stress‑test revenue, margin and capex outcomes under alternative demand, price, and input‑cost assumptions.
- Supplier capability matrices and a sortable due‑diligence checklist for sourcing teams — covering quality systems, IP posture, capacity elasticity and aftermarket coverage.
- Product roadmaps and comparative performance matrices for reducer architectures (cycloidal/RV, strain‑wave/harmonic, precision planetary) to help engineering teams prioritize tradeoffs in mass, stiffness and backlash.
- Operational playbooks on contract design, inventory buffers, and localized supply strategies to mitigate lead‑time and commodity risk.
- Pipeline and M&A screening tools that flag target profiles aligned with consolidation or capability acquisition strategies.
Note: the report contains full regional, type and application split datasets and granular competitive benchmarks; these detailed tables and interactive models are intentionally withheld here to encourage direct access to the primary report.
Methodology and data integrity
Our estimates synthesize primary supplier interviews, public filings, on‑site capacity surveys, and a proprietary demand model calibrated to end‑market automation spend patterns. Historical series, including 2020–2025 baseline values, were reconciled against company disclosures and market indicators. Forecasts reflect a bottom‑up build tied to robot unit forecasts, actuator penetration curves and technology substitution assumptions. For transparency, the report includes sensitivity analyses and a documented assumptions log for each scenario.
Final recommendation — the strategic window for 2026
2026 represents a decisive year to convert market momentum into durable competitive advantage. Companies that align R&D investments with actuator integration, secure resilient supply arrangements, and adopt outcome‑based commercial terms will disproportionately capture the high‑value segment of the expanding market. With the top tier suppliers controlling a substantial share of revenue, targeted partnerships and carefully structured M&A will be more effective than broad market expansion without technical differentiation.
Next steps
PW Consulting’s full Robot Joint Precision Reducers Market report provides the complete quantitative breakdowns, supplier scorecards, and interactive decision tools that corporate teams need to finalize 2026 strategy. For access to the full dataset, segmented forecasts, and our customized advisory options (including supplier selection workshops and M&A diligence support), please visit the official report page.
For detailed analysis of this topic, please visit the official page: Robot Joint Precision Reducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


