



PW Consulting: Multi‑Turn Potentiometer Market Set to Grow at 3.4% CAGR During 2026–2032, Fueled by Asia‑Pacific Demand

Multi-Turn Potentiometer Market: Strategic Outlook for 2026 — PW Consulting Insight
Executive preview
PW Consulting’s newest Multi-Turn Potentiometer Market study (base year 2025) frames the sector as a stable, technically specialized niche with measurable growth potential for suppliers and OEMs. The global market was valued at approximately USD 204.4 Million in 2025 and, under our base forecast, is expected to expand at a compound annual growth rate (CAGR) of 3.4% across the 2026–2032 projection window, reaching roughly USD 258 Million by 2032. Those headline numbers capture a market that is neither hyper-growth nor stagnation: instead, it rewards engineering differentiation, operational discipline, and supply-chain foresight.
Multi Turn Potentiometer Market
This briefing is written as a strategic “trailer”: it surfaces the research’ most consequential insights for 2026 decision-makers—investment priorities, procurement strategies, product roadmap choices, and M&A imperatives—while reserving the complete, model-level segmentation and downloadable datasets for the full PW Consulting report.
Multi Turn Potentiometer Market
Why 2026 is an inflection year for corporate strategy
-
Supply-side cost pressure: Volatility in conductive and precious-metal inputs is materially changing cost math across multi-turn potentiometer designs. In early 2026 copper crossed records intraday and precious metals used in contact finishes have also firmed. A November 2025 index tracking raw materials for passive electronic components rose sharply versus the spring of 2025—an 8% move in months—underscoring how input inflation can compress supplier margins and force OEM price renegotiations.
Multi Turn Potentiometer Market -
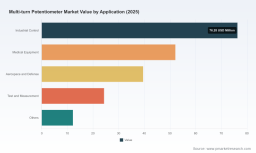
Demand composition and premiumization: End markets—industrial control, medical equipment, aerospace/defense, and test-and-measurement—continue to place a premium on reliability, tolerance, and lifecycle support. Growth is coming predominantly from higher-spec applications where long-term certification and failure-risk reduction justify higher unit economics.
-
Technology and design shifts: Hybrid and miniaturized architectures, tighter linearity specs, and increased use of sealed and ruggedized form factors mean that product differentiation is now as much about system integration and qualification capability as it is about raw resistor technologies.
What the PW report delivers for practical decision-making
-
Market sizing and scenario models calibrated to 2020–2025 history and 2026–2032 forecasts, with sensitivity runs that quantify upside/downside given input-cost shocks and demand deviations.
-
Competitive landscape landscaping—detailed vendor profiles, capability maps, and M&A fit analyses to help corporates prioritize partners or acquisition targets.
-
Cost-to-serve and BOM-level impact assessment that translates raw-material price moves into margin pressure by design archetype.
-
Actionable GTM playbooks for suppliers and OEMs (pricing frameworks, channel segmentation, service bundles, and certification roadmaps tailored to medical and aerospace buyers).
-
Supply-chain mitigation toolkit—procurement contracting templates, hedging scenarios, and near-shoring vs. offshoring decision frameworks.
Competitive dynamics — capability map (qualitative)
The market exhibits moderate consolidation: a mix of global precision specialists, regional low-cost manufacturers, and a handful of system-integrator incumbents. Leaders are differentiated by depth of precision portfolios, institutional relationships with high-reliability end markets, and the ability to deliver certified assemblies at scale.
-
Bourns Inc. (Riverside, CA) — broad precision multi-turn portfolio across wirewound, conductive plastic and hybrid elements; strong channel and long-standing OEM relationships that favor high-reliability industrial and medical programs.
-
Vishay Intertechnology / Spectrol (Malvern, PA) — entrenched in applications requiring high linearity and robustness; recognized for high-spec wirewound solutions with servo-mount and bushing options.
-
TT Electronics (Woking, UK) — competence in hybrid, miniaturized multi-turn designs and an established presence in aerospace and demanding industrial environments.
-
ETI Systems (Carlsbad, CA) — niche strength in valve-actuation and high-accuracy industrial control potentiometers; a proven partner for OEMs needing customization and long-term lifecycle support.
-
Sensor Systems LLC — deep custom engineering capability for military, aerospace and medical systems where tailored mechanical and electrical interfaces are table stakes.
-
MEGATRON (Germany), SENTOP (Shanghai), Honeywell and Althen Sensors & Controls — each brings distinct regional, cost or miniaturization advantages that buyers should map against product requirements and certification timelines.
Choosing suppliers in 2026 should be a capability-first exercise: prioritize vendors with demonstrated qualification pathways for regulated end markets and the procurement flexibility to tolerate commodity swings.
Actionable playbook for executive teams (priorities for 2026)
-
Procurement and cost management: institute dual-track sourcing—short-term hedged purchase agreements for critical copper and contact materials, alongside development of alternative material mixes (e.g., selective use of conductive plastics or plated alloys) to create optionality. Use BOM-level scenarios from the PW model to stress-test margin outcomes under ±20% raw-material swings.
-
Product & engineering strategy: accelerate modularization of multi-turn designs so that customer-specific tolerances can be delivered with fewer unique SKUs. Invest in hybrid technology where it uniquely reduces total cost of ownership for customers in medical and aerospace segments.
-
Manufacturing footprint decisions: evaluate near-shoring for programs that demand short lead times and high regulatory oversight; keep commodity-oriented production where scale and labor cost advantage persist. Balance this with supplier consolidation to reduce complexity without creating single-point-of-failure risk.
-
M&A and partnerships: favor bolt-on acquisitions that add precision assembly, test-lab certification, or specialized materials know-how. Strategic JV structures can be an effective bridge to secure capacity in constrained raw-material cycles.
-
Commercial & pricing tactics: move from unit-price competition to value-based offers—warranty, lifetime calibration, and embedded sensing services command premium pricing in the high-reliability segments that drive growth.
Supply chain and raw-material risk: what boards need to know
Raw-material inflation is the proximate threat to margins in 2026. Market intelligence shows copper and other conductive inputs spiking through early 2026, with daily price whipsaws that can erase single-quarter profits for exposed suppliers. The PW report provides a prioritized checklist for procurement leaders: contract-tenor optimization, indexed-pass-through clauses for long-term OEM agreements, and small-scale vertical integration where the capex payback is compelling.
Beyond commodity risk, controllers must model longer-term structural deficits in base metals and evaluate strategic inventory policies. Our scenario work highlights that even modest sustained increases in raw-material costs will shift the competitive balance toward suppliers who either control their supply chain or who can demonstrate lower total-cost-of-ownership to buyers.
Buyer and investor implications
-
For OEMs: emphasize supplier qualification and lifecycle sourcing. Given the market’s modest growth profile, incremental revenue is limited—procurement and reliability choices will be the primary levers for improving product margins and uptime.
-
For component suppliers: differentiation through certification capability (medical/aerospace) and services (calibration, extended warranties) will enable margin expansion despite input-cost pressure.
-
For investors: the market’s risk-return profile favors targeted, capability-driven investments—especially in specialists that can scale certification-led revenue or in companies that own advantaged supply positions for critical materials.
How to use the full PW Consulting market package
The complete report includes the granular models, regional and application-level breakdowns, supplier scorecards, and executable playbooks referenced here. It is designed so commercial, procurement, engineering and corporate development teams can run “what-if” scenarios tied to their specific product mixes and sourcing structures. The detailed segmentation tables and downloadable spreadsheets are intentionally retained in the full report to preserve the actionable value of the datasets.
Closing takeaway
In 2026 the multi-turn potentiometer market rewards technical excellence, supply-chain discipline, and commercial creativity more than scale alone. With the market base near USD 204 Million in 2025 and a steady 3.4% CAGR outlook to 2032, success will flow to players who 1) design for certification and serviceability, 2) hedge commodity exposure aggressively, and 3) structure go-to-market propositions around total cost of ownership rather than lowest unit cost. PW Consulting’s full market package translates these strategic imperatives into executable programs—contact our team to access the full dataset, supplier matrices, and scenario models that underpin this executive briefing.
For detailed analysis of this topic, please visit the official page: Multi Turn Potentiometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


