



PW Consulting Forecasts Biomass-for-Power Market to Surge to USD 178.02 Billion by 2032

Biomass for Power Generation Market: Strategic Insights for 2026 Decision-Making
Executive preview
PW Consulting’s latest market study on biomass for power generation synthesizes five years of historical performance (2020–2025) and delivers a forward-looking forecast through 2032. The market has expanded meaningfully since 2020, reaching an assessed global market size of USD 111.8 Billion in the report’s base year (2025). Our modelling indicates continued expansion across the forecast period, with the market projected to grow at a compound annual growth rate (CAGR) of 6.89% (2026–2032), reaching an estimated USD 178.02 Billion by 2032. For executives planning capital allocation, strategic partnerships, or regulatory engagement in 2026, these headline dynamics are a practical starting point — and this press release outlines the key strategic takeaways you should weigh before accessing the full report.
Biomass For Power Generation Market
Why this report matters in 2026
-
Actionable horizon: The study is calibrated to the 2026 decision cycle. It integrates recent project commissioning, supply‑chain developments, and policy shifts that are already altering project economics and permitting timelines.
Biomass For Power Generation Market -
Decision support: Rather than high-level commentary, the report provides investment-level lenses — project-level economics, scenario-based sensitivities, and CAPEX/OPEX benchmarks — to support go/no‑go choices and portfolio prioritisation.
Biomass For Power Generation Market -
Risk differentiation: With policy frameworks evolving rapidly in major markets, the report quantifies regulatory upside and downside scenarios so stakeholders can design hedge strategies for feedstock, carbon accounting, and incentive eligibility.
Market outlook — what the numbers signal
The sector’s growth trajectory is clear: after a post-2020 recovery and expansion phase, the industry is entering a multi‑year growth runway that is underpinned by utility-scale coal-to-biomass conversions, new build projects in emerging markets, and increased interest in distributed biomass CHP. The forecast CAGR of 6.89% over 2026–2032 reflects a combination of steady demand for dispatchable renewable electricity, greater policy support in several jurisdictions, and investment in supply‑chain infrastructure.
For corporate strategists, the headline phase of growth translates into expanding addressable markets for three distinct value pools: fuel supply and logistics, plant equipping and EPC services, and energy offtake and grid integration services. Each pool requires different margin and capital models — the full report breaks these down and models sensitivity to fuel price swings, capital cost inflation and differing policy outcomes.
Key dynamics shaping 2026 choices
-
Policy and incentive design: Recent regulatory developments have shifted the calculus for biomass investments. Technology‑neutral clean electricity credits and investment tax incentives tied to lifecycle greenhouse gas outcomes have created pathways for certain biomass projects to access parity with other low‑carbon options — provided developers can demonstrate credible lifecycle emissions accounting.
-
Carbon management: Legislative proposals to broaden carbon‑capture tax credits to support forest residue-based products and wildfire mitigation endpoints are increasing the optionality for integrated biomass projects that combine fuel management with carbon mitigation services. For project sponsors, pairing biomass generation with carbon removals is becoming a material component of long‑term value creation.
-
Feedstock economics and logistics: Supply‑chain resilience remains the single largest operational risk. While feedstock costs and market flows continue to vary regionally, our scenario models show that vertically integrated supply strategies, fuel diversification and upstream processing capacity (pelletising, densification) can materially reduce merchant price exposure and improve plant availability.
-
Project finance and offtake: Appropriations and public funding mechanisms signed into law in early 2026, alongside evolving merchant power dynamics, are widening financing options for creditworthy projects. However, financiers are increasingly demanding transparent carbon accounting and feedstock sustainability evidence as condition precedents to debt.
Competitive landscape — who’s shaping the market
The biomass value chain is populated by several distinct player types: large utilities retrofitting or operating biomass fleets, specialised fuel producers and pellet exporters, EPC and equipment suppliers, and regionally-focused developers. Leading utilities and energy companies are pursuing a twofold strategy: preserve dispatchable capacity by repurposing existing assets and build new capacity in markets with secure feedstock streams.
Representative players profiled in our study include major European and North American utilities that have converted coal units to biomass and maintain integrated wood pellet supply chains; global EPC and engineering firms supplying boilers and gasification systems; and specialised developers active in Asia-Pacific. Our company-by-company analysis evaluates strategic positioning, balance-sheet exposure to biomass, recent project pipelines, and technological focus — enabling investors to identify potential partners or acquisition targets.
Recent, strategically significant developments (covered in the report) include new commercial plant startups in Southeast Asia, grid connections of first-of-type projects in the Asia‑Pacific region, and additional processing capacity in key biomass fuel hubs. These moves are practical indications of where near-term operational scale and supply integration are being achieved.
Strategic implications for corporate decision‑makers in 2026
-
For utilities and IPPs: Prioritise asset-level lifecycle GHG verification and evaluate hybrid models (biomass-plus-carbon-capture or biomass-plus-waste-to-energy) to secure long-term offtake premiums and policy credits.
-
For fuel producers and traders: Invest in downstream processing capacity and logistics visibility to capture margin from densification and to supply long-term conversion projects; contracts that include indexation, quality clauses, and logistics guarantees will be critical.
-
For equipment vendors and EPCs: Differentiate through modular, lower‑emissions combustion and gasification solutions, and by offering performance guarantees tied to fuel variability and ash management.
-
For financial sponsors: Use the report’s scenario models to stress test leverage and term structures against feedstock shocks and policy reversals; green‑linked financing structures that reward verified lifecycle carbon performance are increasingly relevant.
What the PW Consulting report contains (practical deliverables)
-
Market sizing and forecasting model (base year 2025; historical 2020–2025; forecast 2026–2032) with downloadable Excel workbooks that allow users to run alternative scenarios on feedstock price, CAPEX trends and policy outcomes.
-
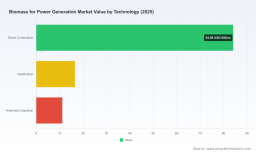
Segment-level diagnostic frameworks across fuel types and technology routes (combustion, gasification, anaerobic digestion) with practical checklists for plant conversion and new build evaluation.
-
Policy and incentives playbook mapping major jurisdictional programs, recent legislative proposals, and eligibility criteria for tax and production credits — emphasising pathways to monetise lifecycle emissions improvements.
-
Competitive intelligence dossiers on leading utilities, developers and equipment suppliers with capability matrices, partnership maps and M&A signals to guide corporate development teams.
-
Supply‑chain risk heatmaps and procurement strategies covering densification, co‑firing compatibility, logistics bottlenecks and seasonal availability.
-
Operational benchmarking: CAPEX/OPEX comparators, heat-rate ranges, fuel consumption profiles and availability metrics to support valuation and due diligence teams.
How to use the report in 90 days
-
Week 1–2: Validate your internal assumptions against the report’s base‑case model — focus on feedstock sourcing and lifecycle emissions inputs.
-
Week 3–6: Run customised scenario stress tests for target assets or projects using our downloadable workbooks — explore different policy and price outcomes.
-
Week 7–12: Engage targeted counterparties identified in the competitive dossiers and use the report’s negotiation playbooks to structure long‑term fuel and offtake agreements with sustainability covenants.
Final counsel — the strategic decision window
2026 will be a pivotal year for stakeholders in biomass power. The confluence of stronger policy attention on lifecycle emissions, nascent carbon‑removal linkages, and fresh capacity coming online in several geographies creates both opportunity and complexity. Our analysis shows the market is growing from an established base and entering a sustained expansion phase; however, outcomes will be highly path‑dependent on feedstock security, carbon accounting frameworks, and the structure of fiscal incentives.
PW Consulting’s Biomass for Power Generation Market report is designed as a decision‑grade instrument: it equips executives with the models, competitive intelligence, and pragmatic checklists needed to move from strategic intent to executable plans in 2026. For teams that require the full dataset, segment breakdowns, and downloadable modelling tools, the report and accompanying data packs are available on our website.
Next steps
Contact PW Consulting to schedule a briefing with our biomass practice lead and request a tailored extract of the forecast model for your asset or market of interest. Our advisory team can also run a short-form diligence workshop to translate the report’s insights into an actionable 12‑month roadmap for your organisation.
For detailed analysis of this topic, please visit the official page: Biomass For Power Generation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


