



PW Consulting Forecasts Satellite Control Services Market to Expand at a 7.45% CAGR Through 2032, Unlocking New Growth Opportunities

Satellite Control Service Market 2026: Strategic Imperative and Tactical Playbook — PW Consulting Industry Brief
Executive summary
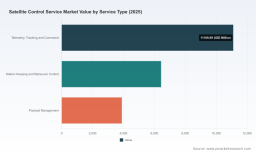
The Satellite Control Service market stands at a strategic inflection point. Our new market study, anchored on 2025 as the base year and projecting through 2032, demonstrates resilient expansion driven by multi-orbit operations, commoditization of ground infrastructure, and regulatory shifts that will reframe access to spectrum and market entry in 2026. PW Consulting’s models estimate the global market at USD 21,450 Million in 2025, growing at a 7.45% CAGR to reach roughly USD 35,470 Million by 2032. That trajectory creates a multi-year runway for incumbents and new entrants to capture recurring TT&C (Telemetry, Tracking & Command), station keeping, maneuver control and payload management revenues — provided they realign commercial models, manage capital intensity, and navigate an accelerating regulatory landscape.
Satellite Control Service Market
Why 2026 is a decision point
-
Regulatory windows opening. Multiple policy initiatives converging in late 2025 and early 2026 — including streamlined satellite licensing proposals, a bipartisan U.S. bill to standardize market access, and EU measures accelerating infrastructure approvals — create a narrow window for firms to secure spectrum rights, contest market positions, or lock in favorable licensing terms. Strategic timelines that were measured in years are now compressed into quarters.
Satellite Control Service Market -
CapEx vs. GSaaS economics. Ground-station deployment remains capital intensive. At the same time, the market’s financial logic is shifting: Ground-Station-as-a-Service (GSaaS) and managed operations models are material vehicles for growth and risk mitigation. Operators must decide whether to scale owned infrastructure or form cloud-like, networked partnerships that monetize antenna capacity and operations expertise.
Satellite Control Service Market -
Operational complexity and automation. The mass adoption of smallsat constellations and hybrid multi-orbit architectures increases TT&C transaction volumes and mission complexity. Automation, cloud-native mission control, and AI-driven anomaly detection are no longer optional for operators who want to maintain margins while scaling operations.
What PW Consulting’s report delivers (practical, actionable modules)
Our Satellite Control Service Market report is built for decision-makers planning capital allocations, M&A, product strategy, or procurement for 2026. The study synthesizes historical performance (2020–2025), a detailed forecasting model (2026–2032), and scenario analysis under alternative regulatory and technology adoption pathways. Key deliverables include:
-
Proprietary market-sizing model with base-case, upside and downside scenarios and sensitivity levers for spectrum policy, capex trends, and GSaaS adoption rates.
-
Vendor benchmarking and scorecards across capabilities: multi-orbit TT&C, managed operations, latency SLAs, security posture, and service continuity assurances.
-
Go-to-market playbooks for incumbent operators, ground-network specialists, systems integrators and cloud providers — including pricing buckets, partnership archetypes, and white-space opportunities.
-
Build-versus-buy TCO models and a procurement-ready RFP template for GSaaS and managed satellite control services.
-
Regulatory path matrices that map national licensing regimes, predicted approval timelines, and practical mitigation steps for spectrum and access risk.
-
M&A and alliance playbook with valuation heuristics, integration risks, and revenue-synergy scenarios tailored to satellite control assets.
Note: This announcement intentionally omits the granular regional and application split tables and proprietary financial line items included in the full report — these are available through PW Consulting’s data portal.
Competitive landscape: positions, capabilities, and strategic moves
The market’s top-tier concentration and the profile of active players shape competitive dynamics. Our concentration analysis indicates a moderately consolidated market: the top three firms account for a meaningful share of revenue concentration, and the top five further increase market hold. This structure creates room for specialized challengers and ground-network aggregators to capture niches while incumbents defend broad service portfolios.
-
Ground-network specialists and GSaaS aggregators: Firms with dense antenna networks and mission-adapted operations — exemplified by global ground-network providers — are leveraging geographic reach and multi-orbit experience to win managed TT&C contracts. Recent public network expansions demonstrate continued investment in physical footprint to support rising telemetry volumes and LEO revisit demands.
-
Large satellite operators and integrated service providers: Established satellite operators that combine fleet operations with integrated ground segments are playing a dual role: they are both customers for third-party GSaaS and competitors offering full lifecycle mission services. Their advantage lies in fleet-level optimization and lifecycle engineering capabilities.
-
Defense and systems integrators: Defence-focused suppliers and prime contractors offer hardened, secure command-and-control solutions and have a strong position in government and military segments where mission assurance and certification are primary procurement criteria.
-
Platform and software vendors: A rising cohort of software-first providers focus on mission control automation, telemetry analytics, and cloud-native control systems. Their marginal cost model for scaling mission control software makes them attractive partners for both operators and GSaaS providers seeking automation-driven efficiency.
Recent corporate actions underscore these dynamics: network expansions by ground-network specialists, contract renewals in managed connectivity for defense customers, operational updates from global operators, and gateway deployments tied to new constellations. These moves collectively underline an industry transitioning from siloed, capital-heavy stacks to hybrid models that mix asset ownership with service layers.
Key strategic implications for 2026 (how executives should act)
-
Lock in regulatory and spectrum positions now: With several regulatory initiatives slated to crystallize in early 2026, firms should prioritize regulatory engagement, scenario planning for license timelines, and legal strategies to protect cross-border operations.
-
Decide the infrastructure posture: Use a short-form TCO and sensitivity model to determine whether to expand owned ground assets or accelerate GSaaS partnerships. The right choice depends on latency needs, sovereign requirements, and the lifecycle revenue outlook of an operator’s fleet.
-
Invest in automation and secure software stacks: Scale cannot be achieved profitably without higher levels of automation in mission control and robust cybersecurity architectures for TT&C. Prioritize modular, cloud-friendly control systems and AI-enabled anomaly detection as immediate investment themes.
-
Pursue selective M&A and strategic alliances: Identify targets that fill capability gaps — e.g., ground-network density, software control platforms, or certified defense-grade operations — and favor bolt-on transactions where integration risk is manageable.
-
Differentiate through SLAs and mission assurance: Commercial customers will trade on predictable availability and rapid restoration. Firms that can credibly offer mission assurance commitments with verifiable SLAs will command premium pricing in managed services engagements.
Risk map and mitigation
Key risks include regulatory uncertainty, capital intensity of ground infrastructure, supply-chain constraints for RF and antenna components, and evolving cyber threats to TT&C pathways. Mitigation levers include diversified access strategies (hybrid owned + GSaaS), multi-sourcing of critical hardware, cyber-hardening programs, and insurance structures tied to service continuity. Our report contains a detailed risk-heatmap and mitigation-level scoring to prioritize where to deploy capital and market-facing resources in 2026.
How to use this brief and next steps
This release is intentionally a strategic preview: our goal is to surface the decision-critical themes that will define winners in 2026 while conserving the proprietary modelling and granular split data that clients rely on for execution. Executives preparing budgets, M&A targets, or procurement strategies should treat the findings here as directional and use the full PW Consulting report to execute precise sizing, vendor selection, and contract negotiation strategies.
-
For immediate planning: incorporate the 7.45% CAGR and our near-term forecasts into 2026 revenue scenarios, stress-testing assumptions on spectrum access and GSaaS adoption.
-
For procurement and partner selection: request PW Consulting’s vendor scorecards and RFP templates to compress supplier evaluation timelines.
-
For transactions: use our M&A playbook and valuation heuristics to align bids with realistic synergy capture and integration timelines.
To access the full dataset, granular regional and application splits, vendor-level revenue models and the operational playbooks referenced above, please visit the PW Consulting report page or contact our strategy team. The window to lock positions ahead of 2026 regulatory and commercial inflection points is short — informed, decisive action now will materially alter market share outcomes over the next seven years.
For detailed analysis of this topic, please visit the official page: Satellite Control Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


