



PW Consulting: Dolby Atmos Phone Market to More Than Double from USD 28.5 Billion in 2025 to USD 61.59 Billion by 2032 on 11.64% CAGRPW Consulting: Phased Array Coil Market Poised to Reach USD 1,270.79 Million by 2032, Backed by a 6.32% CAGRPW Consulting Report: cfDNA Testing Market to Reach USD 18,432.9 Million by 2032, Expanding at a 13.6% CAGR

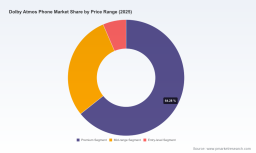
Dolby Atmos Phone Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
PW Consulting today publishes an in-depth market research brief — Dolby Atmos Phone Market — designed to equip senior strategy teams with the evidence and frameworks required to make high-consequence decisions in 2026. The study synthesizes historical performance, near-term inflection points, and a seven-year forecast horizon to show where Dolby Atmos-enabled smartphones will create commercial leverage for OEMs, platform partners, content owners, and component suppliers.
Dolby Atmos Phone Market
Executive snapshot: Why 2026 is a strategic inflection
-
Market momentum is unmistakable. The Dolby Atmos-enabled smartphone category more than doubled in size across the last half-decade, growing from approximately USD 16.5 billion in 2020 to USD 28.5 billion in 2025.
Dolby Atmos Phone Market -
Forward-looking growth is robust: our base-case model projects a compound annual growth rate (CAGR) of 11.64% over the 2026–2032 forecast window, with the market expected to exceed USD 60 billion by 2032.
Dolby Atmos Phone Market -
2026 is the year to translate audio feature parity into commercial differentiation. OEMs and ecosystem partners that move beyond checkbox integration toward differentiated hardware-software-content experiences will capture disproportionate value as adoption scales into mid-tier portfolios and new geographies.
What the report contains — practical, decision-ready intelligence
-
Market sizing and robust forecasting: transparent methodology, scenario modelling (base, upside, downside), and sensitivity tests to help translate macro assumptions into P&L impact.
-
Go-to-market playbooks: product segmentation by audio UX archetypes, route-to-market considerations for premium vs. mid-tier launches, and recommended launch timing relative to annual refresh cycles.
-
Commercial frameworks: licensing and revenue share models, co-marketing templates with Dolby and streaming partners, and pricing archetypes adapted to multiple channel strategies (direct, carrier, retail).
-
Engineering and product checklists: end-to-end hardware/software integration guidance, speaker configuration trade-offs (stereo placement, amplification, DSP tuning), certification pathways, and verification protocols to ensure consistent spatial audio quality.
-
Supplier and component mapping: strategic supplier segmentation, lead-time risk analysis, and cost-down levers for mass-market adoption without degrading experience.
-
Competitive and M&A playbook: assessment of incumbent OEM positioning, adjacencies ripe for consolidation (audio startups, low-latency streaming middleware, spatial-audio SDKs), and diligence checklists for bolt-on acquisitions.
-
Commercial KPIs and measurement templates: adoption metrics, feature engagement, bundling uplift, and LTV/ARPU modeling for monetization experiments tied to Dolby Atmos-enabled experiences.
Competitive landscape: what the OEM moves tell us
The competitive map is dominated by a mix of global flagships and aggressive regional players. Major incumbents have implemented Dolby Atmos differently — from system-level spatial audio implementations to device-specific tuned experiences — and recent product announcements in early 2026 underscore continuing commitment across the ecosystem.
-
Samsung has embedded Dolby Atmos broadly across its flagship Galaxy families and selected mid-range models, using speaker hardware and software tuning to make spatial audio a headline feature in launches.
-
Apple continues to support spatial audio across its iPhone line through integrated hardware-software optimization and a closely controlled accessory/eCosystem play that protects perceived quality.
-
Large Chinese OEMs (Xiaomi, OPPO/OnePlus/Realme, vivo, Huawei) are treating Dolby Atmos as a product capability that accelerates multimedia and mobile gaming differentiation, bringing more advanced audio experiences into aggressive price tiers in many markets.
-
Sony and Nokia persist as niche differentiators: Sony leverages its audio heritage to position Xperia models with cinema-grade tuning, while Nokia and other smaller OEMs selectively deploy Dolby Atmos to lift perceived value on model refreshes.
-
Motorola’s early-2026 launch of an ultra-slim Signature model with Dolby Atmos and partner-branded audio hardware signals an important product strategy: collaborate with specialist audio brands to deliver tangible experiential upgrades rather than marketing-only claims.
Across the competitive set, the takeaway is consistent: Dolby Atmos has shifted from a premium-only checkbox to a scalable feature leveraged for both product differentiation and volume growth. The strategic question for 2026 isn’t whether to support Dolby Atmos — it is how to design product, pricing, supply chain, and partner economics to extract commercial advantage from that support.
Dynamics shaping the next 12–24 months
-
Premiumization and feature bundling: Buyers continue to exhibit willingness to pay for richer multimedia experiences. Dolby Atmos can act as a demand amplifier when paired with display, camera, and gaming upgrades.
-
Streamers and gaming publishers as multipliers: Content owners expanding spatial audio catalogues create distinct use-cases that raise the marginal utility of in-device Atmos implementations.
-
Certification and licensing: Dolby’s licensing and certification programs reduce quality variability, but they also introduce negotiation levers (package scope, testing cycles, co-marketing commitments) that materially affect margins and go-to-market speed.
-
Geographic diffusion: The expectation that Dolby Atmos expands into mid-tier devices in emerging markets suggests that scale economics will increasingly matter. This changes supplier mix, testing regimes, and pricing models.
-
Concentration among supply and OEM partners: a handful of large OEMs and platform players will continue to define market norms; strategic partnerships with these players accelerate reach while creating competitive moats for differentiated device makers.
Actionable recommendations for 2026 corporate decision-makers
-
For OEM product leaders: Prioritize a tiered integration strategy — reserve highest-fidelity tuning and premium hardware for flagships while creating verified, repeatable integration templates for upper mid-tier devices. Map clear experiential deltas so marketing can credibly communicate value.
-
For commercial & partnerships teams: Negotiate licensing and co-marketing arrangements that align incentives across OEM, Dolby, and streaming partners. Test bundling pilots with major streaming services to assess incremental ARPU and retention effects.
-
For finance and M&A teams: Screen acquisition targets that provide proprietary spatial-audio processing, low-latency audio stacks for cloud gaming, or differentiated tuning tools. Prioritize targets with defensive IP and established integration methodologies.
-
For supply-chain and operations leaders: Lock down multi-sourced component pathways for speakers, amplifiers, and key DSP chips, and build accelerated validation tracks to shorten certification timelines without compromising audio quality.
-
For marketing and channel: Develop consumer education programs that translate spatial audio benefits into tangible use-cases (mobile gaming, streaming movies, voice clarity). Equip carrier and retail sales teams with simple demos and quantified uplift metrics.
Why this report matters for boardroom decisions in 2026
Strategic bets on audio capability today influence product roadmaps, supplier contracts, and content partnerships for years. With the Dolby Atmos phone market on a clear upward trajectory — supported by solid historical acceleration and an 11.64% CAGR in our forecast window — the choices companies make in 2026 will determine whether they are volume participants, margin-capturers, or relegated to feature parity.
Boards and C-suite teams will find the report valuable because it converts market growth projections into investment-grade guidance: recommended capex allocations for audio hardware, milestone-based commercial KPIs for partnership deals, and a prioritized action list for near-term EBITDA improvement tied to audio-led product differentiation.
Selective insights — and what you’ll only see in the full report
We deliberately present a high-level view in this release to demonstrate the strategic value of the full intelligence package. The complete report contains granular regional scenarios, channel-specific adoption curves, product-level profitability models, and an OEM supplier matrix — the detailed inputs that underpin the topline forecasts and the practical templates described above.
If your team is evaluating product roadmaps, licensing strategies, or M&A targets tied to spatial audio, the dataset and playbooks included in the full report provide the calibrated evidence required to run rigorous build vs. buy vs. partner analyses and to size expected return on investment under multiple commercial structures.
Next steps
-
Download the executive package to access our forecast model and scenario workbook.
-
Commission a tailored briefing from PW Consulting to map the implications for your product roadmaps, channel strategies, and partnership negotiations in 2026.
-
Engage our M&A team for a targeted screening of audio technology assets aligned to your strategic objectives.
PW Consulting’s Dolby Atmos Phone Market report is intended as the strategic trailer for decision-makers who need both the big-picture growth signal and the playbooks to act. For the full dataset, segmented analyses, and the complete set of operational templates referenced above, please visit our report page to access the comprehensive study and supporting models.
For detailed analysis of this topic, please visit the official page: Dolby Atmos Phone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


