



PW Consulting: High-Precision Copper Foil Market to Expand at 8.64% CAGR, Reaching USD 21,167.27 Million by 2032

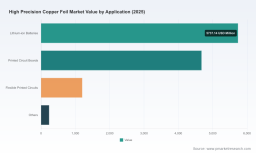
High Precision Copper Foil Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting today publishes an executive preview of our forthcoming in-depth market study on the High Precision Copper Foil market, designed to equip senior strategy teams with the intelligence required to make high-stakes decisions in 2026. This piece outlines the report’s analytical framework, summarizes key market trajectories, and flags the competitive and supply-side dynamics that will determine winners and losers through the 2026–2032 forecast horizon. Consider this a strategic trailer: we demonstrate analytical depth and actionable insights while holding back the detailed segment-level figures reserved for the full report.
High Precision Copper Foil Market
Executive snapshot: macro trajectory and strategic stakes
The high precision copper foil market emerges from 2025 on a renewed growth trajectory, underpinned by electrification, miniaturization of electronics, and demand for higher signal-integrity materials in advanced computing and communications. Our model, anchored on a 2025 base year and projecting through 2032, shows a robust compound annual growth rate (CAGR) of 8.64% across the forecast period. By 2026 the market is forecast to expand meaningfully from its 2025 base, and PW Consulting’s scenario set shows a clear upside path to the terminal year supported by technology adoption curves in consumer electronics, automotive electrification, and next-generation PCBs.
High Precision Copper Foil Market
Two observations are immediately pertinent to 2026 strategic planning: first, the market growth is sufficiently broad-based to justify capacity reallocation and selective investment in higher-value foil technologies; second, volatility in input costs and regional policy shifts make timing and supplier diversification a central part of procurement and capital allocation playbooks.
High Precision Copper Foil Market
What the full report delivers (practical, transaction-ready content)
- Proprietary model outputs with base-year calibration and stress-test scenarios for copper price shocks, capacity outages, and demand-side slowdowns.
- Decision matrices for procurement, pricing, and capacity investments mapped to 18 business cases (OEMs, laminate producers, battery makers, and PCB fabricators).
- Scenario-based ROI and NPV implications for capacity expansion vs. strategic offtake agreements under high and low raw material price regimes.
- Competitive playbooks for incumbents vs. challengers, including recommended strategic responses (JV, licensing, vertical integration, or niche specialization).
- Due diligence checklists and M&A valuation multiples tailored to different foil technologies (electrodeposited, rolled, and ultra-thin/high-frequency variants).
Drivers, friction points and 2026 decision levers
- End-market pull: Rapid adoption of lithium-ion battery architectures and high-density interconnects is elevating demand for ultra-thin and ultra-smooth copper foils. Procurement teams should treat foil quality and process yield as leading indicators of total system cost, not simply a raw-material line item.
- Input-price volatility: Copper cathode volatility in 2025 and early 2026 materially tightened manufacturing margins. Our scenarios quantify the pass-through elasticity and identify optimal hedging horizons for buyers and manufacturers.
- Capacity & timing: Recent capacity investments by several leading producers change the near-term supply balance. The timing of commissioned capacity, ramp-up efficiency, and location footprint will materially affect contract negotiations in 2026.
- Regulatory and sustainability constraints: Tightening environmental rules—particularly in jurisdictions pushing carbon neutrality—are reshaping cost structures and raising compliance investment needs for producers. Sustainability capabilities are fast becoming commercial differentiators.
Competitive landscape — who matters in 2026 and why
The market exhibits moderate concentration: the top-three players account for a meaningful chunk of supply while the top-five command an even larger share. This concentration profile creates asymmetric bargaining power that buyers and new entrants must account for in 2026 negotiations.
- Mitsui Mining & Smelting (Mitsui Kinzoku): A global leader in ultra-smooth MicroThin products and VSP™ technology. Recent actions—including capacity expansions and price adjustments—signal a dual focus on securing margin through pricing while vertically scaling capacity for high-end applications.
- JX Nippon Mining & Metals (JX Advanced Metals): Deep expertise in both electrodeposited and rolled foils positions this player to capture cross-sector demand where strict thickness control and high-frequency performance are required.
- Furukawa Electric: With a global footprint and disciplined tolerance manufacturing, Furukawa remains a go-to supplier for precision applications requiring consistent quality across geographies.
- Circuit Foil Luxembourg and other specialty European producers: These firms retain strength in very thin, high-spec foils where surface finish and micro-roughness metrics are non-negotiable for advanced PCB and RF applications.
- Regional challengers (selected Chinese, Korean, and Taiwanese producers): These firms compete on cost-competitive high-precision rolled and electrodeposited products and are increasingly active in energy storage and FPCB supply chains.
In short, 2026 will not be a winner-take-all race; instead, manufacturers will compete along differentiated axes—technology (e.g., ultra-low roughness and thickness control), scale (mass supply to battery and laminate sectors), and sustainability credentials. Buyers should expect targeted price moves and capacity-driven availability constraints to persist through much of 2026.
Recent market moves and implications for 2026 negotiations
- Price adjustments: Several leading suppliers announced significant price increases in late 2025 and early 2026. These moves reflect both input-cost pressure and strategic margin management. Buyers must reassess indexation clauses, hedging strategies, and long-term supply contracts in response.
- Capacity expansions: Announced expansions of proprietary ultra-smooth foil capacity by global incumbents will shift supply-side dynamics for specific premium product lines. The timing of these ramps affects spot availability and contract leverage for both OEMs and laminate producers.
- Product portfolio refreshes: Some producers updated product catalogs to emphasize tighter tolerances and thinner offerings for electronics and battery applications—an indicator of accelerating product-level competition rather than a race on commoditized volumes.
Supply-chain stress points: raw materials and regional exposure
High precision foil manufacturing is tightly coupled to copper cathode supply and refining economics. Despite elevated cathode prices earlier in 2026, smelter treatment and refining charges hit atypical low points—creating a paradox of upstream margin pressure and downstream raw-material cost spikes. Coupled with historically high operating-rate variability in major supply regions, these dynamics produce short lead-time volatility and localized shortages at times of peak demand.
For strategy teams, the practical implications are clear: diversify sourcing across technology types and geographies, build flexible contract terms that allow for rapid reallocation of supply, and evaluate on-site scrap recovery and material-efficiency projects to mitigate input-cost risk.
Regulatory & sustainability considerations
Public policy is reshaping production economics. Stringent carbon neutrality mandates in some producing countries are prompting investments in renewable energy integration, recycled-copper processing, and lower-emission process technologies. These investments have capex implications but create market advantages for suppliers that can credibly offer low-carbon foil streams to OEMs targeting greener supply chains.
Strategic recommendations for 2026 decision-makers
- Prioritize supplier segmentation: Assign suppliers to buckets (strategic, tactical, contingency) based on technology fit, sustainability credentials, and capacity visibility. Use PW Consulting’s supplier scorecard to operationalize this segmentation.
- Lock in critical offtake for premium foils: For applications where foil performance is system-critical (e.g., high-frequency interconnects, advanced batteries), prefer long-term offtake with fixed R&D collaboration terms over spot purchasing.
- Hedge intelligently: Combine physical inventory buffers with derivative hedges tailored to the timing of major capital projects and product launches.
- Consider asset-lite partnerships: For companies seeking exposure to advanced foil performance without heavy capex, structured licensing, tolling, or joint-venture models offer downside protection while preserving access to specialized technology.
What we deliberately withhold in this preview — and why
True to the “trailer” principle, we have shown the analytical approach and surfaced the strategic implications that will matter to executives in 2026. We have, however, withheld core subsegment revenue tables, granular regional and application splits, and product-level pricing curves that are critical for transaction execution and contract drafting. Those items are included in the full PW Consulting report and model package, which also contains sensitivity runs and supplier-level scorecards necessary for negotiation and M&A diligence.
Next steps — how PW Consulting supports your 2026 agenda
- Custom briefings: Schedule a tailored 90-minute executive briefing to align the report’s findings with your corporate strategy and procurement calendar.
- Scenario workshops: We offer facilitated scenario-planning sessions to stress-test capital allocation and procurement strategies against alternative raw-material and policy outcomes.
- M&A and procurement support: Access to our valuation models, supplier due diligence templates, and negotiation playbooks designed specifically for high-precision copper foil deals.
For purchasing the full High Precision Copper Foil Market report, accessing the proprietary model, or arranging a briefing, visit the PW Consulting insights portal. The full study contains the detailed segment-level data, supplier matrices, and actionable templates that procurement, strategy, and corporate development teams will need to convert 2026 uncertainty into competitive advantage.
For detailed analysis of this topic, please visit the official page: High Precision Copper Foil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


