



PW Consulting: P Series Glycol Ether Market Hits USD 4,950 Million in 2025; Set for 4.85% CAGR to 2032 as Asia Pacific Leads with USD 2,132.3 Million

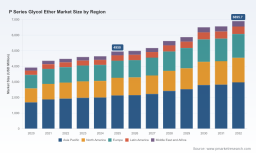
P Series Glycol Ether Market: Strategic Compass for 2026 — PW Consulting P Series Glycol Ether Market Report (Preview)
Executive Snapshot
PW Consulting's P Series Glycol Ether Market report (base year 2025; historical 2020–2025; forecast 2026–2032) delivers an actionable, decision-oriented playbook for chemicals executives, procurement leaders, and strategy teams planning for 2026 and beyond. The market is entering a structurally steady growth phase, with a compounded annual growth rate (CAGR) of 4.85% across the 2026–2032 forecast window. Measured in USD Million, the global market expanded from USD 3,920.0 Million in 2020 to USD 4,950.0 Million in 2025 and is forecast to reach USD 6,895.7 Million by 2032 under the baseline scenario. These headline metrics set the context for near-term tactical choices and medium-term capital allocation.
P Series Glycol Ether Market
Why this report is strategically material in 2026
2026 is where structural dynamics—feedstock volatility, regulatory tightening, and supply disruptions—converge with tactical choices about sourcing, capacity, and product mix. Our report translates macro trends into executable options that reduce downside risk and capture upside. Key drivers demanding immediate attention in 2026 include:
P Series Glycol Ether Market
- Feedstock and input-price volatility: Propylene oxide remains the principal upstream feedstock for P-series glycol ethers. Market intelligence shows meaningful price swings in early 2026 (North America pricing reached approximately USD 1.14/kg in March 2026, following month-to-month and quarter-to-quarter swings driven by downstream demand and propylene availability). Our models quantify the impact of these swings on margin and working capital under multiple pass-through and hedging strategies.
- Supply disruption risks: Recent operational events — including a force majeure declaration at a major Bayport facility in March 2026 following a fire, and contemporaneous price adjustments announced by leading producers — underscore the need for supply resilience and dynamic commercial terms.
- Regulatory trajectory: Emerging regulatory actions (such as proposed Significant New Use Rules under TSCA for glycol ether-related substances) are likely to increase compliance complexity and influence product acceptance in certain geographies and end-markets.
Report contents — practical, transaction-ready material
This report is designed as an operational toolkit, not just a narrative. It includes:
P Series Glycol Ether Market
- Market sizing and topline trajectory: annual market values (USD Million) for 2020–2025 and scenario-driven forecasts for 2026–2032 framed around a 4.85% baseline CAGR and two alternative demand paths.
- Supply-demand modeling: dynamic models that simulate the impacts of feedstock price shocks, capacity outages, and demand swings by end-use class and production pathway. Note: granular regional and application split tables are available in the full report to support contractual and capex decisions (this preview intentionally withholds the proprietary segmentation figures).
- Cost and margin sensitivity tools: embedded spreadsheets that map cost pass-through under common commercial terms (spot, short-term, long-term fixed). These tools let procurement teams stress-test supplier quotes against realistic PO and indexation clauses.
- Competitive landscape and strategic profiles: 15+ supplier dossiers (including capacity maps, specialty vs commodity positioning, and M&A posture), plus real-time monitoring of recent corporate actions and force majeure events to support supplier risk assessments.
- Commercial playbooks: negotiation checklists, recommended contract clauses for supply security, and procurement approaches tailored to different risk appetites (e.g., low-cost vs low-risk strategies).
- Regulatory and sustainability roadmap: impact assessment of likely regulatory measures, recommended compliance investments, and timelines for product reformulation where necessary.
Competitive landscape — what the report reveals (high-level)
The P-series market demonstrates moderate concentration: the top three players account for roughly 42.5% of market share (CR3), and the top five account for about 58.3% (CR5). That structure creates a mix of supplier power in commodity pockets and differentiated capabilities among specialty producers.
- Dow Inc. (USA) — Strengths: scale, high-purity product lines, broad application reach across coatings and cleaners, and extensive global production capacity. Strategic implication: Dow’s pricing actions in early 2026 signal the commercial leverage available to large, integrated suppliers when feedstock or logistics tighten. Buyers should prepare layered sourcing strategies and consider volume-commitment instruments with price collars.
- LyondellBasell Industries (Netherlands) — Strengths: integrated manufacture from propylene oxide, commodity and specialty grades. Risk: site-level operational incidents can create upstream shocks (the March 2026 force majeure at a Bayport facility materially tightened regional availability). Strategic implication: counterparties should maintain contingency capacity or pre-arranged cross-sourcing paths with geographically diverse producers.
- BASF SE (Germany) — Strengths: deep specialty portfolios spanning both E- and P-series glycol ethers, strong formulation support for coatings and cleaners. Strategic implication: premium, application-specific solutions remain resilient even when commodity segments face volatility.
- INEOS Oxide (UK), Eastman Chemical (USA), Shell Chemicals (UK), Huntsman (USA), KH Neochem (Japan), Chang Chun Group (Taiwan), Sasol (South Africa), Solventis (UK/Belgium) — Each of these players brings a distinct mix of regional footprint, specialty grades, and service propositions. The report assesses where each supplier fits along the tradeoff axes of price, lead time, and technical support.
Recent market signals and implications
- Price & supply moves (March 2026): Major sellers announced price increases for P-series products while a production site incident triggered force majeure at a large producer. These near-term actions increase the risk premium for spot purchases and motivate re-evaluation of safety stocks and contract terms.
- Feedstock volatility: Propylene oxide dynamics in late 2025 and early 2026 reveal sector sensitivity to upstream tightness and demand cycles. Procurement and treasury teams will need scenario-based hedging playbooks and collateral-light long-term contracts to stabilize landed costs.
- Regulatory watch: Proposals to expand regulatory scrutiny of glycol-ether related compounds introduce potential market access frictions. Companies that preemptively invest in data packages and toxicological dossiers will shorten time-to-market for reformulated products.
Recommended strategic moves for 2026
We convert insights into 6 practical actions executives can deploy this year:
- Stress-test supply chains against a “Bayport-style” outage scenario and establish pre-approved second sources mapped by rail/ship lane — prioritize suppliers with geographically complementary production.
- Lock in a portion of demand under indexed long-term contracts with price collars to balance cost predictability and upside sharing — use our model templates to quantify optimal hedge ratios.
- Segment product portfolios: accelerate migration to specialty, formulation-backed grades where margin resilience is higher; consider premium positioning for applications where regulatory or performance demands raise switching costs.
- Invest in traceability and regulatory dossiers now — prepare submission-ready data to reduce friction if SNURs or similar measures are finalized.
- Re-evaluate capex decisions through scenario-weighted NPV analysis rather than single-case forecasts — our included capex model provides sensitivity testing for five-year ROI horizons under alternate feedstock price regimes.
- Operationalize supplier risk scoring into the monthly procurement cadence to reflect real-time changes in force majeure events, price announcements, and inventory positions.
How PW Consulting supports your 2026 agenda
The full PW Consulting P Series Glycol Ether Market report couples macro forecasts with micro-level, executable tools: live Excel models, supplier due-diligence templates, a short-list of high-probability M&A targets, and contract clause libraries. Importantly, while this preview highlights the strategic themes and headline market sizing, the report’s proprietary segmentation tables, regional demand breakouts, and application-specific revenue curves are deliberately reserved for the full deliverable to preserve the utility of our proprietary analysis for subscribers and clients.
Next steps
For procurement teams, the immediate priority is to run the included price-impact and supply-disruption scenarios against current exposure. For strategy and corporate development teams, the report identifies corridors where bolt-on acquisitions and risk-sharing alliances generate asymmetric value. To access the full dataset, segment-level forecasts, and the operational toolset referenced in this preview, visit the report landing page or contact our industry practice for a tailored briefing.
For detailed analysis of this topic, please visit the official page: P Series Glycol Ether Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


