



PW Consulting: Liquid Phenolic Resin Market to Reach USD 10.44 Billion by 2032 at a 5.01% CAGR — Asia Pacific Leads with USD 3.52 Billion (2025)

Liquid Phenolic Resin Market Outlook 2026 — Strategic Imperatives for Decision‑Makers
PW Consulting presents a forward‑looking executive briefing built from our latest Liquid Phenolic Resin Market study (base year 2025, historical analysis 2020–2025, forecast 2026–2032). This briefing distills the market dynamics, competitive posture, and pragmatic playbook that senior executives, strategy teams, and investors will need to navigate 2026 as the industry transitions from cyclical recovery into structurally different demand and regulatory regimes.
Liquid Phenolic Resin Market
Headline market context
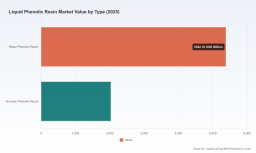
The liquid phenolic resin market has demonstrated steady expansion through the early 2020s and enters the 2026–2032 forecast window from a robust base. Our model (base year 2025) estimates the market at approximately USD 7,411.4 Million in 2025 and projects steady growth to roughly USD 8,173.0 Million in 2026 and around USD 10,435.5 Million by 2032 — an implied compound annual growth rate (CAGR) of roughly 5.01% across the forecast horizon. Market concentration metrics indicate a moderately consolidated competitive landscape (CR3 ≈ 32.5%; CR5 ≈ 41.8%), signalling both established scale players and room for strategic consolidation or niche specialization.
Liquid Phenolic Resin Market
Why 2026 is a strategic inflection point
- Feedstock volatility is rising: Phenol spot pricing has firmed in early 2026 (Northeast Asia spot levels in Q1 2026 were notably higher than late‑2025 benchmarks). That movement, paired with periodic upstream outages, may compress margins for producers that lack feedstock hedges or integrated upstream access.
- Regulatory tightening escalates product risk: New and evolving formaldehyde emission standards and stricter chemical limits in key jurisdictions are materially increasing compliance complexity and incremental production costs (our proprietary modelling shows single‑digit to low‑teens percentage impacts on manufacturing cost for legacy formulations).
- End‑market mix is shifting: Demand drivers such as construction recovery in select markets, lightweighting in automotive and growing insulation requirements are reshaping application mixes — creating higher growth pockets but also raising quality and certification demands.
- Trade and tariff disruptions: Recent reciprocal tariff actions and evolving trade policy create near‑term routing and sourcing risks that favor flexible regional supply footprints and localised contractual strategies.
What PW Consulting’s report delivers — the actionable toolkit
This study is constructed as an operator’s guide, not only as a market narrative. It includes:
Liquid Phenolic Resin Market
- Top‑down market sizing and trend decompositions (2020–2032) with sensitivity scenarios that isolate feedstock price, regulatory cost pass‑through, and demand elasticity.
- Proprietary pricing and margin model calibrated to segmental cost drivers and global trade flows, enabling scenario testing for contract negotiation and MRP planning.
- Supply‑chain topology maps showing supplier concentration, toll production options, and critical logistics chokepoints in strategic corridors.
- Regulatory impact analysis with compliance cost estimates and roadmap for low‑emission product reformulation and certification (including ISCC PLUS and other sustainability schemes).
- A competitive playbook: company benchmark matrices, capability heatmaps, and M&A screening criteria tuned to CR3/CR5 concentration dynamics and scale economics.
- Commercial levers and go‑to‑market templates for resin producers, formulators, and large downstream buyers (including hedging, indexation strategies, and tiered supply commitments).
To preserve the commercial value of the study, granular regional splits and detailed application‑level revenue tables are available exclusively in the full report.
Competition snapshot — what leading players are doing
The competitive landscape is a mix of large, integrated chemical manufacturers and specialised resin producers. Several strategic patterns are clear from public actions and primary interviews:
- Hexion Inc. — Global scale in resoles and broad downstream reach. Strengths: worldwide supply capability and portfolio breadth. Strategic implications: Hexion will likely prioritize supply reliability and integrated customer solutions to protect premium margins.
- Prefere Resins Holding GmbH — Europe‑focused specialist with multiple production sites. Strengths: regional manufacturing density and closeness to construction markets. Strategic implications: Prefere is positioned to capture demand for low‑emission and locally‑sourced products as EU regulatory pressure increases.
- Sumitomo Bakelite — Emphasis on sustainability credentials (notably ISCC PLUS certification) and advanced specialty grades. Strengths: certifications and premium industrial applications. Strategic implications: premiumization through certified and circular offerings will be a differentiator.
- BASF SE — Large‑scale integration and global reach afford feedstock and downstream synergies. Strengths: cost management and R&D leverage. Strategic implications: BASF can compete on total solution packages where multi‑chemistry integration is valued.
- DIC Corporation — Expanding capacity in Asia with focus on coatings and functional materials. Strengths: regional growth execution and technical formulations.
- Capital Resin Corporation — Niche, custom and toll manufacturing specialist with ISO 9001 credentials. Strengths: flexibility and close co‑development with customers. Strategic implications: toll manufacturing and co‑development contracts will be attractive to companies seeking de‑risked capacity without capital expenditure.
- Georgia‑Pacific Chemicals, Bakelite, Jinan Shengquan, SI Group — Each brings unique value propositions, from integration with wood products to regional mass production and specialty chemistry capabilities.
Collectively, public developments — including feedstock price movements and sustainability certifications — indicate incumbents will protect core customers via supply continuity, differentiation (low‑emission and certified products), and selective capacity investments. For mid‑sized and regional players, tolling, co‑development, and asset light strategies become viable defensive moves.
Key strategic choices for 2026 — practical recommendations
- Hedge and secure feedstock: Implement a blended procurement strategy combining short‑term spot exposure, medium‑term indexed contracts, and targeted forward hedges for phenol to stabilise margins under price swings.
- Prioritise low‑emission reformulation: Accelerate R&D and pilot commercialization of low‑formaldehyde liquid phenolic formulations. Map compliance cost to product pricing and embed certification pathways early in product pipelines.
- Rationalise footprint for tariff resilience: Reassess sourcing and routing in light of recent tariff actions; where economically justified, localise supply to key demand clusters or engage toll partners to avoid tariff penalties.
- Monetize sustainability: Fast‑track ISCC PLUS or equivalent certifications where customers value bio‑based or circular credentials; use certification to justify premium pricing and long‑term contracts.
- Use commercial contracts to share risk: Move toward hybrid pricing mechanisms (base price index + feedstock surcharge) and volume‑linked commitments to balance revenue predictability with market volatility.
- M&A and partnerships: For scale players, targeted bolt‑on acquisitions in adjacent geographies or specialty grades will compactly increase CR metrics; for smaller players, strategic partnerships and tolling agreements can preserve market access without heavy capex.
Operational playbook — a five‑step execution sequence
- Run the PW Consulting margin impact simulator to quantify feedstock and regulatory shocks against your cost base.
- Rank product SKUs by regulatory exposure and margin; designate priority SKUs for reformulation or certification.
- Negotiate multi‑year, indexed supply contracts with key customers that enable cost‑pass‑through and shared investment in reformulation.
- Deploy a hybrid sourcing map combining localised production, tolling partners, and strategic inventory buffers in tariff‑sensitive corridors.
- Define an M&A scorecard that values strategic fit, technology access, and regulatory compliance assets over pure revenue accretion.
Why this report is must‑read for 2026 decision cycles
As boards and CEOs set budgets and capital allocation plans for 2026, the Liquid Phenolic Resin Market report is designed to be directly actionable: it translates macro trends into line‑item impacts, provides negotiation‑ready commercial models, and supplies the competitive intelligence required to make high‑conviction choices on plant investments, product roadmaps, and transaction targets. The report balances strategic foresight with operational templates and contains proprietary scenario outputs that cannot be reconstructed from public sources alone.
PW Consulting adheres to the “trailer” principle — we have intentionally summarized the market architecture and strategic implications here while reserving the report’s granular regional and application‑level tables, supplier scorecards, and model spreadsheets for report subscribers and clients. Those deliverables enable deterministic planning (e.g., price pass‑through schedules, supply contingency plans, and SKU‑level reformulation cost curves) that procurement, product and M&A teams will use in 2026 negotiations and capital decisions.
Next steps
If you are preparing 2026 commercial plans, capital budgets, or M&A pipelines, engage PW Consulting for the full report and the accompanying modelling workshop. We will walk your cross‑functional team through scenario outputs, tailor the pricing/margin model to your cost structure, and validate an executable 12‑ to 36‑month action plan.
About PW Consulting: We are a strategy advisory firm focused on industrial chemicals and materials markets, delivering market research, commercial due diligence, and execution support to C‑suite clients, private equity sponsors, and industry investors.
For detailed analysis of this topic, please visit the official page: Liquid Phenolic Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


