



PW Consulting Forecast: Residential Solar Power Solutions to Expand at a 14.02% CAGR Through 2032

Residential Solar Power Solution Market: Strategic Imperatives for 2026
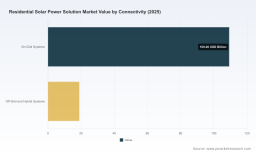
PW Consulting’s latest market study, Residential Solar Power Solution Market (base year 2025; forecast 2026–2032), synthesizes primary research, proprietary modeling and on-the-ground interviews to deliver a pragmatic playbook for corporate leaders planning 2026 actions. Our headline finding is unambiguous: the global residential solar market has moved from early-scale adoption to a structurally larger, more strategic industry. After growing from roughly USD 61.4 billion in 2020 to USD 128.19 billion in 2025, the market is projected to expand at a 14.02% CAGR through the forecast window and is expected to reach approximately USD 320.88 billion by 2032. 2026 stands as a critical year in which sourcing, product strategy, and policy responses will determine winners and losers over the rest of the decade.
Residential Solar Power Solution Market
Why 2026 Is A Strategic Inflection Point
-
Policy discontinuities and trade actions are changing the playing field. The termination of the U.S. Residential Clean Energy Credit (Section 25D) for systems placed in service after December 31, 2025 alters homeowner economics in the U.S. and shifts the incentive calculus for developers, financiers and manufacturers targeting North American demand.
Residential Solar Power Solution Market -
Trade enforcement and quotas are creating short-term supply distortions. Recent CBP quota and duty regimes on crystalline silicon products and preliminary antidumping determinations for imports from certain geographies introduce margin volatility and regional sourcing risk that require adaptive procurement strategies.
Residential Solar Power Solution Market -
Input-cost dynamics remain non-trivial. Polysilicon spot prices rose materially in early 2025; while raw-material cycles are familiar to the sector, the timing of price normalization and pass-through to downstream system pricing will affect product strategy and inventory decisions.
-
Installer economics and household-level affordability metrics are tightening. Publicly available benchmarking shows U.S. residential system pricing in H1 2025 operating in a mid-single-digit $/Wdc range; small absolute shifts in component cost or subsidy availability therefore have outsized effects on payback and financing product suitability.
What the PW Consulting Report Delivers
This study is designed as a decision-support toolkit for executives, investment committees, product teams and channel leaders. Key practical deliverables include:
-
Robust market sizing and top-down forecasts with sensitivity scenarios—illustrating baseline, upside and downside trajectories through 2032 and the implications of policy and commodity shocks.
-
Supply-chain heatmaps and vulnerability analysis—identifying concentration points across ingot-to-system layers, and offering mitigation playbooks (dual sourcing, nearshoring, contractual hedges).
-
Commercial models for rooftop deployments—downloadable models for LCOE, payback, tariff-sensitive IRR and consumer financing constructs that can be adapted to local pricing and incentive regimes.
-
Competitive vendor profiles and procurement scorecards—benchmarks on manufacturing footprint, technology differentiation, vertical integration and channel strategy (note: granular segment-level market shares and region-by-region revenue splits are summarized in the full report).
-
Operational playbooks for installers and distributors—standardized cost templates, workforce planning scenarios, and digital adoption frameworks for sales, permitting and asset management.
-
M&A and partnership diagnostic—valuation drivers for asset and platform deals, integration risk checklists and prioritization criteria for technology partnerships (e.g., storage + EMS).
-
Regulatory and tariff tracker—rolling timeline of major actions, anticipated policy windows and decision points for 2026 capital planning.
Competitive Landscape: Reading the Field in 2026
The industry shows a mix of consolidation and product-level competition. Top-tier module manufacturers continue to invest in high-efficiency monocrystalline technologies and vertical integration from wafers to modules. At the same time, power electronics and energy management providers are tightening the value chain by offering integrated solar+storage systems with software-enabled energy services.
-
Large module players are competing on scale, margin control and technological steps such as N-type architectures and bifacial designs. Their global shipment capacity and distribution networks remain core competitive levers for rooftop supply.
-
Inverters and balance-of-system innovators are differentiating via optimization technologies—microinverters and module-level power electronics are increasingly paired with storage to offer superior performance in complex roof topologies and behind-the-meter use cases.
-
Storage and integrated-solution vendors are pushing downstream: bundled propositions that simplify installation and O&M, and that provide home energy management capabilities, are gaining traction with homeowner segments focused on resilience and bill hedging.
-
Market concentration metrics indicate a moderate level of concentration among leading suppliers, while independent rankings show the top manufacturers controlling a sizable share of global shipments—this dual reality favors large-scale producers but leaves niches for differentiated, higher-margin products.
For corporate strategists, the competitive interpretation is clear: scale and vertical integration remain defensive advantages, but product differentiation (efficiency, integrated storage, software) and channel excellence can create sustainable premium positions.
2026 Strategic Playbook: Five Priority Moves
-
Hedge procurement and secure optionality. Lock in multi-origin supply contracts and modular inventory strategies to weather tariff windows and input-cost volatility.
-
Prioritize integrated solutions for homeowner segments valuing resilience. Upsell pathways combining PV, storage and energy management increase average deal size and reduce cost-to-serve over the customer lifecycle.
-
Reassess go-to-market economics in incentive-dependent markets. Build alternative consumer financing solutions and tailor product bundles for post-incentive scenarios where tax credits are reduced or removed.
-
Invest in installer enablement and digital workflows. A smaller installed-cost window depends on permitting automation, workforce certification and remote commissioning capabilities.
-
Execute targeted M&A or JV plays to close capability gaps—whether in storage chemistry, EMS software, or regional distribution—and ensure rigorous integration plans to capture synergies.
Scenario Briefs: How Outcomes Could Diverge
-
High-adoption scenario: rapid cost declines and supportive policy in major markets accelerate homeowner uptake, favoring vertically integrated suppliers who can scale production economically.
-
Protectionist scenario: prolonged trade measures and antidumping actions fragment supply chains and reset regional sourcing priorities—this benefits suppliers with diversified, localized manufacturing.
-
Stagnation scenario: policy pullback or prolonged commodity inflation compresses margins and slows installer growth, rewarding companies with strong financing platforms and aftermarket revenue models.
How to Use This Report in 2026 Decision Cycles
PW Consulting’s report is built for immediate use in boardrooms and strategy sessions. It includes dashboards and downloadable models designed for 2026 budget cycles: supplier risk matrices that plug into procurement frameworks, channel profitability templates for sales leadership, and investment case bundles for corporate development teams. Executive summaries and sector briefings are optimized for rapid assimilation; appendices house the detailed assumptions and primary-data citations necessary for compliance and audit.
We deliberately structure the public summary to convey directionality and strategic options while reserving the full suite of granular regional splits, segment-by-segment revenue forecasts and unit-level economics for licensed report holders. This approach protects actionable intelligence and ensures clients who need depth can operationalize recommendations without ambiguity.
Conclusion
The residential solar market is entering a phase where macro growth meets micro complexity. With the global market roughly doubling over the last five years and projected to more than double again by the end of the decade under our baseline, the opportunity is substantial—but so are the execution risks. For firms deciding 2026 capital allocation, go-to-market moves or M&A targets, the imperative is to combine supply resilience, product differentiation and channel efficiency. PW Consulting’s Residential Solar Power Solution Market report equips leaders with the forward-looking evidence and tools to act decisively. For the complete data, scenario models and supplier scorecards that underlie these conclusions, access the full report and interactive resources on our website.
For detailed analysis of this topic, please visit the official page: Residential Solar Power Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


