



PW Consulting: 24‑Hour Emergency Roadside Assistance Market Poised for Steady Expansion with 5.12% CAGR, New 2026–2032 Forecast Reveals

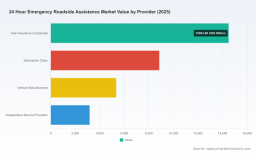
24 Hour Emergency Roadside Assistance Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
PW Consulting's latest 24 Hour Emergency Roadside Assistance Market study delivers a focused playbook for leadership teams making critical investment, partnership and operational decisions in 2026. Built on a comprehensive historical series (2020–2025) and a detailed forecast window (2026–2032), the report synthesizes market-size trajectories, competitive positioning, regulatory inflection points and executable go-to-market options that materially affect near- and medium-term returns.
24 Hour Emergency Roadside Assistance Market
Executive snapshot
The market is expanding steadily. Our base-year assessment (2025) values the global 24-hour emergency roadside assistance market at roughly USD 31.9 billion and projects that it will reach just over USD 45.2 billion by 2032 — reflecting a compound annual growth rate (CAGR) of 5.12% across the forecast horizon. This trajectory reflects a mix of persistent core-service demand (towing, battery and tire interventions, lockouts and fuel services), plus incremental growth drivers tied to fleet telematics, OEM bundled service programs and technology-led dispatch efficiencies.
24 Hour Emergency Roadside Assistance Market
Why this report matters for 2026 decision-making
- Actionable foresight: The combination of near-term market sizing and scenario-tested forecasts enables boards and commercial teams to stress-test capex and outsourcing decisions against plausible demand and cost environments in 2026–2028.
- Regulatory and operational risk mapping: We identify jurisdictional regulatory shifts that will change unit economics (notably for EV incident handling and vehicle storage), enabling pre-emptive contract and pricing redesigns.
- Competitive posture diagnostics: The study benchmarks incumbent strengths — from membership models to white-label OEM platforms and AI-driven on-demand providers — allowing executive teams to calibrate M&A, JV and partner-selection strategies without overpaying for redundant capabilities.
What the report contains (practical, executable deliverables)
- Clear market sizing and trend narratives for 2020–2025 with modelled forecasts through 2032, plus sensitivity scenarios under alternative EV adoption and macro-inflation assumptions.
- Provider capability maps, technology maturity assessments and a vendor short-list framework that ranks suppliers on operational coverage, SLA performance, telematics integration and claims integration readiness.
- Commercial playbooks for insurers, OEMs and fleet operators that translate forecast implications into pricing levers, bundling options and contract language templates to protect margins and uptime KPIs.
- Regulatory compliance checklists and a priority matrix for jurisdictions where near-term rule changes will affect storage, salvage handling and liability — including modeled P&L impact ranges for likely policy outcomes.
- An M&A and partnership decision tree that identifies where bolt-on consolidation, white-label partnerships or regional network investments will produce the highest IRR in a 24–36 month horizon.
- Operational templates for scaling patrols, training programs for EV incident response, and technology roadmaps for upgrading dispatch and ETA communications.
Competitive landscape — who matters and why
The market exhibits moderate concentration: the leading three providers account for a meaningful share of demand, while the top five capture a clear majority of market revenue — a structure that creates room for both regional specialists and national-scale integrators to capture value. Key provider archetypes we analyze include legacy motor clubs with deep membership economics, insurer add-on programs, OEM-partnered white-label providers, independent on-demand operators and digital disruptors focused on intelligent dispatch.
24 Hour Emergency Roadside Assistance Market
- Legacy membership clubs (e.g., AAA, ADAC, RAC, AA): These organizations leverage trusted brand equity, broad patrol networks and multi-decade operating experience to retain high-margin members. Their strength lies in retention economics and scale logistics.
- White-label integrators (e.g., Agero): These firms deliver platform-based dispatch, claims integration and OEM-grade SLAs. Their commercial value is in bundling services for insurers and manufacturers, enabling rapid market entry without capex-heavy network builds.
- Insurance and OEM programs (Allianz Partners, OEM-linked arrangements): These models tie roadside as a service into product warranties and policy suites, deepening customer lifetime value while shifting operational risk to service partners.
- Digital-first on-demand players (e.g., Urgently): AI-enabled dispatch and marketplace models are compressing response times and enabling margin improvements through dynamic pricing and improved asset utilization.
- Regional specialists and network operators (Falck, ARC Europe, Viking Assistance, SOS): These providers are critical for cross-border continuity and local regulatory navigation.
Our competitive chapter includes company-level capability matrices, partner-fit scoring and a scenario analysis of how recent moves — such as extended OEM contracts, platform consolidations and organizational integrations — alter competitive advantage into 2026.
Recent market developments to watch
- Major OEM and insurer partnerships have continued to proliferate, with multi-market agreements extending standardized roadside offerings across additional countries — accelerating the trend toward harmonized, cross-border service levels.
- Integration of fleet service teams under larger corporate umbrellas is consolidating capability and creating one-stop-shop offerings for larger fleet customers, enabling scale benefits but also increasing competitive pressure on independent operators.
- Digital providers are securing placements with dealerships and fleet managers on the strength of AI-enabled dispatch and real-time ETA improvements, forcing incumbents to elevate their technology investments to defend retention.
Regulatory and operational dynamics shaping 2026
Regulation and localized operational rules are among the highest-impact uncertainties in our analysis. Three trends demand immediate executive attention:
- EV incident handling and storage rules: Emerging statutes in some jurisdictions (for example, mandates on safe storage and separation requirements for damaged electric vehicles) change the cost profile of accident handling and salvage — influencing tow-provider reimbursement, storage fees and liability allocations.
- Regulatory gaps in vendor oversight: At least one U.S. state lacks distinct regulation for roadside assistance providers, creating material risks around vetting, training and equipment standards when insurers or apps contract third-party operators. This gap creates liability exposure that boards should model into contract terms and insurance costs.
- Operational variability in roadside vehicle safety practices: Inconsistent rules for warning lights and roadside vehicle operations across states/countries raise operational complexity and compliance costs for firms operating across multiple jurisdictions.
Operational demand patterns are also shifting: non-traditional call types — from pothole-related breakdown surges to EV-related service requests (which currently remain a small share of overall volume) — are changing the skill mix and equipment requirements of patrol fleets. Our field surveys and operator interviews document doubled pothole-related attendances in a recent quarter for a major patrol operator, an indicator of how infrastructure and seasonal patterns create episodic cost and demand spikes.
Strategic implications for leaders in 2026
Executives should treat 2026 as a decision window where investments or strategic shifts will determine who benefits from the projected 5.12% CAGR over the coming decade. Key implications include:
- Re-price and re-contract for EV economics: Expect higher direct handling costs and potential new storage fees to be passed through or contracted differently; update contract templates and SLA definitions now to avoid margin erosion.
- Prioritize telematics and AI-enabled dispatch: Improved ETA accuracy and dynamic resource allocation produce measurable margin improvements and customer satisfaction gains; early adopters will raise the bar for service-level expectations.
- Use regulatory engagement as a competitive moat: Firms that invest in compliance, participate in standard-setting and build demonstrable training and equipment protocols will secure larger insurer and OEM contracts.
- Evaluate consolidation selectively: With the market's moderate concentration, targeted acquisitions or strategic alliances that add geographic coverage, specialized EV-capable assets or proprietary dispatch technology offer attractive IRRs versus greenfield expansion.
- Redesign pricing and bundling: Work with actuarial and claims teams to design roadside bundles that mitigate predictability risks while capturing higher lifetime value through OEM and membership tie-ins.
Recommended near-term actions (90–365 days)
- Audit current roadside contracts for EV incident clauses, storage liabilities and pass-through fee triggers; insert contingency pricing where absent.
- Run a technology gap assessment focused on dispatch latency, ETA accuracy and telematics integration; prioritize quick wins with measurable cost-to-serve reductions.
- Perform a targeted provider due-diligence sweep in regions where regulatory gaps or new storage rules are emerging; tighten vetting and insurance requirements accordingly.
- Open exploratory dialogues with white-label integrators and digital dispatch providers to test pilot integrations for fleet and dealer channels.
Medium-term choices (12–36 months)
- Decide on build vs. buy for EV-capable roadside assets informed by a break-even analysis tied to regional EV penetration scenarios.
- Pursue one strategic M&A or JV to extend coverage or acquire differentiated technology if internal capability gaps exceed acceptable time-to-market thresholds.
- Develop a regulatory advocacy plan to harmonize safety standards for roadside operations and vehicle storage in high-risk jurisdictions.
Conclusion — the strategic value of this report
For boards, commercial leaders and operations executives, PW Consulting's 24 Hour Emergency Roadside Assistance Market report converts macro growth projections and fragmented competitive dynamics into a clear set of prioritized actions for 2026. With the market expected to grow from roughly USD 31.9 billion in 2025 to USD 45.2 billion by 2032 at a 5.12% CAGR, the opportunity is substantial — but timing, regulatory readiness and technology choices will determine who captures disproportionate value.
To preserve the report's utility as a strategic decision tool, we present this brief as an executive trailer: it surfaces essential insights and strategic recommendations while reserving the full regional, service-type and provider-level segmentation tables, detailed financial models and the complete methodology for the full study. For the complete dataset, downloadable models, company scorecards and procurement templates, please visit the official PW Consulting report page.
For detailed analysis of this topic, please visit the official page: 24 Hour Emergency Roadside Assistance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


