



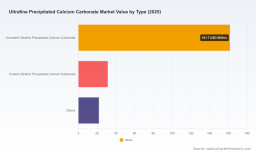
PW Consulting: Ultra-Fine PCC Market to Rise from USD 215.0 Million in 2025 to USD 344.8 Million by 2032 at a 6.98% CAGR, Led by Plastics (USD 178.4M)

Ultra Fine Precipitated Calcium Carbonate (PCC) Market — Strategic Outlook for 2026: What Corporate Decision‑Makers Need to Know
As companies finalize strategic plans for the 2026 fiscal year, PW Consulting presents a targeted briefing derived from our Ultra Fine Precipitated Calcium Carbonate (PCC) Market study (base year 2025, historical 2020–2025, forecast 2026–2032). This briefing synthesizes high‑probability scenarios, regulatory and supply‑chain stress tests, and competitor activity that materially affect near‑term choices in procurement, product development, capital allocation, and commercial positioning.
Ultra Fine Precipitated Calcium Carbonate Pcc Market
Market trajectory in one glance
The ultra fine PCC market has demonstrated steady expansion through the 2020–2025 period and is projected to continue growing across our 2026–2032 forecast window at a compound annual growth rate of 6.98%. Our full model quantifies a clear growth arc from the 2020 baseline across the historical years, through a 2025 reference year and into a range of strategic outcomes through 2032. These topline dynamics provide the foundation for scenario planning: as demand intensity increases and specifications tighten, suppliers and end‑users face converging pressures on cost, compliance and technical performance.
Ultra Fine Precipitated Calcium Carbonate Pcc Market
Why this matters for 2026 decision cycles
-
Budgeting and capital expenditure: the predictable CAGR and the transition from the 2025 base year enable CFOs to stress‑test capacity expansion, retrofit and automation projects against robust demand scenarios.
Ultra Fine Precipitated Calcium Carbonate Pcc Market -
Procurement strategy: raw material price volatility and regional regulatory actions call for differentiated sourcing strategies — from hedging and long‑term supply agreements to near‑shoring and strategic inventory buffers.
-
Product roadmaps: formulation teams must reconcile higher performance requirements (e.g., particle size control, surface treatment) with tighter compliance regimes and cost constraints.
Key structural forces shaping the market
-
Raw material and input cost volatility — The industry is feeling the effects of commodity tightness and regional cost pressure. Notably, calcium carbonate price indices have spiked in some markets recently (for example, a month‑on‑month increase was recorded in North America in May 2026), underscoring the need for procurement agility and supplier diversification.
-
Regulatory tightening — Between 2020 and 2025, regulators in major markets have enacted stricter chemical safety and emission controls. The EU’s enhanced chemical safety assessments under REACH and North America’s updated occupational exposure limits for airborne particulates have raised compliance thresholds for both production and downstream users.
-
Environmental and permitting constraints — Mining‑linked environmental regulations (dust control, water discharge limits) are increasing production cost floors in mature jurisdictions and restricting capacity expansion, which alters the balance of supply and creates opportunities for competitive entrants in less constrained regions.
-
Geopolitical and trade noise — Exchange rate swings and tariff uncertainty remain non‑trivial contributors to delivered cost volatility, affecting regional competitiveness and long‑term sourcing decisions.
Commercial and technical implications for manufacturers and buyers
Manufacturers must reconfigure priorities across three dimensions: product quality, cost competitiveness, and regulatory resilience. For buyers, the primary imperatives are supplier performance risk management and product specification optimization to maintain margins without sacrificing end‑product functionality.
-
Quality differentiation: performance gains increasingly come from tight control of particle characteristics and surface chemistry; suppliers investing in advanced milling, surface treatment and inline analytics will secure premium positions.
-
Cost containment: with input prices subject to periodic spikes and environmental compliance increasing unit costs, cost‑to‑serve analyses and lean manufacturing playbooks will determine who can compete on price without eroding returns.
-
Regulatory footprint: firms that preemptively align production processes with evolving exposure limits and chemical safety standards will face lower interruption risk and faster approval timelines for new SKUs.
Competitive landscape — what to watch
The market remains moderately unconsolidated with a low to mid single‑digit concentration among the largest players; our concentration metrics indicate a relatively open field (CR3 and CR5 values reflect modest aggregation). This structure is fertile for specialized players to capture niche value through product innovation, technical service and customer intimacy.
-
Established European and Asian producers continue to prioritize R&D to push ultrafine particle control and surface modification capabilities. Their investments are oriented toward higher‑value specialty grades that command resilience against commoditization.
-
Emerging suppliers from India and China emphasize cost efficiency and regional servicing advantages. Recent product launches and SKU extensions from regional players signal an active race to capture formulation‑specific opportunities (for example, new ultrafine grades targeted at sealants and high‑performance polymer systems were introduced late in 2025).
-
Service differentiation (technical application support, co‑development, and regulatory assistance) is becoming a primary competitive lever — suppliers who combine materials expertise with formulation‑level troubleshooting are winning strategic partnerships with downstream OEMs.
Selected company signals (illustrative)
-
Specialized European producers maintain a technology‑first posture, focusing on ultra‑fine grade performance optimization and high‑spec industrial applications.
-
Indian and Chinese firms are executing aggressive product portfolio expansions and cost competitive positioning; one such firm launched a purpose‑built ultrafine PCC grade in late 2025 targeted at sealants and reinforced polymer systems, reflecting a broader move into application‑specific SKUs.
-
Across the board, companies are investing in regulatory compliance, digital process control and near‑customer technical support to protect margins and secure long‑term contracts.
What our report delivers (practical, operational, and strategic content)
The full PW Consulting study is designed for immediate use by executive teams, procurement officers, and R&D leads. It includes:
-
Comprehensive topline modeling — historical 2020–2025 actuals, a 2025 base year, and scenario‑based forecasts through 2032 with sensitivities to key variables (commodity price shocks, regulatory tightening, and capacity shifts).
-
Actionable playbooks — supplier segmentation frameworks, procurement hedging templates, and manufacturing improvement roadmaps tailored to different company archetypes (integrated producers, toll processors, and formulators).
-
Competitive dossiers — strategic profiles of the leading market participants with capability maps, go‑to‑market tactics, and potential acquisition targets that meet specific technical or geographic criteria.
-
Regulatory impact assessment — an easy‑to‑use compliance matrix that translates EU, North American and regional regulatory changes into operational tasks, cost estimates and timeline impacts.
-
Commercial tools — price‑to‑cost models, customer profitability calculators, and SKU rationalization templates to prioritize product investments and margin recovery initiatives.
-
Supply‑chain stress tests — scenario simulations that quantify inventory strategies, dual‑sourcing benefits and near‑shoring tradeoffs under tariff, FX and transportation disruption assumptions.
Five prioritized strategic actions for 2026
-
Lock in diversified supply agreements with embedded flexibility — pursue a hybrid of long‑term contracts for core volumes and option‑style purchases to capture upside from price corrections.
-
Invest selectively in performance grades — channel R&D spend to formulations that reduce downstream processing costs or enable premium pricing, supported by co‑development agreements with strategic customers.
-
Operationalize regulatory foresight — convert the compliance matrix into a 12‑ to 24‑month implementation plan (monitoring, engineering controls, documentation and training) to de‑risk plant operations and tender responses.
-
Prioritize supply‑chain resilience — run the PW Consulting stress tester to quantify inventory and dual‑sourcing tradeoffs; reallocate working capital to where it buys the highest continuity value per dollar.
-
Pursue bolt‑on M&A selectively — target acquisitions that fill technical gaps (surface treatment, narrow particle distribution control) or add high‑value application penetration rather than chasing volume alone.
How PW Consulting supports execution
Beyond the market report, our advisory engagements deliver hands‑on implementation support: supplier negotiations, technology due diligence, regulatory roadmapping, and integration planning for acquisitions. We align commercial priorities with technical feasibility and supply‑chain realities, delivering executable milestones for 6, 12 and 24 months.
Concluding guidance and next steps
The 2026 planning horizon rewards firms that pair data‑driven scenario planning with decisive operational moves. The combination of steady market growth, regulatory tightening and input cost volatility creates both risk and opportunity: risk for undifferentiated players operating on thin margins, and opportunity for firms that can translate technical differentiation and supply resilience into premium placement.
For procurement leads, the actionable priority is immediate vulnerability assessment and contract re‑engineering. For R&D and product leaders, the homework is to accelerate co‑development with strategic customers and defend margins through value‑added formulations. For the C‑suite, the imperative is clear: convert the growth trajectory and concentration dynamics into disciplined capital allocation that favors capabilities over scale‑for‑scale’s‑sake.
PW Consulting’s Ultra Fine PCC Market study includes the full datasets, granular regional and application splits, and downloadable tools referenced in this briefing. To access the detailed segmentation, company profiles, and the interactive scenario model, please visit our report page for the authoritative inputs and subscription options.
For detailed analysis of this topic, please visit the official page: Ultra Fine Precipitated Calcium Carbonate Pcc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


