



PW Consulting Predicts Short‑Range Air Defense Market to Expand at a 6.38% CAGR During 2026–2032

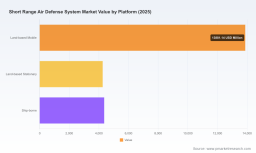
Short Range Air Defense System Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As geopolitical tensions evolve and unmanned aerial systems proliferate across conflict zones and contested airspaces, short range air defense (SHORAD) is moving from niche battlefield capability to core force-protection architecture. PW Consulting’s latest Short Range Air Defense System Market Research report provides a forward-looking intelligence layer designed for executives who must decide, procure, or invest in SHORAD capabilities in 2026 and beyond. This preview highlights the report’s strategic value without disclosing the granular segment tables reserved for subscribers.
Short Range Air Defense System Market Research
Macro snapshot: growth and strategic momentum
The SHORAD market is on a clear, sustained upward trajectory. From an estimated USD 16,420.5 Million in 2020, the market expanded through the mid-2020s to about USD 22,500.0 Million in 2025. Our forecast points to continued expansion across the 2026–2032 period at a compound annual growth rate (CAGR) of 6.38%, reaching an overall market size in the neighborhood of USD 34,689.9 Million by 2032. These macro dynamics are driven by accelerated procurement cycles, modernization programs among allied militaries, and rapid technology maturation in sensors, interceptors, and integration architectures.
Short Range Air Defense System Market Research
Why this matters for 2026 decision-makers
- Budget prioritization and program timing: The mid-2020s represent a narrow window for influence—capability roadmaps and production ramp decisions made in 2026 will determine industrial share and interoperability options for the next decade. Our modelling shows that suppliers who secure early production-rate agreements and modular integration work will capture outsized value as demand scales.
- Supplier selection and risk management: Procurement teams must balance advanced missile and sensor performance with industrial risk: production capacity, export-control exposure, and supplier concentration. The market concentration profile indicates a cluster of incumbent primes controlling a meaningful share of supply, with a broader set of niche technology specialists forming the rest of the ecosystem.
- Investment and M&A timing: Private equity and strategic corporate development teams will face choices between buying into scale via platform integrators or investing in high-margin components (interceptors, seekers, C2 software). Our scenario analysis reveals optimal entry points aligned with key program milestones and test campaigns expected in 2026–2028.
- Supply chain resilience: High R&D and production costs—driven by sophisticated missile motors, seekers, and high-performance radars—mean per-vehicle systems for contemporary mobile SHORAD configurations fall into a multi-million-dollar class. For procurement authorities, lifecycle affordability planning (including munitions throughput and training costs) is now as important as unit acquisition price.
What PW Consulting’s report delivers — practical, actionable intelligence
Our full report is structured as an operational playbook for executives, program managers, and investors. Key deliverables include:
Short Range Air Defense System Market Research
- Executive decision map: A matrix linking strategic objectives (e.g., area denial, maneuver protection, critical-site defense) to optimal architecture choices, procurement timelines, and risk mitigations.
- Production and demand scenario models: Probabilistic demand curves keyed to defense budgets, large-scale procurement programs, and surge-production frameworks from leading governments.
- Supplier and component risk heatmaps: Comparative scoring across manufacturing scale, export-control exposure, technology depth, and integration risk—enabling defensible single-source vs. multi-supplier decisions.
- Integration playbooks: Tactical guidance for integrating interceptors, cannons, sensors, and C2 nodes into layered defences, including recommended data-interfaces, testing regimens, and incremental upgrade pathways.
- Commercial intelligence for investors: Valuation anchors, likely consolidation vectors, and shortlist of high-conviction targets for strategic and financial buyers.
- Regulatory and export-control roadmap: A practical guide to navigating ITAR and allied transfer regimes, plus mitigation strategies for non-U.S. partnerships.
To preserve the report’s commercial utility, we intentionally withhold the full set of segment-specific forecasts and revenue tables in this preview. Subscribers receive the granular splits, unit-level demand models, and supplier-by-supplier revenue projections that underpin the strategic recommendations summarized here.
Competitive landscape — who matters and why
The competitive environment is a blend of global primes, national champions, and specialized component suppliers. Market concentration metrics point to a moderate level of aggregation: a small group of leading suppliers together hold a material portion of market value, while an active middle tier and innovative niche players sustain technology progression.
- RTX Corporation (Raytheon) & Kongsberg: Strong network-centric SHORAD offerings and leadership in NASAMS position them as pivotal integrators. Recent ballistic test milestones for Next Generation Short Range Interceptor (NGSRI) reflect successful maturation of replacement-fleet interceptors and signal a viable pathway for armies seeking to retire legacy MANPADS and adopt integrated, vehicle-mounted interceptors.
- Lockheed Martin: Ongoing NGSRI flight-test progress and M-SHORAD integration expertise keep Lockheed near the center of U.S. maneuver-protection modernization—an important factor for allied interoperability decisions.
- Rheinmetall: Momentum from major procurement commitments in Europe underscores the strategic value of automatic-cannon-based mobile systems for ultra-short-range and counter-drone tasks, particularly when mounted on modern AFV fleets.
- Rafael & IAI: Israel’s firms continue to innovate in point defense and layered interception architectures. Recent successful test series and framework agreements with partner nations demonstrate export traction for mixed missile and radar solutions.
- MBDA, Thales, Leonardo, Saab: European integrators and missile developers are consolidating capabilities across radar, seeker, and C2 integration, offering interoperable options for NATO and allied buyers navigating common operational requirements.
- ASELSAN, Hanwha, Elbit, L3Harris, Northrop Grumman, BAE Systems: These firms span indigenous SHORAD solutions, sensor suites, rocket propulsion, and integration layers—each playing a critical role in national programs and cross-border partnerships where export constraints or sovereign supply are decisive.
These vendors’ recent developments—test flights for NGSRI, ballistic trials, national framework agreements, and large-scale procurement plans—are catalysts shaping both near-term orders and longer-term industrial positioning. PW Consulting’s supplier dossiers unpack the commercial implications of each development for 2026 contracting cycles.
Regulatory, procurement and industrial dynamics to watch in 2026
- Procurement inflection points: Major national programs are transitioning from capability definition into production and delivery phases. For example, large-scale M-SHORAD plans in the United States and multi-vendor development contracts in Europe are driving increased production cadence and munitions demand.
- Export controls & allied interoperability: Technology transfer regimes continue to shape alliance procurement strategies. Our policy modelling shows that export-control friction increases preference for interoperable but non-sensitive sub-systems produced through allied partnerships.
- Cost and industrial base considerations: High R&D and per-unit system costs are driving procurement agencies to focus on modular, upgradeable architectures and munitions commonality to manage lifecycle affordability.
- Production scale and munitions throughput: Framework agreements and government-led production ramp programs are likely to be decisive for firms seeking scale economies; those unable to secure volume commitments risk margin compression and technological obsolescence.
Actionable recommendations for 2026
- For defense purchasers: Use a layered sourcing approach that balances a core integrator for platform integration with specialized suppliers for seekers, propulsion, and C2 to preserve flexibility and mitigate single-source risk.
- For prime contractors: Lock in production-rate agreements tied to performance-based milestones and invest in modular open-architecture interfaces to win multi-year upgrade work.
- For component suppliers & startups: Prioritize certification pathways and allied partnership routes to accelerate exportability; target niche but high-margin sensor and software domains where barriers to entry are higher for competitors.
- For investors: Focus on plays that either (a) capture aftermarket and munitions revenues or (b) provide critical enabling technologies (seeker algorithms, active-electronically scanned array radars, resilient comms) with defensible IP.
Conclusion and next steps
2026 is a pivotal year. The combination of steady market growth (6.38% CAGR across 2026–2032) and concentrated procurement cycles creates unique windows for influence: decisions taken this year on supplier selection, production commitments, and partnership structures will produce outsized returns or strategic lockouts across the following decade.
PW Consulting’s full Short Range Air Defense System Market Research report contains the granular forecasts, supplier revenue matrices, and playbooks required to convert insight into executable plans. For access to the complete dataset, unit-level demand models, and company scorecards referenced in this preview, please visit our website or contact our advisory team—subscription unlocks the detailed segment tables and scenario worksheets that underpin the recommendations above.
For detailed analysis of this topic, please visit the official page: Short Range Air Defense System Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


