



PW Consulting Forecast: Non‑Ferrous Scrap Metal Market Valued at USD 663.96 Billion in 2025

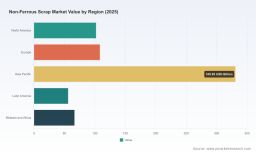
Non-Ferrous Scrap Metal Market — Strategic Outlook for 2026: A PW Consulting Preview
As companies prepare their 2026 strategic plans, the non-ferrous scrap metal market presents a mix of steady growth, structural disruption, and regulatory turbulence that will define competitive advantage across supply chains. PW Consulting’s latest market study (base year 2025) synthesizes five years of historical performance, a seven-year forecast (2026–2032), and deep operational diagnostics to deliver the context leaders need to prioritize investments, partnerships, and risk mitigations. This release offers a strategic preview of the report’s key insights; proprietary segment-level tables and scenario models are available in the full report.
Non Ferrous Scrap Metal Market
Why this market matters for 2026 decision-making
The global non-ferrous scrap metal market has moved from cyclical recovery to a structurally larger and more complex marketplace. After expanding from roughly USD 558 billion in 2020 to about USD 664 billion in 2025 (base year), the market is projected to continue expanding through 2032 with an expected market size above USD 850 billion under our central forecast. The forecast period (2026–2032) carries a compound annual growth rate (CAGR) of 3.6%—a pace that signals steady demand, but one that masks meaningful volatility across sub-segments, geographies, and product grades.
Non Ferrous Scrap Metal Market
For 2026, three imperatives emerge for executive teams: optimize feedstock quality through technology and upstream sourcing controls; re-evaluate geographic exposure given shifting trade and export policies; and accelerate capabilities in automation, material traceability, and downstream partnerships to capture margin and supply security.
Non Ferrous Scrap Metal Market
Market trajectory and macro drivers
-
Demand stability anchored in circularity: Increasing emphasis on recycled content across aluminum and copper end-markets—driven by corporate ESG targets and regulatory pressure—supports a structurally higher baseline demand for processed scrap as a feedstock.
-
Price cycles and raw-material supply constraints: Commodity price dynamics remain a critical determinant of scrap flows. Multilateral forecasts point to upward pressure on key non-ferrous commodity prices through at least 2027, amplifying the value of high-quality scrap streams and incentivizing investments in higher-yield recovery technologies.
-
Policy-driven localization and licensing: Recent policy moves (including export restrictions and state-level licensing for copper scrap) are already reshaping global flows and margin structures. These interventions create both short-term dislocations and long-term opportunities for regionalized processing hubs.
-
Technological adoption: AI-enabled sorting, sensor-based characterization, and improved shredding/recovery processes are no longer optional. Firms investing in such technologies are realizing step-change improvements in purity, downstream yields, and price realization.
Competitive landscape — where value is being captured
The non-ferrous scrap market is fragmented relative to primary metal producers, with market concentration measures indicating a moderate level of consolidation at the top (CR3 ~32.5%, CR5 ~38.0%). This structure leaves room for scale-seeking consolidators while enabling regional specialists to defend profitable niches.
-
Sims Metal Management Inc. — A global processor and trader with expanding advanced recovery operations. Their investments in AI-enabled sorting and upgraded shredding equipment position them to capture higher-purity streams and to expand value-capture from e-waste and complex alloys.
-
OmniSource Corporation — A North American-integrated operator with strong collection and processing networks. Their strength is in optimizing feedstock logistics and providing predictable supply to downstream smelters and fabricators.
-
European Metal Recycling (EMR) — EMR’s emphasis on copper and aluminum grades and their trading reach position them as a key hub for European material flows, particularly as export rules and domestic incentives shift material retention strategies.
-
Aurubis AG — As an integrated non-ferrous producer, Aurubis’ commissioning of a major copper recycling facility (recently operational) is a clear signal that downstream integration—linking scrap procurement to smelting and refined output—remains a high-value strategic play.
-
Regional and niche players — Established firms across North America, Asia-Pacific, and Australasia continue to provide critical collection and preprocessing capabilities. Their local footprint and contractual relationships underpin resilience in regional supply chains.
Recent corporate moves illustrate strategic direction. For example, capacity expansions with AI-enabled sorting reported by major processors in early 2026 and large-scale commissioning of recycling facilities in 2025 show a clear industry pivot toward higher recovery rates and processing complexity. These investments are not merely capacity plays—they’re an attempt to capture quality premiums, stabilize feed availability, and shorten routes to market in an environment where trade friction is rising.
Regulatory and financing catalysts — implications for 2026
-
Export controls and licensing: Policy announcements restricting exports of certain scrap grades and stricter seller licensing create near-term pricing anomalies and long-term incentives to locate value-adding processing within consuming regions. Companies must model both compliance costs and the upside of regional value capture.
-
Public financing for capacity expansion: Significant funding initiatives have emerged to accelerate recycling capacity and process optimization in key markets. These instruments lower the cost of capital for large-scale upgrades and favor projects with clear decarbonization and job-creation credentials.
-
Commodity price outlook: Forecasts signaling higher non-ferrous metal prices through 2027 increase the strategic value of securing clean scrap streams and long-term offtake arrangements, while also elevating the urgency of processes that can reliably produce high-grade inputs.
What PW Consulting’s report contains — practical outputs for executives
The full PW Consulting study goes beyond headline forecasting to deliver decision-useful tools tailored for 2026 planning cycles. Key deliverables include:
-
Market sizing and layered forecasts (2026–2032) with sensitivity cases that isolate the impact of price shocks, trade restrictions, and technology adoption rates on demand and realized margins.
-
Regulatory impact matrices and jurisdictional risk maps that quantify potential supply re-routing and compliance cost scenarios—designed for use in capital allocation and sourcing strategies.
-
Technology adoption playbooks that benchmark AI sorting, sensor-based characterization, and mechanical recovery investments against ROI thresholds, payback periods, and scale requirements for 2026–2028.
-
Commercial and M&A playbooks: prioritized target lists, integration risk checklists, and synergies templates for buyers and strategic partners, with valuation sensitivities to grade quality and contractual duration.
-
Operational diagnostics: modular checklists and pilot protocols to uplift yield, reduce contamination, and enhance traceability—ready for immediate deployment in procurement and operations teams.
Strategic recommendations for boardrooms and CEOs
-
Prioritize quality over quantity in feedstock strategy. In an environment of constrained primary supplies and more restrictive trade policies, premium for high-purity material will compress the economics of low-yield streams.
-
Invest selectively in automation and onboard sensor-based analytics. Early movers in AI-enabled sorting and in-line characterization will gain margin and downstream reliability; these investments are especially important for firms targeting higher-value alloy grades.
-
Reassess geographic exposure. Regulatory shifts mean that previously balanced global arbitrage opportunities are narrowing; companies should evaluate nearshoring (or “region-shoring”) strategies for processing capacity and offtake security.
-
Use financing programs strategically. Public and multilateral funding for recycling capacity can materially improve project economics—structures that combine concessional finance with private co-investment merit priority review.
-
Develop contractual hedges and long-dated offtakes with downstream partners to stabilize margins in periods of price volatility and regulatory uncertainty.
How executives should use this preview
This preview is designed to orient senior teams to the structural implications of the non-ferrous scrap market trends as they finalize 2026 budgets and capital plans. The full PW Consulting report contains the granular segment analyses, proprietary models, and jurisdiction-level figures that decision-makers require to operationalize the recommendations summarized here. Notably, detailed regional and application-level splits, asset-level valuations, and client-specific scenario outputs are intentionally withheld from this preview to preserve the utility of the full report as the definitive planning resource.
Next steps and access
For procurement leads, corporate development teams, and plant operations directors preparing 2026 strategies, PW Consulting provides tailored briefings, bespoke scenario runs, and implementation support packages. To obtain the complete report—containing the full data tables, segmentation breakdowns, and executable playbooks—visit the official PW Consulting report page or contact your PW account director for an executive briefing.
Strategic clarity in 2026 will come from combining market-level foresight with operational execution. The non-ferrous scrap market offers durable growth but rewards those who invest early in quality, regulatory intelligence, and technology-enabled processing. PW Consulting’s full study is designed to make those decisions actionable.
For detailed analysis of this topic, please visit the official page: Non Ferrous Scrap Metal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


