



PW Consulting Forecast: Cellular Base Station Antenna Market to Jump from USD 10,480 Million in 2025 to USD 27,877 Million by 2032 on a 15.0% CAGR (2026–2032)

Cellular Base Station Antenna for Telecommunications Industry Market — Strategic Briefing for 2026
Executive summary
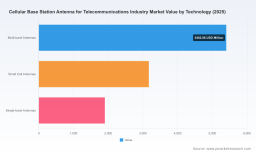
PW Consulting today publishes a pre-release briefing of our full market research report on the Cellular Base Station Antenna market, offering executive teams and investors a concise strategic view of what matters for 2026 decision-making. The market has moved from an estimated USD 5,120.45 Million in 2020 to USD 10,480.0 Million in 2025 and is projected to continue expanding through our 2026–2032 forecast horizon at an estimated compound annual growth rate of roughly 15.0%. By 2032 the model estimates total industry revenues in the tens of billions (USD 27,877.01 Million), driven by densification, Massive MIMO rollouts, and a wave of product innovation around active antenna systems and small cell form factors.
Cellular Base Station Antenna For Telecommunications Industry Market
Why this report matters in 2026
-
Timing for capital allocation: Networks are transitioning from capacity-driven 4G upgrades to capacity-and-latency-sensitive 5G densification. The pace implied by a mid-teen CAGR forces a re-evaluation of multi-year procurement pipelines, deployment phasing and lifecycle economics for antenna assets.
Cellular Base Station Antenna For Telecommunications Industry Market -
Technology inflection points: Active antenna systems, high-port Massive MIMO, and compact small‑cell antennas are migrating from early-adopter stages into mainstream deployment. Strategic product choices made this year will determine spectrum efficiency and per-bit cost profiles for operators over the next decade.
Cellular Base Station Antenna For Telecommunications Industry Market -
Regulation and spectrum dynamics: Recent regulatory actions in the United States and proposals to repurpose mid-band spectrum materially influence deployment strategies and vendor selection. At the same time, modernization orders that ease certain permitting and discontinuance processes lower structural barriers but create timing pressures to capture auctioned spectrum and densification opportunities.
-
Operational cost leverage: Energy efficiency and beamforming performance are no longer boutique attributes. Analyses shared in the market show that modest gains in passive and active antenna beam efficiency can produce meaningful throughput and energy savings at the cell edge—outcomes that reshape TCO when scaled across a national footprint.
What the full report delivers (practical, actionable content)
The full PW Consulting study is designed as a decision-making toolkit, not merely a descriptive market narrative. Highlights include:
-
A transparent market model (2020–2032), including baseline, upside and downside scenarios reflecting alternative spectrum and capex outcomes.
-
Vendor scorecards and product archetypes that evaluate performance, feature gaps, interoperability risk, and NDAA/geopolitical compliance for procurement teams.
-
TCO and unit‑economics templates for macro- and small‑cell deployments, with sensitivity analyses for energy cost, installation labor and site rental assumptions.
-
Supply‑chain risk maps and mitigation playbooks covering component concentration, alternative sourcing pathways, and near-shoring tradeoffs.
-
Five real-world deployment case studies showing how operators can sequence active antenna, passive antenna and RU investments to optimise throughput and CAPEX cadence.
-
A policy and regulation tracker with scenario implications tied to auction timing, permitting reforms, and cross-border trade controls.
-
An investor-focused chapter identifying M&A targets, consolidation catalysts and partnership archetypes that create scalable value in this concentrated market.
We intentionally withhold granular regional and application breakdowns in this briefing; the full data tables, interactive dashboards and downloadable financial models are accessible in the complete report.
Competitive landscape — positioning and strategic implications
The base station antenna sector is shaped by a mix of large systems integrators, global infrastructure OEMs and specialised suppliers. Market structure exhibits notable concentration among leading vendors, which creates both stability and strategic lock‑in risks for buyers.
-
Huawei Technologies Co. Ltd. — Strengths: comprehensive active and passive portfolios, deep R&D in Massive MIMO and energy-efficient RF architectures. Strategic implication: operators seeking rapid capacity scaling will weigh Huawei’s technical breadth against geopolitical and procurement constraints; alternative supplier strategies should be modelled in parallel.
-
Ericsson AB — Strengths: integrated antenna-radio platforms and well-established E2E systems engineering for global 5G. Strategic implication: Ericsson’s integrated approach reduces integration risk for operators migrating to active antenna systems but can command premium pricing; evaluate total integration value rather than capex alone.
-
Nokia Corporation — Strengths: multi-band Massive MIMO optimized across urban/rural use cases and strong AirScale integration. Strategic implication: Nokia is a compelling choice where multi-environment optimisation and software-defined radio features are priorities.
-
CommScope — Strengths: scalable RF and hybrid LTE/5G antenna lineups, DAS experience for complex in‑venue deployments. Strategic implication: strong contender for operators prioritising heterogeneous networks and indoor-outdoor continuity.
-
Amphenol , Comba , Rosenberger , RFS , ACE Technologies , Tongyu , Kathrein (Ericsson) , PROSE , JMA Wireless , Alpha Wireless , HUBER+SUHNER — These suppliers offer differentiated strengths across mechanical robustness, RF connectors, niche high-gain solutions, domestic manufacturing footprints and sustainability-focused passive antennas. Strategic implication: procurement should match vendor selection to deployment archetype—macro, small cell, in‑building or enterprise—with a clear evaluation of integration friction and long-term support commitments.
Recent industry activity merits attention: NEC’s 2026 announcement of a compact, energy-efficient Massive MIMO RU underscores the market’s push toward tighter integration between radio units and antennas. Likewise, the NGMN Alliance’s updated recommendations provide a practical taxonomy to simplify vendor comparisons and accelerate deployment harmonisation.
Market structure and concentration
The industry shows a concentrated supplier landscape. Leading vendors collectively command a majority share of revenue and influence roadmap standards and supply‑chain dynamics. For procurement and M&A strategists, that concentration creates both bargaining power opportunities and single‑point risks that should be stress‑tested in procurement contracts and continuity planning.
Key strategic recommendations for 2026
-
Adopt phased procurement linked to spectrum milestones: Synchronise capital commitments with confirmed spectrum availability and permitting reforms to avoid stranded assets or overhangs during rapid band repurposing.
-
Prioritise energy and beam efficiency in RFPs: Include measurable beam efficiency and lifecycle energy metrics as weighted criteria; even modest efficiency gains translate to substantial network-level savings and edge throughput improvements.
-
Design for multi‑vendor interoperability: Require open interfaces and clear integration SLAs to avoid lock-in, particularly when combining active antenna systems with third-party RUs and OSS/BSS stacks.
-
Invest in supply‑chain resilience: Map single-point component dependencies and develop contingency sourcing for critical RF parts; consider contract structures that incorporate lead-time flexibility and inventory pooling.
-
Leverage procurement vehicles and partnership models: Explore shared densification programs, leasing models for RUs/antennas, and outcomes-based contracts that align vendor incentives with throughput/availability KPIs.
-
Prepare regulatory playbooks: Monitor auction timelines, permitting liberalisation and proposed band repurposing. Early engagement with regulators and municipal authorities reduces rollout friction and captures first-mover advantages.
-
Evaluate M&A and JV opportunities: For vendors and investors, assess targets that provide compounding value: low-cost manufacturing, proprietary RF IP, integration skills or strong regional channels.
What we are not disclosing here — and why
This briefing intentionally omits granular region-by-region and application-by-application splits, as well as the detailed tables and interactive models that underpin our forecasts. That level of granularity is included in the full report and interactive data sets because it is the material that directly supports procurement negotiations, investment memoranda and deployment playbooks. We are sharing the macro trajectory, competitive context and strategic implications here so senior teams can prioritise internal reviews; the complete dataset is required to operationalise decisions.
Next steps — how to use this intelligence
-
Procurement leaders: request the vendor scorecards and TCO templates to run live RFP simulations.
-
Network planners: use our scenario models to align rollout waves with spectrum auction calendars and regulatory milestones.
-
Investors and corporate development teams: access the M&A heat map and concentration analytics to shortlist targets or partnership candidates.
PW Consulting’s full Cellular Base Station Antenna for Telecommunications Industry Market report contains the proprietary models, downloadable spreadsheets and vendor benchmarking datasets necessary to convert the insights in this briefing into executable programmes. For access to the complete report, interactive dashboards and consulting engagement options, please contact PW Consulting’s market research desk or visit our report portal.
For detailed analysis of this topic, please visit the official page: Cellular Base Station Antenna For Telecommunications Industry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


