



PW Consulting: Coal Tar Pitch Market Poised to Grow at 4.85% CAGR

Coal Tar Pitch Market: Strategic Intelligence for 2026 Decision-Making
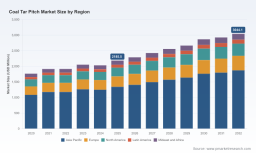
PW Consulting's latest Coal Tar Pitch Market brief translates multi-year data, on-the-ground industry dynamics, and competitive intelligence into a decision-grade roadmap for executives planning capital allocation, commercial strategy, and regulatory compliance in 2026. Using a 2025 base year and a proprietary demand-supply model, the report traces the market from 2020 through 2025 and projects through 2032. The market recorded steady recovery and rebalancing after pandemic disruption — rising from approximately USD 1,765 million in 2020 to USD 2,185 million in 2025 — and our forecast extends to a projected market size north of USD 3,000 million by 2032 at a compound annual growth rate of 4.85% (USD, Million basis).
Coal Tar Pitch Market
Executive summary — what matters for 2026
-
Structural demand is steady but resegmentation is underway: traditional aluminum and electrode end-markets remain material, while graphite and battery supply chains are reshaping near-term demand profiles.
Coal Tar Pitch Market -
Supply-side constraints and feedstock volatility are creating premium windows for compliant, low-PAH grades; newcomers that secure feedstock or processing flexibility will win pricing power.
Coal Tar Pitch Market -
Regulatory tightening in North America and Europe is not hypothetical — compliance costs are real and will influence capacity economics and product design starting in 2026.
-
Market concentration is meaningful: the top three suppliers control a dominant share of the market while the top five consolidate further, creating both barriers and acquisition targets for mid‑size players.
What this report delivers — operational, not academic
-
Demand and price modeling: a transparent model calibrated to 2020–2025 actuals and scenario-tested through 2032, enabling stress-testing of capex and offtake assumptions.
-
Supply-mapping and corridor analysis: primary and secondary supply nodes, port and logistics constraints, and realistic lead-time estimates for incremental tonnage.
-
Regulatory impact playbooks: country-level compliance cost estimates, mitigation pathways for PAH restrictions, and a step-by-step investment roadmap to retrofit legacy grades.
-
Competitive intelligence: executive-level profiles, capacity positioning, recent strategic moves, and a supplier scorecard that quantifies operational resilience and commercial flexibility.
-
Commercial toolkits: negotiation templates for long-term supply agreements, indexing mechanisms for pitch pricing, and customer retention frameworks for smelters and electrode producers.
-
M&A and partnership playbook: target-screening criteria, valuation sensitivity checks, and integration checklists for bolt-on pitch assets and processing facilities.
Market dynamics shaping 2026 strategy
-
Feedstock volatility and structural shifts in steelmaking: The ongoing transition toward electric-arc furnace (EAF) capacity in many steel systems, combined with intermittent coal-tar availability, has increased feedstock price volatility for pitch producers. This reality tightens the economics for non-integrated players and raises the value of vertical integration or secure, long-term feedstock contracts.
-
Regulatory tightening around PAHs: Jurisdictions are actively tightening limits or extending bans on coal tar products for specific applications. Examples include long-standing prohibitions at the state level in certain U.S. jurisdictions and proposals to tighten PAH thresholds elsewhere. In parallel, EU REACH-related directives are increasing compliance costs for legacy grades. These trends accelerate demand for low‑PAH and tightly specified grades and create compliance-driven capacity planning imperatives for 2026.
-
Demand resegmentation toward battery and specialty graphite: Commercial launches and capacity investments across graphite and battery material supply chains are starting to pull coal tar pitch demand in new directions. Facilities that can cost‑effectively produce low-impurity pitch with controlled softening points will have a first-mover advantage in supplying precursors for high-value graphite applications.
-
Logistics and export corridors matter: Recent milestone shipments and new processing terminals demonstrate that export corridors are evolving. Producers and buyers alike should treat logistics as strategic assets rather than commoditized line items.
Competitive landscape — positioning and strategic moves
-
Koppers Holdings Inc.: As an integrated carbon-pitch producer with a strong legacy customer base in aluminum anodes and graphite electrodes, Koppers benefits from established offtake channels and technical know-how in binder technologies. The strategic question for 2026 is how Koppers balances legacy product stewardship with investments into lower-PAH, battery‑grade offerings.
-
Rain Carbon Inc.: Rain Carbon’s recent facility build-out in Andhra Pradesh signals a clear push into graphite and battery precursor markets in addition to traditional aluminum demand. Their move to add incremental distillation and processing capacity in Asia demonstrates a strategy that blends geographic diversification with product-grade expansion — a model others are likely to replicate.
-
Himadri Speciality Chemical Ltd.: With significant installed capacity and a growing export footprint, Himadri is leveraging vertical integration and terminal access to open new supply corridors. Their milestone liquid‑pitch export to the Middle East underlines an emerging exporter playbook that pairs large-scale processing with logistics agility.
-
Deza, a.s. and Shree Shyam Chemicals: These regional players provide important flexibility and local-market responsiveness. Their roles in specialty grades and regional supply balancing make them attractive partners or acquisition targets for global suppliers seeking to de-risk distribution and compliance pathways.
-
Implications: The market’s CR3 and CR5 concentration metrics indicate that incumbents retain pricing leverage but that regional entrants and strategic investments can shift local dynamics quickly. Expect M&A and JV activity focused on capacity, low‑PAH technology, and proximity to end-use clusters.
Recent transactions and developments to watch
-
Capacity additions targeted at graphite/battery/aluminum end-markets are material: new distillation and pitch processing capacity in Asia is intended to capture growing demand from battery-related graphite processors.
-
Commercial supply arrangements for liquid pitch aimed at securing smelter continuity are appearing as strategic hedges; long-term supply MoUs and pilot off‑take contracts are increasingly common.
-
Export corridor developments: first‑of‑kind liquid pitch exports from new port terminals are opening alternative origins for buyers seeking redundancy.
Strategic playbook for 2026 — recommended actions
-
Secure feedstock via layered hedges: Combine short-term spot purchases with medium- to long-term feedstock agreements and selective vertical integration to stabilize margins.
-
Invest in low‑PAH processing and certification: Prioritize CAPEX for low-emission processing lines, PAH testing capabilities, and third-party certification where route-to-market depends on regulatory compliance.
-
Design flexible product portfolios: Modularize processing assets to switch between aluminum, electrode, and specialty battery-precursor grades quickly as offtake windows open.
-
Lock in logistics resilience: Lease or co-invest in terminal capacity on key export corridors; model inventory buffers that reflect both regulatory and feedstock risks.
-
Execute opportunistic M&A and alliances: Target regional processors and terminal operators to secure distribution and regulatory know‑how; pursue JVs with graphite and battery material players to guarantee demand pull.
-
Integrate regulatory foresight into capex decisions: Run sensitivity cases where PAH limits tighten suddenly — allocate a portion of CAPEX to retrofit readiness rather than retrofitting under duress.
Scenario framing — three near-term outcomes
-
Base case: Moderate, steady growth consistent with our central forecast (roughly mid-single-digit CAGR over the forecast window) driven by stable aluminum demand and incremental uptake in graphite/battery precursors.
-
Downside case: Accelerated regulatory restrictions and slower metallurgical demand reduce conventional offtake; legacy grades face obsolescence without investment, favoring vertically integrated and compliance-ready players.
-
Upside case: Rapid scaling of battery and specialty graphite supply chains accelerates demand for high‑spec pitch grades, rewarding producers who can certify low-impurity, narrow-specity product streams.
Why PW Consulting’s 2026 guidance matters
This report is purpose-built for commercial leaders, supply-chain heads, and private-equity teams who must translate technical market signals into executable strategy. We combine a data-driven top-line forecast with granular operational checklists and supplier intelligence that goes beyond headlines. Importantly, while this release highlights the analytical scaffolding and strategic implications, we have intentionally withheld detailed regional and application-level splits in this preview to protect proprietary model integrity and to direct stakeholders to the full dataset and supplier scorecards available through our portal.
For teams planning investment decisions, contracting cycles, or compliance investments in 2026, the report provides the framework to identify where to deploy capital, which supplier relationships to prioritize, and how to price risk into long-term agreements. PW Consulting also offers bespoke scenario workshops and valuation support for teams preparing M&A bids or strategic partnerships in this space.
Access the full Coal Tar Pitch Market report for complete datasets, regional and application breakdowns, the supplier scorecard, and downloadable models to run your own sensitivity tests. For tailored briefings and advisory support, contact PW Consulting’s Coal Tar Pitch practice.
For detailed analysis of this topic, please visit the official page: Coal Tar Pitch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


