



PW Consulting Predicts Polarizer for OLED Market to Expand at a 10.32% CAGR Through 2032

Polarizer for OLED Market — Strategic Snapshot for 2026 Decision-Making
By PW Consulting — Senior Strategy Advisor & Chief Industry Analyst
Polarizer for OLED Market
Executive preview
The polarizer segment for OLED displays is at an inflection point. Our new Polarizer for OLED Market report, with a 2025 base year and a forecast horizon through 2032, shows the market expanding from roughly USD 2.19 billion in 2025 to an expected USD 4.35 billion by 2032, at a compound annual growth rate (CAGR) of 10.32% over the forecast window. That trajectory reflects sustained demand from mainstream OLED form factors while being tested by accelerating technology shifts that could displace conventional polarizers in targeted applications.
Polarizer for OLED Market
This release is written for executives who must set 2026 budgets, capex plans, supplier strategies, and M&A priorities. Below we outline the strategic implications, competitive dynamics, and playbooks that the report contains in operational form — while intentionally withholding detailed regional and application-level splits to preserve the full report’s commercial value.
Polarizer for OLED Market
Why this matters for 2026 planning
-
Timing matters: 2026 is a pivot year. The market scale and the above-trend CAGR create room for expansion, but concurrently, commercially viable polarizer-free innovations and alternative optical stacks are moving from R&D into productization. Procurement, R&D, and corporate development functions must be aligned now to either capture upside or insulate performance.
-
Concentration amplifies strategy effect: The market is relatively concentrated — the top three suppliers command the majority share, and the top five control an even larger portion — which means strategic moves by market leaders (capacity, pricing, or technology licensing) cascade quickly through the ecosystem and can reshape supplier economics within 12–18 months.
-
Material and policy exposures are asymmetric: Profitability depends not only on product innovation but also on management of PVA/iodine supply chains and geopolitical factors like tariff regimes. Gross margins in the industry have been reported in the mid-teen to low-twenties range; preserving that requires active raw-material and policy risk mitigation.
What the report delivers (practical contents)
-
High-resolution market forecast (2026–2032) with scenario trees reflecting variable adoption curves for polarizer-free solutions and flexible OLEDs.
-
Risk-quantified raw-material model that links iodine and PVA price scenarios to supplier margin sensitivity and suggests hedging and sourcing tactics.
-
Competitive playbooks for incumbents and challengers — covering product differentiation, cost-to-serve optimization, licensing models, and partnership archetypes with panel makers.
-
Decision-ready M&A and JV frameworks (valuation multipliers adjusted for concentration metrics and technology-risk premiums), plus integration checklists focused on optical film manufacturing and downstream coating capabilities.
-
Go-to-market modules for premium vs. volume segments, including price elasticity tests, channel mapping, and a 12–24 month partner engagement cadence tailored to foldable and large-area OLED use cases.
-
KPIs and early-warning indicators to trigger tactical moves — e.g., PVA/iodine price spikes, tariff announcements, display OEM design wins for polarizer-free stacks, or capacity announcements by top suppliers.
Competitive landscape — what to watch
The supplier fabric blends long-established optics specialists with vertically integrated chemical and display groups. Leaders bring distinct advantages:
-
Nitto Denko Corporation (Japan) — recognized for ultra-thin polarizers and high-performance circular polarizers optimized for flexible and high-contrast OLEDs. Nitto’s deep material science and production know-how make it a natural partner for smartphone and high-end panel makers seeking yield stability at scale.
-
Sumitomo Chemical (Japan) — a major PVA-based film producer whose strength lies in optical film chemistry and consistency for premium consumer-electronics panels. Sumitomo’s upstream polymer competencies create defensible margins on premium offerings.
-
LG Chem / Shanjin Optoelectronics (Korea / China) — leveraging retained OLED-specific capabilities and regional manufacturing footprints, they are prominent in supplying circular polarizers for large-size and flexible panels where supply chain proximity matters.
-
Samsung SDI / Ace Digitech (Korea) — notable for tailoring polarizers to foldable and premium handset displays; however, their strategic posture is currently under review as they balance internal display synergies and third-party supply opportunities.
-
BenQ Materials (Taiwan) — a leader in bendable circular polarizers for foldables, with a focused product roadmap aimed at the flexible-device segment and strong OEM relationships in that domain.
-
Other regional producers (Polatechno, Optimax, Sunnypol, CMMT, SAPO Photoelectric, WINDA, Tunghsu) provide capacity diversity and represent local market dynamics that can be leveraged for cost competitiveness or rapid localized scale-up.
Collectively, this mix of specialist optics firms and generalized chemical producers shapes an ecosystem where technological differentiation, supply security, and scale economies determine winners. Our report includes operational profiles, plant-by-plant capabilities assessments, and supplier scorecards to support vendor selection.
Technology and disruption signals
-
Polarizer-free designs are materializing. Independent industry analysis forecasts polarizer-less OLED shipments to reach 244 million units by 2032, driven by innovations like COE and OLED transmittance control films (OTF). These developments can materially reduce unit polarizer demand in selected product classes (notably certain TVs and smartphone subsegments).
-
SAM display wins and awards (e.g., polarizer-free LEAD technologies) are an early indicator of design wins that will propagate through OEM supply chains within 18–36 months; suppliers must watch patent filings and conference demonstrations closely.
-
R&D and material science remain a competitive moat — ultra-thin flexible polarizers and advanced compensation films will retain high value in categories where polarizer-free solutions cannot yet match optical performance or durability (e.g., some AR/VR and automotive safety-critical displays).
Supply chain & policy risk — the near-term playbook
Raw materials anchor the cost base. Polarizer film production is heavily reliant on polyvinyl alcohol (PVA) and iodine; the global iodine market is sizable (projected at approximately USD 3.21 billion in 2026) with Chile supplying a dominant share of output. These inputs are volatile and can compress margins unless actively managed.
Additionally, tariff and trade policy are active levers. Historical tariff concessions in some jurisdictions have supported localization; anticipated policy shifts in 2026 — particularly in major manufacturing nations — could alter landed costs and sourcing logic. US-China tariff dynamics also represent a persistent tail risk for cross-border suppliers.
Practical responses include: multi-sourcing critical inputs, strategic iodine forward purchases or tolling agreements, selective upstream investment (e.g., minority stakes in key chemical suppliers), and contracting clauses that pass through raw-material inflation.
Strategic recommendations for 2026
-
Adopt a dual-track product strategy: continue to invest in ultra-thin and flexible polarizers for near-term high-margin opportunities, while establishing R&D pilots or partnerships to integrate polarizer-free options where they align with OEM roadmaps.
-
Prioritize supplier resilience: lock in multi-year agreements with key PVA and iodine suppliers, and create contingency plans for tariff-driven re-shoring or near-shoring of capacity.
-
Use the year to secure selective vertical integration: small, targeted investments in upstream chemical capability or strategic tolling partnerships can defend margins in commodity-stressed scenarios without the capital intensity of full upstream M&A.
-
Prepare for consolidation: given industry concentration, scale matters. Build an M&A playbook focused on acquiring specialty film capabilities and proprietary coatings rather than broad chemical portfolios — execute deals that deliver immediate route-to-market and customer contracts.
-
Institute a real-time signal dashboard: track PVA/iodine price indices, tariff policy calendars, key OEM design-win disclosures, and patent filings for polarizer-free technologies as triggers for tactical reallocation of resources.
What we intentionally withhold here
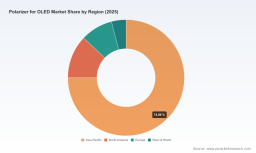
To preserve the actionable value of our market intelligence and to comply with our “trailer” approach, this release omits the detailed region-by-region and application-by-application numeric breakdowns, and finer-grained pricing curves that are included in the full report. Those granular segmentation tables and supplier-level shipment forecasts are available in the complete Polarizer for OLED Market report.
Next steps
If your 2026 strategy includes procurement, capacity investment, M&A, or product repositioning in the optical films space, PW Consulting’s full report equips you with the models, supplier scorecards, scenario playbooks, and negotiation templates necessary to act decisively. Contact our team to schedule a briefing and obtain the full dataset and executable annexes.
PW Consulting — bringing market foresight to strategic action.
For detailed analysis of this topic, please visit the official page: Polarizer for OLED Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


