



PW Consulting: Laser Spectrum Analyzer Market Poised for 7.42% CAGR, Reaching USD 700.1 Million by 2032

Laser Spectrum Analyzer Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s latest market study on Laser Spectrum Analyzers distills actionable intelligence for corporate leaders, product strategists, and procurement teams preparing to make high‑stakes decisions in 2026. Grounded in a detailed historical review (2020–2025) and a robust forecast (2026–2032), the report synthesizes commercial dynamics, supplier positioning, and near‑term risks that will materially affect capital allocation and go‑to‑market choices.
Laser Spectrum Analyzer Market
Executive snapshot
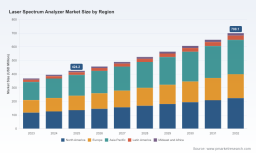
Our analysis finds that the global laser spectrum analyzer market stood at USD 424.2 Million in the base year 2025. Under the central scenario, the market is projected to expand at a compound annual growth rate (CAGR) of 7.42% across the 2026–2032 forecast window, reaching approximately USD 700.1 Million by 2032. Market concentration is meaningful: the leading three suppliers account for a majority share, while the top five firms collectively command close to seven in every ten dollars of market revenue—an important context for competitive strategy.
Laser Spectrum Analyzer Market
Why 2026 is a strategic inflection point
-
Technology convergence is accelerating. Laser spectrum analyzers are migrating from large benchtop research instruments toward integrated, modular test solutions embedded in manufacturing and network‑level diagnostics. This increases demand heterogeneity and creates product development opportunities for vendors that can balance resolution, speed, and form factor.
Laser Spectrum Analyzer Market -
Supply chain and regulatory headwinds are no longer peripheral. Recent changes in export control regimes and semiconductor equipment restrictions that take effect through 2026, combined with materials and helium supply volatility, are already influencing lead times and component budgets for test equipment purchases.
-
Market consolidation and specialization proceed in parallel. While a handful of incumbents preserve strong positions through breadth and global reach, specialist players are winning on niche performance attributes—high resolution, compact PXIe form factors, and integrated light‑source ecosystems—creating differentiated value for end users.
Key demand drivers and use cases to watch
-
Telecommunications and high‑capacity networks: sustained investment in optical networks and advanced fiber architectures keeps laser characterization and channel analysis as major pull factors.
-
Semiconductor photonics and component manufacturing: tighter process controls and wafer‑level photonics testing are accelerating demand for instruments that combine high resolution with throughput‑friendly ergonomics.
-
Research, aerospace, and defense: precision wavelength metrology and linewidth analysis remain indispensable where accuracy, traceability, and environmental robustness matter.
Competitive landscape — who matters and why
The market architecture blends global test & measurement conglomerates with specialized optical instrumentation companies. Each cohort plays a distinct strategic role:
-
Bristol Instruments (Victor, NY) has carved a reputation for combining Michelson interferometer architectures with FFT analysis to deliver hybrid wavelength metering and spectrum analysis. Their emphasis on frequency stabilization and multi‑laser control positions them well in advanced laser labs and precision manufacturing applications.
-
Thorlabs Inc. (Newton, NJ) competes on modularity, price‑performance, and a broad accessory ecosystem. Their OSAs appeal to both research and telecom laboratories that require fiber‑coupled and free‑space flexibility with competitive noise floors and resolution.
-
Yokogawa Test & Measurement Corporation (Tokyo) remains a reference brand for high‑stability optical spectrum analysis across a wide wavelength span. Their multi‑decade product lineage underpins enterprise purchasing decisions where long‑term service and calibration ecosystems matter.
-
Anritsu and EXFO bring telecom‑grade measurement suites with lab‑to‑field workflows—critical for customers balancing R&D validation and network commissioning.
-
Specialized entrants such as Quantifi Photonics , HighFinesse , and APEX Technologies are differentiating via compact form factors, sub‑µm configurations, and high resolving power for VCSEL and component‑level characterization.
-
Regional and vertically oriented suppliers (e.g., Shimadzu , Optoplex , O/E Land , and CNI Laser ) focus on integrated solutions or pricing/availability advantages in specific end markets.
Recent vendor moves and tactical implications
-
Product launches and platform extensions are accelerating. For example, Shimadzu’s announced SPG‑V500 (InGaAs) launch expands wavelength coverage in communications bands and signals renewed vendor competition in high‑speed spectrum measurement for optical comms markets.
-
Bristol Instruments’ recent multi‑laser control and high‑resolution wavelength meter introductions indicate a push toward bundled stabilization and measurement workflows—an attractive proposition for R&D and industrial laser subsystems.
-
Innovative ecosystem showcases (e.g., Quantifi Photonics integrating novel light sources) foreshadow product roadmaps that prioritize cross‑vendor interoperability, which buyers should prioritize in procurement specifications.
Risk map: supply, regulation, and cost pressures
-
Export control regimes: Updated U.S. export controls affecting semiconductor equipment (with 2026 effective elements) introduce compliance complexity for vendors and OEMs. Decision‑makers should embed regulatory scenario planning into supplier selection and contractual commitments.
-
Component and raw materials: Geopolitical strains in semiconductor supply chains are lengthening lead times and amplifying price volatility for critical optical components and specialty gases. Procurement teams must recalibrate inventory policies and dual‑source strategies.
-
Helium and specialty inputs: Regional conflicts and trade restrictions are disrupting helium availability—impacting manufacturing processes that some suppliers rely on. This creates a secondary operational risk that can influence delivery schedules and pricing.
Strategic recommendations for 2026
In light of the above, we recommend pragmatic, prioritized actions for firms making 2026 decisions:
-
Adopt a two‑track sourcing policy. For mission‑critical test equipment, secure capacity with established global vendors while qualifying fast‑to‑deploy specialist suppliers for niche measurement needs. Include export‑control clauses and dual‑sourcing triggers in contracts.
-
Invest in modular product roadmaps. Product leaders should prioritize architectures that allow software upgrades and plug‑in hardware modules to extend lifecycle value and defray capital intensity.
-
Embed regulatory and supply‑chain scenarios in capex planning. Factor in potential lead‑time extensions and compliance costs tied to semiconductor equipment controls; run stress tests on procurement budgets under multiple compliance outcomes.
-
Pursue targeted partnerships and M&A selectively. Acquihires and technology partnerships with compact‑form factor or light‑source specialists can accelerate time‑to‑market for integrated solutions, while distributor alliances can mitigate regional service risk.
-
Standardize measurement interoperability. Buyers should specify open interfaces and calibration traceability in tenders to avoid vendor lock‑in and to future‑proof instrumentation investments.
What the PW Consulting report delivers — practical deliverables
This study is purpose‑built for executive decision cycles in 2026. It includes:
-
A transparent market model with historical reconciliation (2020–2025) and a segmented forecast (2026–2032) that supports scenario analysis and sensitivity testing against price and adoption assumptions.
-
Supplier scorecards and capability maps that evaluate product performance, distribution reach, service networks, and regulatory exposure—designed to underpin RFP shortlists and supplier negotiations.
-
Operational toolkits: procurement checklists, contract language templates for export controls, lead‑time mitigation playbooks, and a calibration & service‑cost calculator to estimate TCO over instrument lifecycles.
-
Commercial strategy templates for vendors and OEMs, covering product positioning, channel strategies, and a prioritized M&A heatmap that highlights adjacencies likely to accelerate growth or consolidate capabilities.
-
Scenario planning modules that model the financial and operational impact of supply disruptions, export control escalations, and accelerated adoption curves across core end‑user segments.
How leaders should use this report in 2026
For corporate strategy teams, the report serves as a decision primer for R&D budgeting, M&A screening, and product roadmaps. For procurement and operations leaders, it provides the frameworks and checklists needed to secure supply continuity and manage compliance risk. For vendors, it offers benchmarking and route‑to‑market prescriptions to protect margin and expand into adjacent use cases.
Access and next steps
PW Consulting’s Laser Spectrum Analyzer Market report is intentionally structured to be both rigorous and actionable. The public summary offered here is designed as a strategic teaser—showcasing our analytic depth while reserving detailed segmentation cells, exact regional and end‑use splits, and model-level assumptions for the full report. Organizations that require the detailed datasets, supplier scorecards, and scenario workbooks should consult the complete study to inform procurement contracts, product investments, and M&A diligence in 2026.
For bespoke briefings, custom scenario runs, or supplier due diligence support tied to this market study, PW Consulting’s industry team is available to provide targeted advisory engagements tailored to your timeline and risk appetite.
For detailed analysis of this topic, please visit the official page: Laser Spectrum Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


