



PW Consulting: Education Fuels Flutes Market — Valued at USD 467.18 Million in 2025, Poised to Reach USD 627.72 Million by 2032 at a 4.31% CAGR

Flutes Instrument Market — Strategic Outlook for 2026: Actionable Intelligence from PW Consulting
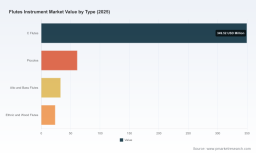
PW Consulting’s new Flutes Instrument Market report (base year 2025; historical window 2020–2025; forecast 2026–2032) delivers the market intelligence executives and investors need to make high‑stakes decisions in 2026. The global market has expanded from roughly USD 382 million in 2020 to an estimated USD 467 million in 2025 and is projected to continue growing to approximately USD 628 million by 2032 at a compound annual growth rate (CAGR) of 4.31%. These headline figures frame a market that is mature in developed territories, yet dynamic where education funding, cultural programming, and product innovation intersect.
Flutes Instrument Market
Why this report matters for 2026 decision cycles
-
Timing and horizon alignment: 2026 will be a pivot year for manufacturers and distributors adjusting to trade policy volatility, rising sustainability expectations, and renewed public investments in music education—our forecast horizon (2026–2032) identifies actionable windows for product launches, capacity shifts, and M&A moves.
Flutes Instrument Market -
Macro to micro translation: We translate topline growth into demand scenarios for product tiers (student, intermediate, professional) and channel implications (bricks, e‑commerce, institutional procurement), while preserving the granularity companies need to stress‑test plans.
Flutes Instrument Market -
Risk‑aware strategy: The report embeds regulatory shocks—most notably tariff disruptions—and supply chain fragilities into scenario planning so leadership teams can prioritize hedges and contingency playbooks.
What PW Consulting’s Flutes report includes (practical, operational content)
-
Market sizing and trend decomposition: A reproducible top‑down and bottom‑up methodology, year‑by‑year market values (2020–2025) and a firm forecast (2026–2032) with sensitivity ranges tied to policy and education spending assumptions.
-
Demand drivers and use‑case analysis: Detailed treatment of education programs, performance/professional demand, and hobbyist markets—mapped to lifecycle purchasing behavior and replacement cycles.
-
Competitive benchmarking and vendor scorecards: Standardized assessments of product breadth, manufacturing footprint, brand equity, distribution strength, and innovation capability for leading makers and brands.
-
Supply chain and cost model: Input cost mapping (materials, labor, logistics), tariff exposure analysis, and manufacturing relocation case studies with TCO (total cost of ownership) scenarios.
-
Route‑to‑market playbooks: Channel economics for school procurement, rental and rental‑to‑own models, retail merchandising, and digital direct‑to‑consumer strategies.
-
M&A and partnership pipeline: Target archetypes, valuation heuristics, and integration checklists for bolt‑on acquisitions in accessories, headjoint specialists, and regional distribution platforms.
-
Regulatory and cultural risk register: Up‑to‑date intelligence on tariffs, certification requirements, and cultural programming that affect demand.
-
Decision dashboards: KPI templates and monitoring triggers to convert market intelligence into board‑level actions.
Competitive landscape — positioning and implications
The flutes market features a mix of scale manufacturers with broad wind instrument portfolios and a resilient artisanal tier that commands premium pricing and institutional reputation. Market concentration is moderate: the top three firms capture a meaningful share of global value and the top five amplify that position—this structure causes strategic tension between volume players and niche artisan makers.
-
Scale brand leaders: Companies with diversified wind portfolios and global distribution benefit from scale economics and channel reach. Their strengths are product breadth (student through professional), robust dealer networks, and investments in manufacturing consistency. Sustainability moves—such as redesigned packaging to reduce waste and improve the customer experience—signal brand investments that reduce non‑product frictions and resonate with younger buyers and institutional purchasers.
-
Exclusive and artisanal manufacturers: A cluster of premium, handmade makers—many located in traditional hubs—sustain high margins through craftsmanship, custom work, and orchestral market adoption. These firms leverage reputation, bespoke service, and limited production to defend pricing even as regulatory and shipping costs vary.
-
Mid‑market and educational specialists: Manufacturers that prioritize entry and intermediate instruments—often using offshore production models—compete on value, supply reliability to school programs, and after‑sales service. Their playbook centers on partnerships with education systems and rental programs that lower adoption barriers.
Strategic implications
-
Scale manufacturers must balance cost control with brand elevation to avoid commoditization in the student segment while protecting premium channels.
-
Artisanal makers should systematize knowledge capture (e.g., headjoint craft techniques) and consider selective industrial partnerships to scale without diluting heritage branding.
-
Distributors and retailers will need to redesign inventory and warranty models to manage tariff‑related price volatility and to support institutional procurement cycles.
Recent industry dynamics that will shape 2026
-
Trade and tariff volatility: Recent tariff measures on woodwind instruments have materially increased landed costs for imported instruments and accessories. These measures have already contributed to export downturns in affected markets and should be central to 2026 sourcing strategies and pricing models.
-
Public investment in music education: Government funding and policy initiatives in several emerging economies are driving demand for beginner and student instruments. For firms that can align production and distribution to institutional procurement timelines, this is a tangible growth lever.
-
Cultural programming and visibility: Major museum exhibitions and regional recognition of artisan clusters are expanding consumer awareness beyond core markets, creating marketing and licensing opportunities that savvy brands can monetize.
-
Sustainability and packaging: Small but meaningful packaging redesigns and other sustainability gestures are becoming brand differentiators; they also present cost considerations that must be weighed against customer lifetime value gains.
2026 Strategic playbook — recommendations by stakeholder
-
Manufacturers: Conduct a tariff‑stress TCO analysis for each supply line; prioritize nearshoring of critical components where lead times or tariff exposure is highest; develop modular product platforms to shorten lead times for institutional specs.
-
Retailers and distributors: Build rental and school‑procurement bundles; implement dynamic pricing linked to landed cost indices; co‑invest with manufacturers in local service hubs to extend product life and customer loyalty.
-
Investors and M&A teams: Target platform deals that consolidate regional distribution or strengthen accessory ecosystems (casework, headjoints, cases) and prioritize targets with captive institutional relationships.
-
Education and policy partners: Design procurement frameworks that balance cost with instrument longevity and maintenance; consider bulk‑buy plus local maintenance agreements to secure better long‑term outcomes.
Decision scenarios and monitoring framework
We outline three rapid scenarios—base (moderate growth at consensus), downside (extended tariff and logistic disruption), and upside (accelerated education funding and cultural demand). For each, the report provides specific triggers and a monitoring dashboard: enrollment and procurement notices, landed cost indices, inventory aging across channels, and artisan order lead times. These are the indicators that shift resource allocation between production, marketing, and M&A.
Next steps — how to convert insight into action
For C‑suite leaders preparing 2026 roadmaps, this study translates market growth projections into tactical imperatives: optimize supply chains against tariff regimes; segment product investment between scalable student volumes and high‑margin custom instruments; and commit to measurable sustainability initiatives that lower lifecycle cost and elevate brand preference. Our vendor scorecards and downloadable financial models (available in the full report) enable teams to run bespoke what‑if analysis and prioritize capital deployment with conviction.
PW Consulting’s Flutes Instrument Market report is designed as a decision tool: it gives executives the context, the playbooks, and the triggers to move from insight to confident action in 2026. For complete segment‑level breakdowns, vendor rankings, and the full set of scenarios and financial models, please consult the full report on the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Flutes Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


