



PW Consulting Forecasts 5% CAGR as Lead-Based Rare Earth Alloy Market Expands from USD 306 Million in 2025 to USD 430.6 Million by 2032

Lead-Based Rare Earth Alloy Market — Strategic Briefing: 2026 Playbook
PW Consulting’s new market study on Lead-Based Rare Earth Alloys (base year 2025; historical coverage 2020–2025; forecast 2026–2032) frames 2026 as an inflection year for corporate strategy. The underlying market has been both resilient and increasingly exposed to upstream rare-earth volatility: after recovering from early-decade fluctuations, global industry revenues reached approximately USD 306.0 Million in 2025 and are projected to grow at a compound annual growth rate (CAGR) of roughly 5.0% through 2032 (our scenario central-case points to an overall market above USD 430 Million by 2032). For executives, investors, and policy teams, the study translates these macro dynamics into near-term decision levers — while reserving granular segment-level figures for subscribers to the full dataset.
Lead Based Rare Earth Alloy Market
Why 2026 matters: a convergence of price, policy and production
-
Upstream price shocks: Q2 2026 saw pronounced upward pressure on rare-earth concentrates used as feedstock for lead-based alloys; reported quarter-over-quarter increases approached mid-double-digits, a change that materially shifts raw-material cost curves for alloy producers and downstream battery manufacturers.
Lead Based Rare Earth Alloy Market -
Policy acceleration: government capital flows and industrial programs in 2025–2026 (notably in North America and other markets) are actively financing metallurgical capacity, separation and metallization projects aimed at reducing concentrated supply-chain risk.
Lead Based Rare Earth Alloy Market -
Regulatory tightening: lead-containing alloys remain subject to robust environmental and occupational health controls. Compliance costs and permitting timelines are now a non-trivial part of capital planning for primary alloy producers and recyclers alike.
Market trajectory and interpretive takeaways
The market’s historical pattern (2020–2025) shows recovery after near-term disruption, followed by steady expansion into our forecast window. That growth is underpinned by persistent demand from legacy applications such as lead-acid battery grids — where rare-earth additions materially improve corrosion resistance and mechanical reliability — and by specialized industrial niches (radiation shielding, corrosion-protective alloys, and various cable and sheathing uses). While the headline CAGR of ~5% signals steady upside, the underlying volatility of rare-earth feedstock prices and the concentrated nature of supply require differentiated strategies rather than uniform capacity expansion.
Key dynamics that should shape 2026 capital and commercial plans
-
Feedstock governance is now strategic: sharp moves in rare-earth concentrate pricing mean procurement teams must move beyond spot buying. Long-term offtakes, index-linked pricing clauses, and equity into upstream raw-material projects are legitimate tools to stabilize margins.
-
Product-form differentiation reduces commoditization: companies that offer alloys in a range of finished forms (wire, foil, strip, custom master alloys) capture premium margins and stickier customer relationships. Investments in finishing lines and quality traceability yield higher returns than undifferentiated melt-and-sell models.
-
Regulatory foresight reduces execution risk: lead-related environmental and workplace regulations materially affect capital allocation and logistics. Early engagement with regulators, and pre-emptive investment in emissions control and worker protection systems, shortens time-to-market for expansions.
-
Supply-chain localization is a hedging strategy: industrial policy incentives in several markets now make local metallurgical investments more attractive to OEMs and system integrators seeking to de-risk battery and shielding supply chains.
Competitive landscape — what the leadership map looks like
The sector shows moderate concentration: our market-concentration indicators place the leading three firms with a material share of the market and the top five commanding a clear majority — a structure that shapes pricing power, access to feedstock, and technology diffusion. A brief, non-exhaustive strategic read on principal players:
-
Integrated metal groups with upstream control (examples among established Chinese producers): these players leverage captive lead and rare-earth inputs to protect margin and manage feedstock availability. Their competitive edge lies in integration economics, scale of operations, and established logistics networks.
-
Non-ferrous diversified companies (manufacturers of zinc, germanium and related metals): companies that combine multiple non-ferrous streams can optimize smelting and refining synergies, offering flexibility in alloy formulations and often holding strong relationships with downstream battery manufacturers.
-
Specialist alloy and processing houses: manufacturers focused on master alloys and value-added forms (wire, foil, capillary, precision strip) compete on product differentiation, quality control, and custom formulations — areas where premium pricing and long-term contracts are common.
-
Mining-linked entrants and miners moving downstream: groups with mining assets in non-ferrous or rare-earth domains have the option to vertically integrate, influencing raw-material allocations and creating potential upstream-downstream arbitrage.
For companies considering partnership or M&A, the priority screen should emphasize: access to secured rare-earth feedstock; finished-form processing capability; regulatory compliance track-record; and customer concentration risks in battery and industrial end-markets.
What PW Consulting’s report delivers (practical, transaction-ready content)
Subscribers will find operationally focused modules designed for decision-makers implementing 2026 strategies:
-
Validated market-size model covering 2020–2025 with a granular, scenario-based forecast through 2032 (central, upside, downside) and sensitivity to rare-earth price trajectories.
-
Supply-chain maps and cost-curve analysis that show where margin pressure originates and how processing steps contribute to final alloy economics.
-
Price-impact scenarios tied to upstream concentrate shocks and regulatory cost migrations, including short- and medium-term cash-flow implications for producers and OEMs.
-
Competitive benchmarking and capability heatmaps for leading and mid-tier firms (production technologies, product forms, geographic reach, feedstock access, and compliance posture).
-
Commercial playbooks for OEMs and alloy suppliers: offtake negotiation templates, hedging instruments, and contract structures that balance security of supply with price flexibility.
-
M&A and partnership screens: target prioritization criteria, valuation overlays, and integration risk checklists tailored to the alloy sector’s unique environmental liabilities and permitting timelines.
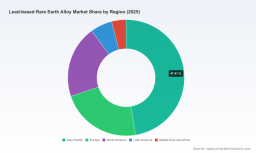
Note: the full report contains detailed segment breakdowns, regional splits and application-level tables to inform precise budgeting and target selection; these data are intentionally omitted from this briefing to preserve exclusivity for subscribing clients.
Actionable recommendations for 2026 (prioritized)
-
Lock in feedstock optionality now. Negotiate staggered offtakes and consider minority upstream investments to mute next-cycle price shocks. Use indexed contracts to align supplier economics and avoid outright spot exposure.
-
Invest selectively in downstream finishing. If you are a producer, allocate CAPEX to value-added forms (strip, foil, wire) that are critical to high-margin segments. If you are an OEM, secure preferred-supplier agreements for finished forms to guarantee quality and lead times.
-
Accelerate compliance-driven upgrades. Budget for emissions control and workplace safety enhancements as a near-term cost of entry for new capacity — this reduces regulatory stoppage risk and shortens approval cycles for expansions.
-
Segment customers by exposure and profitability. Prioritize contracts with battery OEMs and industrial customers that internalize alloy performance gains (corrosion resistance, cycle life) and are willing to accept premium pricing for consistency.
-
Pursue strategic alliances rather than broad acquisitions in the near term. Where capital is constrained, joint ventures with feedstock holders or technology partners deliver asymmetric access without full balance-sheet commitments.
-
Integrate scenario planning into quarterly strategy reviews. Given the sector’s linkage to rare-earth price cycles and policy shifts, firms that institutionalize scenario analyses will execute capex and commercial decisions with materially lower downside.
Conclusion — playing for stable growth in an uncertain upstream landscape
The lead-based rare earth alloy market presents a classic strategic trade-off in 2026: steady end-market demand and modest headline growth (CAGR ~5%) sit alongside episodic upstream shocks and regulatory tightening that can rapidly compress margins and reprice projects. For pragmatic corporates, the path forward is not “more of the same” but smarter integration: securing feedstock optionality, increasing product differentiation, and embedding regulatory resilience into project economics. PW Consulting’s full study operationalizes these priorities with models, playbooks and M&A screens calibrated to the realities of 2026. For teams making binding capital commitments this year, the choice is between reactive bargaining on volatile inputs and adopting a structured, layered approach to supply, product and regulatory risk — the latter consistently delivers superior value in our simulations.
To access the full dataset, detailed segment tables, and bespoke scenario outputs that underwrite executable 2026 plans, please consult the report landing page (subscription required) or contact PW Consulting’s industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Lead Based Rare Earth Alloy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


