



PW Consulting Forecasts Semiconductor Focus Ring Market to Grow at an 8.22% CAGR, Reaching USD 4.26 Billion by 2032

Semiconductor Focus Ring Market: Strategic Imperatives for 2026 — PW Consulting Release
PW Consulting today releases a targeted market briefing derived from our full Semiconductor Focus Ring Market study. As device geometries compress and etch recipes become ever more complex, focus rings — the unheralded components that shape edge uniformity and process stability in plasma etch chambers — are moving from commoditized spares to strategic levers. Our report synthesizes a multi-year, supplier-validated view of the industry and translates it into actionable guidance for procurement, product and operations leaders preparing decisions in 2026.
Semiconductor Focus Ring Market
Market Trajectory & Key Metrics
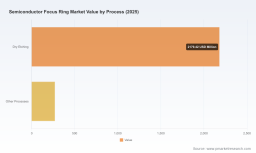
The focus ring market has demonstrated steady expansion through the mid-2020s, growing from roughly USD 1.61 billion in 2020 to about USD 2.45 billion by our 2025 base year (all values in USD Million). Looking forward, our bottom‑up forecast for 2026–2032 anticipates a compound annual growth rate (CAGR) of 8.22%, with the market reaching approximately USD 4.26 billion by 2032 under the base scenario.
Semiconductor Focus Ring Market
This growth is being driven by a convergence of trends: more aggressive multi-layer device stacks and die shrinks that place higher demands on edge control; wider adoption of SiC and engineered-ceramic materials to extend part lifetime under harsher plasma chemistries; and capacity additions in advanced-node fabs. The market is moderately concentrated: the top three players account for a majority share, and the top five firms extend that dominance further, reinforcing the need for buyers to balance technical performance requirements with supply resilience.
Semiconductor Focus Ring Market
What the Full Report Delivers (Practical, Operational Intelligence)
- Proprietary demand model (2020–2032) with multiple scenarios calibrated to wafer fab capex paths and etch tool adoption rates.
- Supplier scorecards and qualification playbooks that map technical attributes (material, coating, particle performance) to wafer-level outcomes and TCO impacts.
- Procurement playbooks: lead‑time hedging, conditioned inventory sizing for specialty ceramics, and contract clauses to mitigate export-control risk.
- Cost-of-ownership calculators allowing users to evaluate trade-offs between lower upfront cost silicon rings and longer-life SiC/ceramic solutions under varied etch recipes.
- Benchmarked qualification timelines and test protocols, including recommended metrology checkpoints and root‑cause templates for edge non‑uniformity issues.
- An M&A and partnership short-list, identifying strategically valuable small and medium suppliers for bolt‑on capacity or localized supply.
These deliverables are intentionally practical — serving engineering, sourcing and strategy teams that must translate macro trends into purchase orders, qualification roadmaps and capital planning for 2026.
Competitive Landscape — Who Matters Now
The vendor map remains diverse but leadership is clear. Established materials specialists and component suppliers have translated deep ceramics, silicon and CVD SiC expertise into differentiated offerings for modern plasma etch environments. Key players we profile in-depth include multinational ceramics and silicon specialists, as well as regional manufacturers that have achieved scale in high‑mix, mission‑critical supply.
- CoorsTek (United States): Advanced high‑purity ceramic focus/edge rings and proprietary PureSiC CVD silicon carbide solutions aimed at extreme dry‑etch environments.
- Morgan Technical Ceramics (United Kingdom): Focus and edge ring portfolios for dry etch, deposition and RTP, leveraging CVD SiC and high‑purity alumina for low particle shedding and thermal performance.
- Tokai Carbon (Japan): A recognized pioneer of solid SiC focus rings produced via proprietary CVD; known for durability in high‑performance etch applications.
- Regional and emerging suppliers (South Korea, China, Taiwan): Fast followers with competitive cost structures and customized silicon/ceramic manufacturing capabilities, some already scaling to supply large North American chipmakers.
We also analyze a recent commercial validation that illustrates the shifting supplier dynamics: in February 2025, a South Korean manufacturer received orders and passed qualification for a nitride‑free polycrystalline silicon focus ring design for a North American chipmaker, moving to mass production in Q1 2025. This case highlights how targeted material innovations and cost-competitive manufacturing can rapidly alter procurement shortlists for high-volume fabs.
Strategic Implications for 2026 Decision‑Makers
Our research crystallizes a set of near-term imperatives for companies making procurement, product architecture and capacity decisions in 2026. Below are the prioritized actions we recommend.
- Run material‑level trade-off analyses. The shift to more durable SiC-based rings is real, driven by recipe aggressiveness and lifetime expectations. But SiC typically involves longer lead times and higher initial unit costs. Use our TCO calculators to quantify break-even points versus silicon and quartz under your fab’s specific recipe mixes.
- Qualify on performance, not price alone. Forgoing rigorous particle and edge-uniformity benchmarking undermines wafer yields. Insist on supplier data for plasma-induced erosion, particle generation over time, and mechanical stability under thermal cycling.
- Rebalance sourcing for resilience. With longer speciality-ceramic lead times (often stretching several months) and export controls influencing trade flows, diversify Tier‑1 and Tier‑2 sources across legal/regulatory jurisdictions and consider local buffer stocks for critical fabs.
- Embed regulatory scenarios into procurement. Tightened export controls and restrictions on critical minerals can rapidly change qualification timelines and supplier eligibility. Contract templates should include clauses for compliance changes and validated secondary sources.
- Fast‑track qualification of lower‑risk substitutes. For high-volume production sites, qualify both primary and tested alternative materials (e.g., nitride‑free poly‑Si variants or coated ceramics) to reduce single‑supplier dependencies.
- Consider strategic partnerships and co‑engineering. The highest‑performing vendors are increasingly offering co‑development that shortens iteration cycles. Fabs that invest in upstream design collaboration can achieve better edge uniformity outcomes and lower run‑in rejects.
- Prioritize predictable supply for scale‑up projects. New fab ramp plans should include supplier capacity audits and binding route‑to‑market commitments for multi‑year horizons tied to tool deliveries.
Risk Scenarios and Operational Playbook
We model three risk scenarios in the full report — Low, Base, and High stress — incorporating variables such as raw material cost shocks, export control tightening, and accelerated adoption of alternative chemistries. Key operational mitigations we recommend are:
- Pre‑qualified alternate materials and dual‑sourced components for the most critical etch stations.
- Inventory layering: a rolling 3–6 month safety stock for specialty ceramics, coupled with a vendor‑managed inventory program for high‑velocity SKUs.
- Contractual visibility into supplier capacity and upstream raw‑material sourcing, with specified escalation paths for geopolitical disruptions.
- Investment in in‑house analytical capability to replicate key supplier tests for particle generation and erosion — shortening acceptance cycles.
Note: lead-time exposures for high‑purity SiC and specialty quartz are material. In several of our supply chain audits, lead times stretch to half a year or more under stressed conditions — a fact that must inform 2026 capex and procurement timetables.
Why This Report Matters for Your 2026 Roadmap
Decisions taken in 2026 about focus ring materials, supplier ecosystems, and qualification sequencing will have multi‑year implications for yield, cost and fab uptime. Our report translates complex material science, geopolitics and supply economics into executable steps: which suppliers to prioritize for partnership, how to structure qualification, and where to allocate working capital to hedge scarcity risks.
We follow a “trailer” approach in this release: the analysis above highlights the strategic contours and decision levers but intentionally omits granular region/application splits and proprietary supplier scoring that buyers need to operationalize supplier selection. Those detailed tables, methodology appendices, and downloadable calibration models are available in the full report and on our report landing page.
Next Steps — How PW Consulting Supports Your Team
- Executive briefing and model walk‑through for your procurement and process teams.
- Customized supplier short‑lists and qualification roadmaps tailored to your toolset and process chemistries.
- Scenario workshops to stress‑test procurement and fab ramp plans against export control and raw‑material disruption scenarios.
To access the full dataset, supplier matrices, and the operational playbooks referenced here, please visit our report landing page or contact your PW Consulting account director. Our team is prepared to run a focused, confidential diagnostic to translate the industry‑level findings into a 90‑day action plan for your 2026 priorities.
— PW Consulting, Semiconductor Practice
For detailed analysis of this topic, please visit the official page: Semiconductor Focus Ring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


