



PW Consulting: Di-tert-Butyl Peroxide (DTBP) Market to Reach USD 813.89 Million by 2032 at 5.1% CAGR; Asia Pacific Leads with USD 255.8 Million

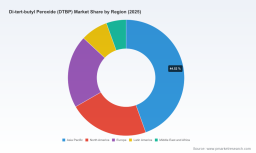
Di-tert-Butyl Peroxide (DTBP) Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting’s latest market study on Di-tert-Butyl Peroxide (DTBP) synthesizes five years of historical dynamics and a seven‑year forward view to give executives a compact, decision‑ready perspective as they set strategy for 2026. Using 2025 as the analytical base year, our model shows the DTBP market returning from cyclical volatility to a steady growth path with a compound annual growth rate (CAGR) of 5.1% across the 2026–2032 forecast window. From a mid‑decade recovery in 2024–2025 to a projected expansion toward the end of the decade, the trajectory underlines both resilience and selective opportunities for producers, converters, and capital allocators.
Di-tert-Butyl Peroxide (DTBP) Market
Why DTBP Matters in 2026
-
Strategic raw material for polymer chemistry: DTBP remains a preferred high‑temperature initiator and crosslinking agent across multiple polymer chains — a role that ties its fortunes to investment cycles in polyolefins, acrylics and specialty resins.
Di-tert-Butyl Peroxide (DTBP) Market -
Regulatory and logistics complexity: DTBP’s classification as an organic peroxide subject to hazardous‑materials transport rules and process safety management creates compliance costs and creates advantage for well‑prepared incumbents.
Di-tert-Butyl Peroxide (DTBP) Market -
Supply base polarization: Global majors and agile regional manufacturers coexist, generating both competitive pressure on margins and opportunities for selective consolidation, geographic reshoring and localized service models.
-
Feedstock dynamics matter: Manufacturing routes based on tert‑butyl alcohol and hydrogen peroxide dominate, while alternative synthesis research advances in catalysts and process intensification are emerging supply‑side considerations.
High‑Level Market Dynamics: A Practitioner’s View
Our historical analysis captures an industry that contracted and recovered unevenly between 2020 and 2025, reflecting downstream demand cycles and episodic supply disruptions. The 2026–2032 forecast reflects steady annual expansion at ~5.1% CAGR, driven by sustained polymer demand in established applications and incremental uptake in specialty uses. That macro trajectory masks meaningful micro variations—grade mix, localized logistics costs, inventory strategies and regulatory timelines materially shift outcomes between regions and customer segments. These are the differences that determine margins in 2026 and beyond.
What This Report Gives You (Operational, Not Theoretical)
-
Market sizing and demand modeling: A reproducible methodology linking polymer sector loadings, end‑market build‑rates and grade migration assumptions so you can stress‑test revenue scenarios under multiple macro outcomes.
-
Supply‑side mapping and risk heatmaps: Facility footprints, technology routes, single‑point failures and logistics chokepoints are mapped with mitigation options — from tactical buffer strategies to targeted CAPEX for redundancy.
-
Regulatory and transport playbook: Practical checklists to align operations with organic‑peroxide transport classification, OSHA process safety thresholds and EU REACH constraints, including gap analyses and compliance timing for new product introductions.
-
Commercial strategy tools: Pricing sensitivity matrices, contract structures (term, indexed, take‑or‑pay), and commercial KPIs tailored for both high‑purity and commodity DTBP grades.
-
M&A and partnership roadmap: Candidate screening criteria, value levers, and integration checklists for buyers and financial sponsors seeking exposure to DTBP value chains.
-
Scenario‑driven investment model: Interactive cash‑flow templates and IRR sensitivities accounting for feedstock price swings, production ramp timing, and regulatory capital requirements.
Competitive Landscape: Themes and Tactical Takeaways
The DTBP supplier base is a hybrid of global chemical majors, specialized peroxide houses, and regional producers focused on cost and delivery. Key strategic themes emerged in our competitive assessment:
-
Global technology leaders maintain product breadth and multi‑site redundancy. Established Western and Japanese players differentiate on global distribution, regulatory track‑record and technical service for demanding polymerization processes.
-
Specialist peroxide manufacturers emphasize product formulation, logistics expertise and custom‑grade development for high‑value applications such as acrylics and specialty polymers.
-
Regional, cost‑competitive producers in Asia have expanded capacity and are cost‑effective suppliers for standard grades; their proximity to feedstock and downstream converters is a structural advantage.
From a practical standpoint, companies with the following attributes are best positioned in 2026: multi‑site manufacturing with documented PSM regimes; flexible production allowing rapid grade shifts; integrated supply agreements for tert‑butyl feedstocks; and a disciplined approach to hazardous‑goods logistics.
Company Profiles: Strategic Posture (select)
-
Major multinational producers combine global distribution networks with branded high‑temperature initiators and broad regulatory registrations — enabling them to serve large polymer producers with technical service and consistent quality.
-
Specialist peroxide firms focus on product depth, REACH and other regulatory certifications, and stock positioning in key logistics hubs to reduce lead times for European and Asian converters.
-
Large regional manufacturers in China and India have scaled capacity aggressively to capture regional demand and exports; their competitive play is price and proximity, with growing emphasis on quality consistency for export markets.
Regulatory and Feedstock Considerations — Operational Impact
Regulatory classifications and hazardous‑materials transport rules (including the organic‑peroxide UN designation and process‑safety management regimes) are non‑trivial line items for any DTBP operation. In practice, these requirements drive capital outlays for storage, specialized transport, emergency response plans, and insurance. Firms that internalize these costs early and design supply chains around them will win commercial flexibility.
On feedstocks, the industry remains dominated by synthesis routes using tert‑butyl alcohol and hydrogen peroxide, while academic and pilot work explores alternative oxidation routes that could change cost curves if scaled. Notably, related tert‑butyl feedstock pricing has stabilized recently — a development that reduces near‑term margin volatility for committed producers.
Concrete Recommendations for 2026
-
For producers: Prioritize safety and compliance investments that unlock commercial trust—this is a low‑risk route to defend premium contracts. Evaluate modest CAPEX in second‑site redundancy or tolling relationships to reduce single‑point risk.
-
For converters/large buyers: Secure multi‑sourced supply agreements with clear quality specifications and defined escalation paths. Consider joint inventory pools with suppliers in key logistics nodes to reduce total landed cost.
-
For investors: Look for acquisition targets that combine technical know‑how, regulated approvals, and logistics assets. Value can be created through operational tightening, up‑sizing safety governance, and rationalizing product mixes toward higher‑margin grades.
The PW Consulting Advantage: How We Translate Insight into Action
The full PW Consulting DTBP study is engineered as a working tool, not a desk reference. Clients receive interactive demand models, supplier scorecards, compliance gap checklists, and a prioritized action plan tailored to executive mandates (growth, margin defense, or risk reduction). Our deliverables include scenario dashboards to stress‑test acquisition cases, a negotiation playbook for procurement, and a regulatory calendar keyed to regional implementation milestones.
We intentionally hold back detailed region‑and‑application splits in this public summary to preserve the commercial sensitivity and forensic value contained in our full dataset. Those granular segmentations—critical to supplier selection, tariff and duty analysis, and localized CAPEX planning—are available in the complete report and interactive client portal.
Next Steps for Executives
-
Request the interactive package to run your own scenarios against our baseline 2026 model and see supplier heatmaps relevant to your procurement footprint.
-
Schedule a strategic workshop with PW Consulting to convert the market view into a 90‑day tactical plan (supplier contracting, CAPEX sequencing, or M&A shortlist).
-
Commission a focused due diligence or supply‑security engagement if you are evaluating an acquisition or long‑term supply agreement in 2026.
DTBP is at once a mature product and a strategically sensitive commodity—where safety, regulatory readiness and supply‑chain design determine winners. Our study arms executives with the tools to convert a modest market expansion into lasting competitive advantage. For access to the full dataset, segmentation details, and bespoke advisory engagements, contact PW Consulting to unlock the operational playbooks behind these insights.
For detailed analysis of this topic, please visit the official page: Di-tert-Butyl Peroxide (DTBP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


