



PW Consulting: Marine Electric Motor Market to Skyrocket at 12.25% CAGR, Forecast Reaches USD 16,422.47 Million by 2032

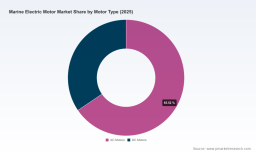
Marine Electric Motor Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive snapshot
PW Consulting's latest Marine Electric Motor Market report delivers a forward-looking, decision-grade picture for executives preparing plans in 2026. The market has transitioned from a niche electrification segment into a mainstream propulsion and auxiliary systems industry: our base-year analysis shows growth from roughly USD 4.1 billion in 2020 to about USD 7.3 billion in 2025, and modelled trajectories place the market north of USD 16.4 billion by 2032 at a compound annual growth rate of 12.25% over the 2026–2032 forecast horizon. That rate underscores rapid adoption across vessel classes and functions, driven by regulation, energy transition economics and technology maturation.
Marine Electric Motor Market
Why 2026 is an inflection point
-
Regulatory tipping points. IMO decisions in 2024–2025, culminating in the 2025 adoption of net‑zero measures and an emissions pricing mechanism that comes into force in 2027, convert long‑term decarbonization commitments into near-term compliance drivers. Shipowners, shipyards and OEMs must translate policy into procurement, retrofit, and design choices in 2026 to meet yard and financing timelines.
Marine Electric Motor Market -
Component and raw‑material dynamics. Elevated demand for copper and exposure to rare‑earth supply concentration are creating palpable procurement and cost risk. Buyers who assume stable input costs in 2026 expose themselves to margin and delivery shocks; those with active mitigation plans will gain negotiating and schedule advantages.
Marine Electric Motor Market -
Technology momentum and product proliferation. The last 18 months have seen an uptick in new motor topologies, high‑power permanent‑magnet designs and compact, modular units for small craft. Trade show activity and OEM catalog updates emphasize lighter, higher‑power density architectures—an important consideration for conversion projects and newbuild design windows in 2026.
-
Market structure. Competition spans global industrial incumbents with integrated systems and a vibrant specialist layer focused on outboards, pod drives and hybrid assemblies. Market concentration remains moderate: a small group of global players holds a meaningful share, while a larger cohort of specialists accelerates volume in recreational and short‑sea segments.
What the report delivers — practical, transaction‑ready intelligence
-
Top‑line market sizing and trend narratives (2020–2032) with reconciled historicals, base‑year calibration and transparent forecast assumptions.
-
Scenario‑based demand modelling that quantifies outcomes under alternative regulatory, commodity and technology adoption paths—designed for capital planning and risk stress testing.
-
Supplier assessment and strategic profiles that map capabilities (product range, power envelopes, systems integration, service footprint) and identify partnership vectors for OEMs, shipyards and asset owners.
-
Supply‑chain risk matrix including critical‑materials exposure, second‑tier supplier concentration, and mitigation levers (sourcing diversification, design substitution, inventory strategies).
-
Commercial playbooks for procurement, pricing and aftermarket services—templates you can deploy to convert strategic choices into RFPs, SLAs and long‑term supply agreements.
-
M&A and investment scorecards for target screening, valuation sensitivity to commodity and regulatory shocks, and integration risk indicators.
-
Practical case studies and deployment timelines for retrofits, newbuilds and small‑vessel electrification pilots—useful for operational planning and stakeholder alignment.
Competitive landscape: who matters and why
The market is defined by a dual structure. On one side are global industrial incumbents and system integrators that deliver high‑power motors, drives and full propulsion packages for commercial and offshore markets. On the other side are focused challengers and niche specialists targeting leisure craft, harbour vessels and nearshore applications with compact, high‑efficiency outboards and pod solutions.
-
Industry integrators such as ABB and Siemens combine propulsion systems, power electronics and services capability, making them natural partners for large shipyards and offshore platforms where integrated energy management is decisive.
-
Regional and specialist manufacturers—Ingeteam (Indar), TECO‑Westinghouse and WEG—occupy a critical position for medium‑ to high‑power vessel drives, offering robustness pedigree and customization for heavy marine environments.
-
Pure‑play electrification innovators including Torqeedo, ePropulsion, Evoy and Elco Motor Yachts are shaping adoption curves in recreational and short‑range commercial segments by delivering compact system architecture, software‑enabled controls and fast time‑to‑market product cycles.
-
Component and motor specialists like Nidec bring precision manufacturing and drive capability that can be repackaged for marine use or integrated into larger propulsion platforms.
Recent industry activity—product demonstrations at major expos, catalog updates showing multi‑megawatt offerings, and concept launches for electric outboards—confirms a market in active diffusion. For corporate strategy teams, the key questions are which segments to own, which partners to contract, and which technology trajectories to hedge against.
Supply‑chain and technology risk dynamics: what to watch in 2026
-
Rare‑earth exposure: dependence on high‑energy‑density permanent magnets creates geopolitical and price risks. Alternative motor chemistries and magnet recycling will be competitive differentiators for firms that can industrialize them within two‑to‑three years.
-
Copper availability: increased demand for motors and charging infrastructure tightens timelines. Procurement strategies in 2026 should include multi‑year contracts, buy‑and‑hold hedges and validated second‑source suppliers.
-
Standards and interoperability: as hybrid and full‑electric systems proliferate, players that drive interoperability standards (connectors, control protocols, battery management interfaces) will secure aftermarket and software revenue share.
-
Service networks and life‑cycle economics: electrification shifts value from fuel to uptime, software and spare parts. Robust field service and digital monitoring capabilities will materially alter total cost of ownership (TCO) for buyers and create recurring revenue streams for suppliers.
Strategic playbook for executives (practical steps for 2026)
-
Prioritize portfolio choices by vessel class and revenue durability—define 'where to play' using TCO scenarios that include carbon pricing and input cost volatility.
-
Implement a raw‑material mitigation plan: secure long‑lead contracts for magnets and copper, evaluate recycled magnet pathways, and fund design projects for lower‑rare‑earth architectures.
-
Invest selectively in systems integration capability or partnerships to capture downstream services revenue—aftermarket margins will make or break many electrification business cases.
-
Design procurement contracts with indexation and shared‑savings mechanisms to protect margins while aligning supplier incentives on reliability and performance.
-
Use pilot fleets and staged rollouts to derisk technology choices—shorter pilots in 2026 accelerate learning curves while preserving capital for scale‑ready projects.
-
Prepare for regulatory compliance now: factor IMO 2027 measures into ship design, retrofit timelines and financial models for newbuild bids.
-
Evaluate M&A targets through a resilience lens—targets with strong service networks, unique IP in magnet or motor design, or anchor client relationships offer strategic optionality.
How PW Consulting’s report accelerates decisions
Our report is built as a toolset as much as an analysis. Beyond headline forecasts, subscribers receive runnable models and decision templates: scenario engines that let procurement and finance teams stress‑test CAPEX/OPEX under alternative commodity and regulatory paths; supplier heatmaps to shortlist partners by capability and geographic coverage; and transaction playbooks for carve‑outs or strategic alliances. We pair this with expert workshops that convert the report’s outputs into a 12‑ to 24‑month actionable roadmap tailored to a client’s fleet composition and strategic ambition.
Next steps
This briefing highlights the strategic contours of a rapidly evolving market while intentionally omitting granular segmentation tables and detailed regional splits that are critical for transaction execution. For full access to the segmentation datasets, supplier scorecards, downloadable financial models and bespoke advisory options, please visit our report page or contact PW Consulting’s Marine Electrification Practice. The 2026 planning window is narrow: applied intelligence and executable options developed now will determine who captures the structural gains in this decade.
— PW Consulting, Marine Electrification Practice (senior strategic adviser & chief industry analyst)
For detailed analysis of this topic, please visit the official page: Marine Electric Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


