



PW Consulting: Missile Decoy Launcher Systems Market Poised for 5.51% CAGR in 2026–2032, Targeting USD 6,060 Million by 2032

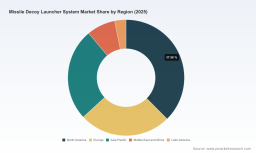
Missile Decoy Launcher System Market: Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on Missile Decoy Launcher Systems (base year 2025; historical 2020–2025; forecast 2026–2032) frames 2026 as a pivotal year for procurement, capability investment, and industrial positioning. The global market—measured in USD Million—recorded sustained growth through the first half of the decade and reached approximately USD 4,163 Million in 2025. Under our medium-term scenario, the sector is projected to expand at a compound annual growth rate (CAGR) of 5.51% through 2032, approaching the USD 6,060 Million mark by the end of the forecast horizon. These macro-dynamics, together with a moderately concentrated supplier base (CR3 ≈ 48.5%, CR5 ≈ 62.15%), create both opportunities and dilemmas for defense planners, prime contractors, and investors in 2026.
Missile Decoy Launcher System Market
Why 2026 is an Inflection Point
-
Operational need is colliding with platform modernisation cycles. Several navies and allied services are entering mid-life upgrades or new-build phases in 2026, amplifying demand for soft‑kill solutions that can be integrated with contemporary combat management and EW systems.
Missile Decoy Launcher System Market -
Threat evolution has accelerated. Adversary investments in coordinated anti-ship missile salvos, stand-off seekers, and high‑speed missiles are pushing navies toward trainable, modular launchers and a blend of expendable and active decoy countermeasures.
Missile Decoy Launcher System Market -
Supply‑chain sensitivity and materials intensity matter more. Decoy launchers increasingly depend on high-strength alloys, precision electronics, and specialized payloads—factors that affect lead times, lifecycle costs, and risk allocation across prime contractors and subcontractors.
-
Market structure favours scale and integration. With the top-tier vendors commanding a large share of the market, new entrants and mid-tier suppliers must differentiate via interoperability, payload neutrality, or niche decoy technologies.
High-Level Findings That Should Inform 2026 Strategy
-
Healthy, predictable growth at the market level. The projected 5.51% CAGR to 2032 supports multi‑year procurement programmes and justifies investment in production capacity and long‑lead component inventories.
-
Consolidation and alliance formation are strategic levers. The market concentration metrics indicate room for partnerships, joint ventures, and consortium bids to win platform-level programmes and meet sovereign-industrial requirements.
-
Product architecture is shifting from fixed, single‑role dispensers to trainable, modular systems. Systems that can host both passive expendables (chaff, flares, corner reflectors) and active decoy payloads increasingly command procurement preference.
-
Integration is as valuable as hardware. Suppliers offering mature integration pathways with combat management systems, offboard active decoys, and common launcher interfaces are being favoured in recent programme awards.
-
Export and geopolitical vectors will shape addressable markets. Naval modernisation across NATO and allied states, combined with regional tensions, continues to underpin demand—yet export controls and coalition interoperability considerations will influence partner selection.
What the PW Consulting Report Delivers (Practical Utility for 2026 Decisions)
-
Actionable market sizing and scenario modelling: an audited 2020–2025 historical baseline, a 2026 pivot-year assessment, and three forecast scenarios (conservative, base, accelerated) to stress-test procurement plans and capital allocation.
-
Procurement playbooks: decision matrices that map platform life‑cycle phase, threat profile, and operational concept to recommended launcher architectures, acquisition routes (direct buy, FMS, offsets), and sustainment models.
-
Supplier benchmarking and bid readiness checklists: comparative scorecards across technical capability, integration maturity, production capacity, and export pedigree—designed for both primes and defence ministries preparing RFPs.
-
Supply‑chain risk maps: identification of critical material and component nodes (precision electronics, propellant/rocket motors, alloy forgings), with mitigation strategies including dual‑sourcing, obsolescence management, and regional inventory pre-positioning.
-
Investment and M&A guidance for investors: valuation sensitivities, synergy capture scenarios, and strategic priorities for target screening (e.g., payload specialists, trainable launcher OEMs, electronic‑warfare integrators).
-
Practical annexes: interoperability checklists, test and acceptance frameworks, and roadmaps for integrating active decoys and soft‑kill doctrine into existing ship‑borne defensive architectures.
Competitive Landscape: Who Matters and Why
The competitive field blends global primes, specialised decoy houses, and national shipyards. The report’s company profiles synthesise capability, operational footprint, and recent activity to help procurement teams and primes shortlist qualified partners quickly. Below are summarised strategic observations on leading vendors included in the study:
-
Terma A/S (Lystrup, Denmark): Known for its C‑Guard MK II naval decoy launchers and modular, decoy‑agnostic design philosophy. Strengths include fielded systems and global in‑service support experience—advantages in retrofit programmes.
-
Safran Electronics & Defense (France): Offers high‑performance, trainable launcher systems used as naval references. Strong systems engineering and payload versatility make Safran competitive in nations seeking European sovereign supply chains.
-
Rheinmetall AG (Germany): Focused on scalable, multi‑launcher solutions and innovative decoy munitions. Positioning is advantageous where prime contractors seek integrated ammunition-to-launcher suites.
-
Elbit Systems Ltd. (Haifa, Israel): Supplier of advanced rotatable, stabilized launchers and active decoy integrations. Elbit’s product updates and export contracts reflect a dual strength in prime integration and payload development.
-
BAE Systems, L3Harris, Lockheed Martin (UK/US/US): These prime contractors anchor active decoy programmes (e.g., Nulka family) and bring systems‑level integration, program management, and offset capability—essential for large surface combatant programmes.
-
Rafael Advanced Defense Systems and Chemring Group: Offer payload innovation—active decoys and passive expendables respectively—making them critical partners for modular launcher ecosystems.
-
IrvinGQ and SEA (Cohort group): UK‑based specialists in corner reflectors and trainable systems; they combine niche product leadership with programme wins on Royal Navy platforms.
-
Emgepron (Brazil): An example of sovereign capability development, supplying national shipbuilding programmes and reflecting the rising interest in domestically manufactured decoy launchers.
Recent contract awards and product unveilings in 2024–2025—procurements for frigate classes, selection of trainable bases for Royal Navy systems, new national trainable launchers, and product refreshes from established vendors—underscore active competition and a buyer preference for trainable, integrable, and payload‑agnostic solutions.
Strategic Recommendations for 2026
-
Prioritise modularity and payload neutrality in procurement specs. Buyers looking for lifecycle flexibility should define interface standards, test harnesses, and integration roadmaps in RFPs to prevent vendor lock‑in.
-
Invest in integration labs and joint test events. Early technical and operational integration pays off—reducing acceptance risk, accelerating IOC, and lowering retrofit costs when new decoys or ECCM techniques emerge.
-
Mitigate supply‑chain fragility. Establish dual sourcing for critical materials and secure long‑lead components via framework agreements or strategic inventory pools tied to platform schedules.
-
Leverage alliances and consortia for scale. Shared procurement across allied navies or pooled sustainment arrangements can lower per‑unit costs while expanding supplier footprints.
-
Adopt a layered procurement approach. Combine immediate buys of mature systems for near‑term capability with concurrent investment in active decoy R&D and modular launcher upgrades for mid‑ and long‑term threats.
-
Factor export and regulatory trajectories into sourcing decisions. Programmes requiring coalition interoperability should prioritise vendors with proven export records and compliance pathways.
Closing: How This Report Helps You Act in 2026
PW Consulting’s missile decoy launcher market study is designed as a decision‑support tool for 2026: it blends audited macro projections (CAGR, market size trajectory), competitive intelligence, procurement playbooks, and practical supply‑chain mitigations. The report supplies the analytical depth to justify capital allocations, the tactical checklists to structure procurement RFPs, and the strategic framing to align industrial policy with operational requirements.
We intentionally present market direction, competitor strengths, and procurement levers in this briefing while reserving the full granular segmentation, contract‑level tables, and downloadable datasets for the report package. For acquisition teams, industrial strategists, and capital allocators that must make choices in 2026—this study is the operationally oriented intelligence input that transforms uncertainty into an actionable plan.
For detailed analysis of this topic, please visit the official page: Missile Decoy Launcher System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


