



PW Consulting: Bone Cement for Spine Market to Reach USD 1,328.96 Million by 2032, Expanding at a 5.81% CAGR (2026–2032)

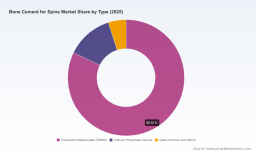
Bone Cement for Spine Market 2026: Strategic Implications from PW Consulting’s New Industry Brief
Executive summary
PW Consulting’s latest market research on Bone Cement for Spine offers a precisely calibrated intelligence package designed to inform corporate strategy choices in 2026. The market has expanded steadily through the early 2020s — rising from a mid‑hundreds million USD base in 2020 to an estimated USD 895 million by the 2025 base year — and our forecast scenario projects continued growth through 2032, with a compound annual growth rate (CAGR) of 5.81% embedded in the outlook and an end‑point that approaches USD 1.33 billion in 2032 under the central case. Those topline dynamics frame a market that is large enough to reward scale and specialization, yet concentrated enough that selective moves can produce outsized strategic returns.
Bone Cement for Spine Market
Why this brief matters for 2026 decision‑makers
- Timing: 2026 is the inflection year where several clinical, regulatory and reimbursement signals begin interacting to alter product adoption curves. Our brief dissects these interactions and converts them into decision‑grade scenarios.
- Resource allocation: Whether you are prioritizing R&D spend, commercial footprint expansion, or M&A, the brief identifies where limited resources will achieve the fastest path to differentiated returns.
- Risk management: The spine bone cement category is exposed to regulatory nuance, sterilization and material validation requirements, and reimbursement coding dynamics. We translate those technical constraints into operational steps that reduce launch and reimbursement risk.
Market dynamics: what’s driving value in spine bone cement
Three structural forces are shaping opportunities and threats:
Bone Cement for Spine Market
- Clinical innovation and product evolution. High‑viscosity formulations, radio‑opaque blends, and antibiotic‑enhanced cements have moved from niche to mainstream in select geographies and indications. These product attributes are increasingly decisive in hospital procurement discussions because they materially affect procedure workflow, cement handling time, and perceived complication profiles.
- Regulatory and sterilization expectations. PMMA bone cements for vertebral augmentation are regulated under defined Class II pathways and associated special controls, and device dossiers must demonstrably address sterility assurance level (SAL 10^-6), appropriate sterilization method validation, and pyrogenicity testing. Successful 510(k) strategies increasingly hinge on well‑documented sterilization and biocompatibility packages, as well as robust bench and handling data that speak to real‑world clinician needs.
- Reimbursement and procedure economics. Procedural reimbursement frameworks for percutaneous vertebral augmentation — including the codes that cover cavity creation and cement injection with imaging guidance — remain a de facto lever of adoption. Alignment between product claims, labeling, and procedural CPT coding materially accelerates hospital uptake.
Competitive landscape: positioning and tactical takeaways
The category displays moderate to high concentration: the top three firms capture a majority portion of the market, and the top five companies increase that share substantially. This structure produces dual strategic imperatives: incumbents must defend scale advantages and evidentiary depth, while challengers can win with targeted clinical differentiation and nimble regulatory execution.
Bone Cement for Spine Market
- Stryker Corporation (Kalamazoo, MI) — established interventional spine franchise with a focused portfolio of vertebral augmentation cements. Strength: integration across device and cement portfolios creates stickiness in procedural bundles. Strategic implication: incumbency provides negotiating leverage with centers of excellence, but requires continued investment in handling and radiopacity improvements to preserve share.
- Medtronic plc (Dublin, Ireland) — offers high‑viscosity radiopaque PMMA formulations optimized for vertebral stabilization. Strength: global commercial reach and strong relationships at the hospital level. Strategic implication: for new entrants, displacing a player with this reach necessitates a differentiated clinical case and cost/effectiveness evidence.
- Zimmer Biomet Holdings, Inc. (Warsaw, IN) — expanded portfolio including antibiotic‑loaded bone cements introduced recently, signaling a push toward infection‑risk mitigation across orthopedic and spine uses. Strength: cross‑portfolio synergies across orthopedics and spine. Strategic implication: antibiotic formulations open adjacent commercial opportunities but also require clear regulatory and labeling strategies.
- DePuy Synthes (Johnson & Johnson) , Heraeus Medical , Merit Medical Systems , IZI Medical , Cardinal Health , Tecres , Teknimed , Xelite Biomed , and Biocomposites — a mix of global OEMs and specialist players with offerings that range from commodity PMMA grades to highly specialised high‑viscosity and RF‑modulated systems. Tactical implication: alliances, distribution partnerships, or targeted licensing can be faster and less capital‑intensive routes to market than greenfield development in many jurisdictions.
Recent developments to watch (implications for 2026)
- Xelite Biomed received FDA 510(k) clearance for a high‑viscosity spinal bone cement late in the 2024–2025 cycle. The clearance underscores the continuing regulatory receptivity to differentiated handling and viscosity claims when backed by appropriate performance data.
- Amber Implants obtained 510(k) clearance for a vertebral support system designed to be used with bone cement; the move highlights how implants and cement systems are being co‑engineered to deliver improved biomechanical outcomes and to create bundled purchasing propositions.
- Zimmer Biomet’s launch of antibiotic‑loaded Tekcem variants in 2025 demonstrates a market appetite for infection‑mitigating formulations — particularly in patient cohorts at elevated infection risk — and signals a battleground for product premiumization that will intensify in 2026.
Report contents: what PW Consulting delivers (operationally useful)
Our full report is structured to move quickly from insight to execution for commercial, R&D, regulatory and corporate development teams. Key deliverables include:
- Executive deck with scenario‑based revenue and investment ladders tied to alternative assumptions about adoption curves, pricing delta, and reimbursement trends.
- Go‑to‑market playbooks segmented by customer archetype (academic centers, community hospitals, specialty clinics) and by procurement model (bundled purchasing, national tenders, group purchasing organizations).
- Regulatory pathway maps across major jurisdictions detailing predicate selection, recommended bench and sterilization evidence packages, and common failure modes observed in recent 510(k) interactions.
- Reimbursement playbook that aligns clinical claims to CPT coding strategy and payer narratives for cost‑effectiveness in vertebral augmentation.
- Competitive matrix and capability heatmaps that synthesize product attributes (viscosity, antibiotic options, radiopacity, handling time) versus commercial execution (distribution, hospital penetration, price bands).
- Clinical evidence compendium and recommended trial designs to support premium positioning, including sample size estimates, endpoint recommendations, and expected timeframes to payer acceptance.
- M&A and licensing screens identifying adjacent technologies and early‑stage innovators that could accelerate entry into high‑growth niches.
Strategic options for executives in 2026
Based on our analysis, decision makers should prioritize one of three near‑term strategies — each with clear execution checklists included in the report:
- Defend and deepen: incumbents should invest in incremental product improvements (handling, radiopacity, antibiotic integration) and evidence generation to raise switching costs and justify premium pricing.
- Focus and scale: challengers should concentrate on a single high‑value clinical niche (e.g., high‑viscosity pathological fracture indications or infection‑risk mitigation) and use regulatory agility plus targeted KOL partnerships to scale quickly.
- Partner and accelerate: smaller device firms and regional players gain faster access through distribution agreements, co‑development with implant OEMs, or selective licensing to avoid the cost and time of full regulatory dossiers in multiple jurisdictions.
What we are not publishing here (and why you should download the full report)
In line with our “trailer” approach to publishable insights, we have intentionally avoided disclosing detailed subsegment allocations, regional breakdown percentages, and granular unit economics in this press summary. Those granular slices — including precise regional shares, application mix percentages, and segment‑level pricing curves — are included only in the paid report because they are the primary competitive differentiators for commercial planning and M&A due diligence. If your 2026 plan depends on precise allocation of sales resources, price modeling at the hospital level, or target company valuation assumptions, the full dataset and interactive models in our report are indispensable.
Immediate next steps we recommend
- Initiate a rapid internal review of your 2026 product roadmap against the sterilization and biocompatibility checklist we summarize. Many foreseeable delays arise from avoidable evidence gaps.
- Map your payer and hospital customer engagements to the reimbursement playbook in our report to ensure alignment of clinical claims with CPT coding narratives.
- Run a 60‑day horizon M&A screen using the criteria we provide to identify acquisition or partnership targets that would close capability gaps in viscosity control, antibiotic loading, or distribution reach.
Conclusion and how to access the full intelligence
The Bone Cement for Spine market sits at a crossroads in 2026: enough scale to reward incumbency, but still far from commoditization in key segments where product attributes, sterility validation and reimbursement alignment determine winners. PW Consulting’s report synthesizes bench, clinical, regulatory and commercial evidence into an executable playbook to make 2026 strategic capital efficient. For the detailed regional and application splits, pricing curves, scenario models and downloadable regulatory templates that support board‑level and operating plans, download the full report from our website or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Bone Cement for Spine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


