



PW Consulting: Low and Medium Capacity Gas Generator Market Valued at USD 3,100 Million in 2025

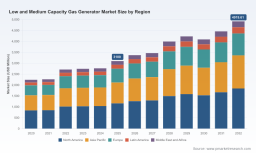
Low and Medium Capacity Gas Generator Market: Strategic Imperatives for 2026 — PW Consulting Insight
As companies reset capital plans and product roadmaps for 2026, PW Consulting’s new Low and Medium Capacity Gas Generator Market report provides the evidence-based, executable guidance executives need to convert uncertainty into competitive advantage. Anchored on a 2025 base year and a detailed historical review covering 2020–2025, the study delivers an independent view of market scale (reported in USD Million), medium-term growth dynamics and scenario-tested recommendations across OEMs, project developers, asset owners and investors. The headline: after rising from a multi-year base in 2020, the market reached roughly USD 3.10 billion in 2025 and—under our central projection—trends toward a roughly 6.82% compound annual growth rate through the 2026–2032 forecast window.
Low And Medium Capacity Gas Generator Market
Why this report matters for 2026 decision cycles
-
A changing risk calculus: volatility in fuel markets and shifting policy incentives have re-priced the economics of distributed gas generation. The market’s recent trajectory and our forecast envelope provide decision thresholds for capex approvals, product launches, and M&A screening in 2026.
Low And Medium Capacity Gas Generator Market -
From backup to value stack: buyers are increasingly assessing gas gensets not only for reliability but also for integration with hybrid systems, demand response programs and local energy markets. Our analysis surfaces which product attributes capture the highest willingness-to-pay across buyer archetypes.
Low And Medium Capacity Gas Generator Market -
Tightening regulatory backdrop: recent public policy moves and proposed adjustments to greenhouse gas reporting and tax credit regimes materially affect project-level returns. The report translates those policy shifts into quantifiable decision triggers for commercial teams and CFOs.
What’s inside — practical, transaction-ready deliverables
The full report is organized to support immediate action as well as medium-term strategy. Highlights include:
-
Market sizing and forecast methodology — transparent assumptions, sensitivity ranges and scenario runs that let buyers and suppliers stress-test plans against high and low fuel price and policy outcomes.
-
Go-to-market playbooks — segmented routes to market, commercial models, and pricing templates designed for low- and medium-capacity product families (tailored for channel, rental, project and OEM-direct models).
-
Technology & product roadmaps — assessment of engine architectures, bi-fuel and hybrid integration levers, emissions-control options, and near-term R&D priorities that unlock lifecycle cost advantages.
-
Regulatory and incentives matrix — actionable guidance on leveraging federal programs and tax instruments, and on structuring projects to preserve eligibility as reporting rules evolve.
-
Supply chain heatmaps and procurement playbooks — critical-path component risk scoring, on-shore vs off-shore sourcing trade-offs, and inventory strategies to reduce lead-time exposure.
-
Competitive benchmarking and M&A screening — comparative scorecards across manufacturing capability, systems integration, installed base service economics and platform extensibility to identify acquisition targets and partnership fits.
-
Project-level financial templates — CAPEX/OPEX modelling, TCO comparisons against alternatives, and investor-ready sensitivity tables (fuel, carbon price, uptime).
Competitive landscape — who is shaping outcomes
The low- and medium-capacity gas generator market exhibits a moderate level of concentration, with leading suppliers capturing a meaningful share but space remaining for differentiated entrants. Our report benchmarks the incumbent cohort across technical capability, channel strength and aftermarket economics.
-
Caterpillar Inc. — Well-positioned with a broad portfolio spanning continuous and standby applications. Recent product activity (for example, the introduction of the G3512 and expanded G3500-H series) underscores Caterpillar’s dual focus on emissions performance and operational continuity for mission-critical owners.
-
Cummins Inc. — Competes through integrated systems: engines plus controls and power electronics. Its emphasis on natural gas and bi-fuel solutions supports commercial and industrial use cases where fuel flexibility and system optimization matter most.
-
Generac Power Systems — A strong channel play into residential and commercial segments, with scalable approaches that enable stepwise upgrades and rental-market penetration for mid-capacity needs.
-
Kohler Co. (Rehlko) — Focuses on reliability and field-proven designs for commercial standby; innovation in controls and digital diagnostics is a core differentiator for facility managers.
-
MTU Onsite Energy (Rolls‑Royce Power Systems) — Emphasizes higher-end medium-capacity sets with sustainability features and service propositions tailored to mission-critical installations.
-
Atlas Copco AB — Offers portable and stationary equipment with an orientation toward construction and industrial temporary power markets, where mobility and rapid deployment are key.
-
Mitsubishi Heavy Industries Ltd. — Brings depth in turbine-based and medium-capacity platforms, suited for larger commercial deployments and integrated energy projects.
For commercial strategists, the takeaway is clear: incumbents compete on a mix of product breadth, service economics and integration capability. Our benchmarking highlights where premium pricing is defensible and where cost leadership wins share.
Market dynamics to watch in 2026
-
Fuel price volatility: Short-term spikes and month-to-month swings in natural gas prices materially affect dispatch economics. The market saw pronounced intra-year volatility in early 2026; scenario testing against such swings is a must for procurement and asset owners.
-
Policy and incentives: Federal funding for high-efficiency generators and recent tax code developments alter project IRRs. We map which technology options and project structures are most likely to retain eligibility under evolving rules.
-
Regulatory reporting risks: Proposed changes to greenhouse gas reporting will influence the valuation of carbon-related credits and may require changes to compliance strategies for energy projects.
-
Service and digitalization: Aftermarket and remote diagnostics are where margin pools grow. Suppliers that can monetize uptime through subscriptions or performance guarantees will capture disproportionate value.
Concrete recommendations for 2026
-
For OEMs: Prioritize modular product families that enable fast configuration for hybrid and bi-fuel options; accelerate digital telematics rollouts tied to service contracts; use scenario-based cost modelling with fuel-price stress tests to inform capex allocation.
-
For project developers and asset owners: Structure offtake agreements and hedge strategies that account for volatile fuel trajectories; exploit available federal funding windows for high-efficiency systems; design procurement specifications that preserve future conversion pathways (e.g., hydrogen-ready interfaces).
-
For investors and M&A teams: Focus diligence on installed-base service economics and control-platform portability; screen targets for software-enabled revenues and clear paths to margin expansion through aftermarket offerings.
-
For utilities and large consumers: Revisit distributed generation strategies to combine resiliency with market participation; evaluate embedded generation as grid deferral alternative using our TCO templates under multiple fuel price and regulatory scenarios.
How to use this intelligence in 90 days — a pragmatic roadmap
-
0–90 days: Run a rapid portfolio assessment using the report’s stress-testing templates; prioritize retrofit candidates and pilots where federal incentives materially improve returns.
-
90–360 days: Implement product or service pilots that bundle remote diagnostics, uptime guarantees and flexible fuel options; begin supplier rationalization using the supply‑chain heatmaps.
-
12–36 months: Scale modular platforms and roll out integrated commercial models (subscription or availability-based pricing), while preparing for longer-term decarbonization options.
Where this “trailer” leaves you — and what the full report provides
This preview demonstrates the depth of PW Consulting’s proprietary analysis—transparent forecasting, scenario-tested financials and execution-ready playbooks—designed to de-risk 2026 spending decisions. To preserve the commercial integrity of our datasets and the competitive advantage they confer, detailed segment tables, granular regional and application splits, and company-level scorecards are contained in the full report and accompanying dashboards.
Clients and decision-makers preparing budgets, product roadmaps or M&A pipelines for 2026 will find the full report indispensable. It includes downloadable financial models (USD Million), customizable scenario inputs, and a ranked list of strategic moves mapped to ROI timelines. For an executive briefing or to access the dataset and model licenses, contact PW Consulting to arrange a tailored walkthrough.
Final note
The low and medium capacity gas generator market is at an inflection: technology capability, fuel economics and policy incentives are converging to reshape where and how these assets deliver value. PW Consulting’s 2026-focused guidance equips leaders to make timely, defensible choices—balancing short-term volatility with a clear, strategic path to sustainable returns.
For detailed analysis of this topic, please visit the official page: Low And Medium Capacity Gas Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


