



PW Consulting: TDI 80/20 market at USD 2.85B in 2025, set to grow at 3.8% CAGR to ~USD 3.7B by 2031 as Asia‑Pacific claims nearly 48% share

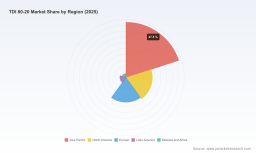
TDI 80/20 Market: Strategic Imperatives for 2026 — A PW Consulting TDI 80/20 Market Brief
As corporate leaders plan capital allocation, procurement strategy, and product roadmaps for 2026, the TDI 80/20 isomer blend emerges as a quietly pivotal raw material shaping competitive positions across flexible polyurethane foam, CASE (coatings, adhesives, sealants, elastomers), and specialty foam applications. PW Consulting’s TDI 80/20 Market TDI 80/20 Market report synthesizes market-scale dynamics, supply structure, regulatory risk and technology-driven efficiency gains into a decision-ready playbook. This brief highlights the report’s strategic value for 2026 while preserving the proprietary segmentation and scenario outputs that we hold as report gated content.
TDI 80/20 Market
Why TDI 80/20 matters to 2026 corporate strategy
-
Macro stability with selective disruption: Our base-year analysis (2025) positions the global TDI 80/20 market as a multi-billion-dollar market (USD, revenue unit: Million). Under the central forecast, the market grows at a mid-single-digit CAGR through the 2026–2032 horizon (3.8%), reflecting stable underlying demand in flexible foam applications alongside episodic cost and regulatory shocks.
TDI 80/20 Market -
Concentrated supply, concentrated leverage: The market’s supply side is meaningfully concentrated: the top three producers control a clear majority share while the top five capture nearly four-fifths of global production capacity. For buyers, this concentration translates into counterparty risk and price-setting power that must be actively managed. For producers and investors, consolidation dynamics create scalable advantages for those who can optimize feedstock integration and logistics.
TDI 80/20 Market -
Cost structure sensitivity: TDI manufacturing remains tightly coupled to upstream aromatics and energy markets and is exposed to intermittent feedstock price shocks and logistics disruptions. Marginal cost movements reverberate quickly through contract negotiations in foam, CASE and related downstream segments.
What PW Consulting’s report delivers (practical content for 2026 decisions)
-
Actionable market sizing and bottom-up demand forecasts: We present a year-by-year market size model anchored to 2025 with scenario-based trajectories to 2032, isolating the effects of end-use demand, substitution dynamics and regulatory headwinds.
-
Supply-side mapping and scenario playbooks: The report maps incumbent and emergent producers, technology variants (liquid-phase vs gas-phase phosgenation, purity differentials), incremental capacity projects, and plant-level risk assessments — all organized to support negotiations, hedging and sourcing decisions.
-
Cost and margin response toolkit: We provide a workbook logic for building feedstock pass-through clauses, contract indexation templates, and stress-tested margin simulations that finance teams can operationalize in supplier contracts and internal planning cycles.
-
Regulatory and safety compliance playbook: Beyond a summary of current frameworks, the report lays out pragmatic steps to reduce compliance cost, optimize occupational safety investments, and structure insurance and contingency plans under tightening chemical-control regimes.
-
M&A and JV decision framework: For strategic investors, the report contains a checklist and valuation multipliers adjusted for concentration, scale economies, and feedstock integration premium — with sensitivity to policy and trade interventions.
-
Commercial go-to-market blueprints: For foam OEMs and formulators, the report includes SKU-level impact guidance (purity and additive interactions), sourcing scorecards, and supplier selection matrices tailored to regional logistics and product quality tolerances.
Competitive landscape: implications for buyers, sellers and investors
The TDI 80/20 market is dominated by a small set of global and regional champions with distinct strategic postures. Understanding each archetype is critical when shaping procurement strategies, partnership outreach, or acquisition targets.
-
Integrated scale leaders: Established integrated chemical majors retain a strategic edge through feedstock integration, global distribution networks and long-standing consumer relationships. Their investments in energy efficiency and modernization are lowering operating intensity and CO2 footprints — an important competitive lever in procurement dialogs and sustainability positioning.
-
Technology-differentiated players: Producers using advanced process technologies (including modernized gas-phase systems) can supply higher-purity streams and win specifications in premium bedding, automotive seating and specialty CASE applications. These capabilities translate to pricing power in quality-sensitive channels.
-
Regional champions: Local producers in high-demand regions play a volume-and-service game — offering proximity, rapid logistics and customs familiarity. However, these players are exposed to feedstock availability and regulatory shifts that can alter regional cost curves quickly.
-
Recent strategic moves: In the past 18 months, leading firms have prioritized capacity additions and plant modernizations, while some markets have tightened import measures and trade remedies. For corporate strategists, these moves meaningfully reshape sourcing grid options and justify contingency inventory planning or dual-sourcing strategies.
Market dynamics and risk vectors to monitor in 2026
-
Feedstock volatility: Aromatics and energy price moves materially change TDI cost profiles. Procurement teams should bake-in scenario stress tests and consider financial hedging or long-term indexation clauses to protect margins.
-
Regulatory escalation: TDI is controlled under strict worker-safety and chemical management frameworks globally. Expect compliance costs to rise with tighter exposure limits, stricter handling rules and expanded reporting obligations in key consuming regions. These changes have direct implications for plant retrofit CAPEX and operating expense trajectories.
-
Trade and policy interventions: Governments in some demand centers are maintaining or initiating trade remedies and anti-dumping measures that alter import economics; commercial and legal teams should incorporate tariff scenarios into sourcing and price-setting models.
-
Decarbonization and energy efficiency: Plant modernizations that deliver significant energy and emissions reductions are accelerating. Buyers and investors should factor supplier-level emissions intensity into longlists and consider contracting with partners demonstrating measurable improvements.
-
Supply concentration risk: High concentration among a few suppliers means operational disruptions, major project commissioning and strategic alliances can tilt regional availability. Contingency planning — including alternate feedstock pathways or temporary formulation adjustments — should be part of continuous sourcing playbooks.
Strategic recommendations — 6 practical moves for 2026
-
Implement dynamic sourcing scorecards: Upgrade supplier evaluation to include not only price and lead time but also process technology, emissions profile, and regulatory resilience. Treat supplier selection as a portfolio optimization problem rather than a bilateral negotiation.
-
Lock in flexible contract mechanics: Negotiate hybrid contracts that combine fixed volumes with index-linked tranches and force majeure protections calibrated to chemical-specific risks.
-
Prioritize supplier modernization partners: Where product premium permits, prefer suppliers that have demonstrable energy efficiency and emissions reductions — these will face lower compliance costs and less risk of shutdowns under stricter regulations.
-
Stress-test M&A targets against policy scenarios: For acquirers, stress test valuations against trade remedy persistence, feedstock shocks and required safety CAPEX to avoid overpaying for perceived scale alone.
-
Operationalize inventory and logistics buffers: Given regional trade measures and concentration risk, maintain tactical buffer stock policies and diversify logistics nodes to minimize production interruptions.
-
Invest in formulation flexibility: R&D teams should prioritize formulations that can tolerate minor feedstock variability or enable substitution pathways to reduce single-supply dependency.
How PW Consulting’s report supports execution
The full TDI 80/20 Market TDI 80/20 Market report contains the granular models, contract templates, plant-level risk matrices and scenario outputs that corporate teams need to operationalize the strategic recommendations above. It combines quantitative market sizing (anchored to 2025 base-year figures and projection models through 2032 at an aggregate CAGR of 3.8% in the forecast window) with qualitative field intelligence gathered from supply-chain actors, plant visits, and regulatory authorities.
We deliberately structure the report to serve as an execution tool — not just an intelligence brief — with downloadable financial models, procurement playbooks, and an M&A valuation checklist tailored to the TDI 80/20 value chain. To protect competitive sensitivity and support depth of insight, segment-level numbers and plant-capacity matrices are maintained behind our report access portal.
Next steps for decision-makers
-
Procurement leaders should request the supplier risk matrix and the indexation clause templates to begin renegotiations this quarter.
-
Corporate development and private equity teams should leverage our M&A stress-test workbook before entering LOI stages for regional assets.
-
Operations and sustainability teams should review the plant modernization benchmark to prioritize retrofit CAPEX that yields cost and emissions co-benefits.
PW Consulting’s TDI 80/20 Market TDI 80/20 Market report is designed as the practical, decision-grade resource for 2026. For the full dataset, plant-level assessments, and the executable templates described above, please visit the PW Consulting report page or contact our advisory desk to request access. Our analysts stand ready to run custom scenarios tailored to your portfolio, sourcing footprint, and risk tolerance.
For detailed analysis of this topic, please visit the official page: TDI 80/20 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


