



PW Consulting Forecasts LCP Antenna Market to Reach USD 2,475.5 Million in 2025, Rising at a 17.98% CAGR to USD 7,876.3 Million by 2032

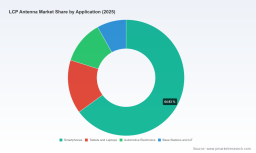
LCP Antenna Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive summary
As wireless ecosystems move deeper into mmWave, high‑frequency 5G and emerging satellite and IoT node topologies, Liquid Crystal Polymer (LCP) antennas are transitioning from niche premium components to an essential design lever for performance, miniaturization and thermal stability. PW Consulting’s latest LCP Antenna Market report uses a 2025 base year and an expanded 2026–2032 forecast horizon to deliver an actionable roadmap for C‑suite leaders, procurement heads and product strategists.
Lcp Antenna Market
Key macro takeaways: the global market exceeded the USD 2.4 billion mark in 2025 and is forecast to expand at a near‑18% CAGR through 2032, reaching roughly USD 7.9 billion by the end of the forecast period. Market concentration is meaningful — the top three players account for well over half of supply, and the top five approach near‑total dominant share — conditions that create both barriers and strategic opportunities for new entrants and incumbents alike.
Lcp Antenna Market
Why this matters for 2026 decision cycles
-
Capital allocation: With a sustained high growth rate, investment windows for capacity expansion, test and measurement capability and packaging automation are time‑sensitive. Boards deciding CAPEX vs. M&A must weigh rapid top‑line expansion against supply chain constraints.
Lcp Antenna Market -
Roadmap prioritization: Product teams must choose where to migrate to LCP‑based antennas versus alternative substrates to balance cost, RF performance and form‑factor gains. The technical and commercial inflection is now — delayed decisions risk forfeiting handset or module BOM slots.
-
Sourcing and localization: Geopolitical trade measures and concentrated resin supply create short‑ to medium‑term sourcing risk. Procurement strategies that blend dual‑sourcing, regional inventory buffers and long‑lead supplier agreements will materially reduce project volatility.
Market trajectory — what the numbers conceal and reveal
The headline CAGR (≈17.98%) and the projection to roughly USD 7.9 billion by 2032 signal a market in scale‑up mode rather than steady maturation. That pace is being driven not only by handset adoption but by a widening set of high‑frequency applications — from compact base station components to advanced automotive radar and premium IoT devices — that demand the low dielectric loss, dimensional stability and high‑frequency handling of LCP substrates.
Importantly, growth is not evenly distributed: technology, supply chain placement and OEM ecosystem dynamics create winner‑takes‑much pockets. This is reflected in concentration metrics and the pattern of recent commercial wins and volume ramps documented in our coverage.
Competitive landscape — strategic dynamics to watch
PW Consulting’s competitive analysis synthesizes technical capability, customer alignment and go‑to‑market positioning among the market’s relevant players. A few illustrative dynamics:
-
Large, diversified electronics incumbents have leveraged system‑level relationships to secure early, high‑volume allocations for LCP antenna modules — turning customer intimacy into scale advantages. Recent publicized production ramps demonstrate how design wins convert quickly into manufacturing leverage.
-
Tier‑1 interconnect and component suppliers with strong materials expertise are integrating vertically into LCP antenna subassemblies to capture higher value‑add and protect margin pools against commoditization of raw laminates.
-
Regional specialists and flexible PCB houses are differentiating through cost engineering and proximity to consumer electronics OEMs, supporting rapid qualification cycles for handset launches.
Case signals from the market: one major supplier began mass production of a compact 28 GHz antenna‑in‑package module and reported multi‑million unit monthly shipments into a single handset customer during early 2025 — a concrete example of how technical readiness and a channel relationship can unlock scale. Another leading connectivity supplier launched an LCP module that materially reduced signal loss at mmWave bands — a product performance delta that directly influences OEM material selection debates.
Supply chain, materials and regulatory dynamics — risks that require strategic hedging
-
Raw material concentration: Global LCP resin capacity is notably concentrated in a handful of suppliers, with one producer accounting for a near‑third share of resin capacity following a major asset consolidation. This concentration creates susceptibility to capacity outages, price steps and contractual power shifts.
-
Upstream specialty monomers and film‑grade resin sourcing are patchy. New entrants in China are moving toward pilot and batch supply for film‑grade LCP, but technology qualification and scale timelines introduce medium‑term uncertainty.
-
Trade and regulatory pressure: Cumulative tariff regimes and import measures on polymer‑based electronic components add a non‑trivial layer to landed cost. In parallel, LCP antenna products must navigate certification frameworks (e.g., FCC, CE), which introduce both testing cost and time‑to‑market friction.
-
Price and lead‑time volatility: Specialty polymer supply chains can experience price shocks due to constrained monomer availability, generating project‑level margin variance and inventory policy implications.
What PW Consulting’s report delivers (practical, actionable content)
Our report is intentionally structured to move organizations from uncertainty to execution. Key deliverables include:
-
Decision playbooks: Concrete recommendations for CAPEX timing, supplier qualification milestones and a procurement scorecard that maps supplier capability to risk tolerance.
-
Go‑to‑market tactics: Bundled model options for suppliers (e.g., contract manufacturing partnerships, co‑development agreements, licensing of antenna IP) that accelerate OEM qualification while protecting margin.
-
Scenario‑based financial models: Three strategic scenarios (conservative, base, upside) that translate market growth assumptions into revenue and capacity needs for 2026–2028 planning cycles. Models are provided in editable formats to allow rapid stress‑testing against your internal assumptions.
-
Supply‑chain heatmaps and mitigation templates: Prioritized actions to reduce single‑source exposure, hedge resin cost risk and align inventory policies with launch calendars.
-
Competitive dossier: Profiles and capability matrices for leading players, including production footprints, recent product introductions, and customer alignment — enabling quicker partner selection and acquisition screening.
-
Regulatory & certification checklist: Turnkey test and compliance roadmaps for device OEMs and module houses entering or scaling LCP antenna integration.
How senior leaders should apply these insights in 2026
-
CEOs and Boards — Treat LCP as a strategic domain, not just a procurement line item. Consider targeted M&A or JV moves to secure resin or module capacity where internal scale is insufficient.
-
Heads of Product — Integrate antenna substrate choices into product spend gates earlier. Performance wins at mmWave are frequently decided at prototype and early qualification stages; late substrate swaps carry significant cost and schedule penalties.
-
Procurement & Supply Chain — Move from transactional buying to supplier partnership agreements that include capacity reservations, hedged pricing instruments and joint contingency plans for material dislocations.
-
R&D and Test — Prioritize mmWave testbeds and environmental qualification for LCP assemblies to shorten qualification cycles with OEMs and tier‑one partners.
Competitive moves to expect and prepare for
Given the high growth and concentrated supplier base, expect continued vertical integration by system suppliers, aggressive capacity expansions by key resin producers, and strategic partnerships between flexible PCB houses and materials providers. OEMs under time pressure will increasingly favor suppliers that can demonstrate both technical performance at mmWave bands and resilient, geo‑diverse supply chains.
Why PW Consulting’s intelligence is uniquely actionable
-
We combine granular production‑level intelligence (validated production ramps, product loss‑reduction claims, contract allocations) with macro supply modeling to highlight where near‑term bottlenecks will create pricing or allocation windows.
-
Our playbooks translate market signals into executable steps — from contract templates to sourcing scorecards — that reduce analysis paralysis and accelerate decision velocity.
-
The report intentionally reveals strategic implications while withholding select granular segmentation tables in the public summary, to preserve the competitive value of the full dataset for subscribers and paying clients.
Next steps and call to action
For leaders planning 2026 budgets and product roadmaps, the critical window for decisive action is now. PW Consulting’s LCP Antenna Market report equips teams with the market sizing, concentration analysis and supplier dossiers necessary to move from planning to procurement and production. To access the full datasets, regional and application segmentation, and editable scenario models referenced in this release, consult the full report page and speak with our advisory team for a tailored briefing.
Closing note
LCP antenna technology is at a strategic inflection point. Firms that combine a precise understanding of market scale and concentration with disciplined supply‑chain hedging and early design‑in will capture disproportionate share of the growth opportunity. PW Consulting’s research is designed to be the practical playbook you consult when translating that strategic intent into board‑approved actions in 2026.
For detailed analysis of this topic, please visit the official page: Lcp Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


